

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
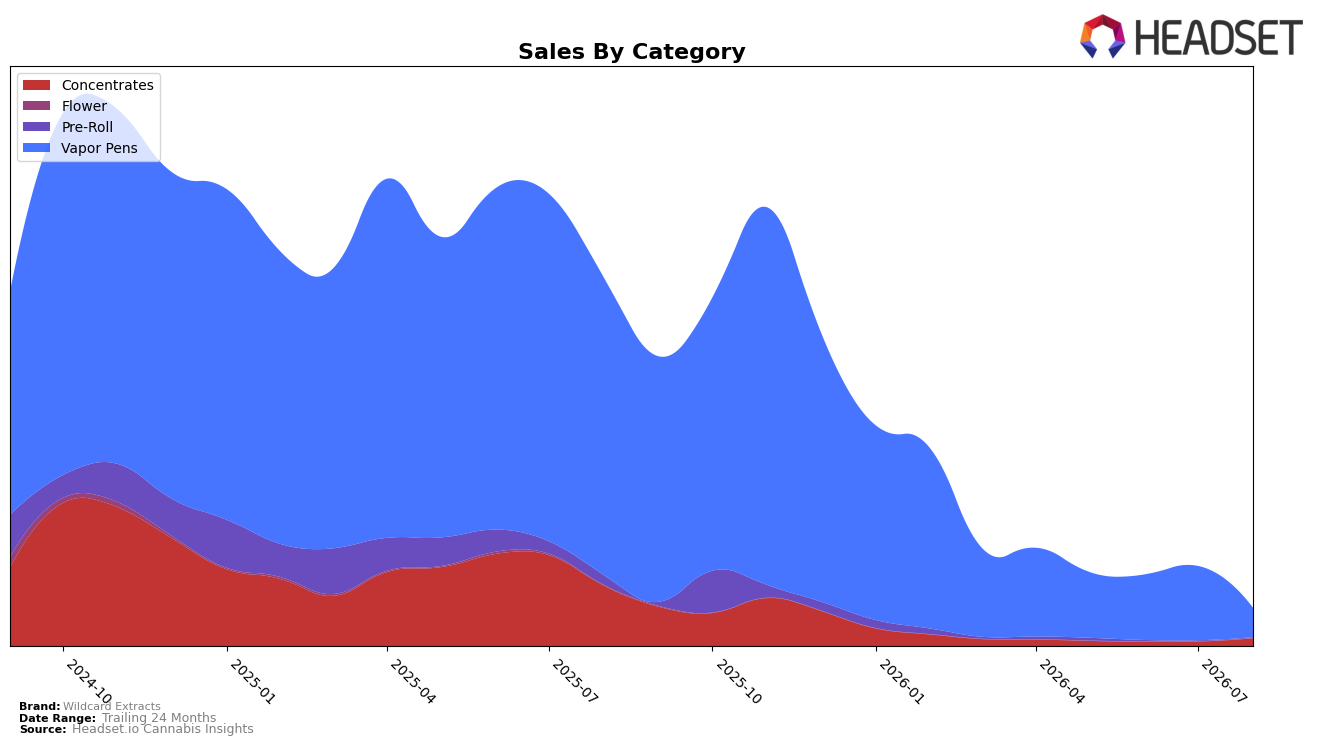
By August 2026, Wildcard Extracts concentrated 78.41% of sales in Vapor Pens with a month-over-month decline of 60.74% and a year-over-year drop of 90.23%, while Concentrates rose to 20.57% share on a 73.08% MoM increase despite an 87.36% YoY contraction; Pre-Roll slipped to 1.02% share with a 30.96% MoM decline and a 95.97% YoY fall. The average price fell 5.02% YoY to $38.68, and within the lead segment Vapor Pens priced at an average of 41.60, indicating that the shift in mix toward a lower-priced Concentrates set is not enough to offset steep volume attrition; the pattern implies category reliance risk with a late-cycle pivot into Concentrates that is gaining monthly traction but from a much smaller base.
In British Columbia Vapor Pens, Wildcard Extracts held rank 54 while Vapor Pens still accounted for 78.41% of total brand sales and fell 60.74% MoM, signaling weakened shelf velocity relative to the province’s segment and limited ability to convert share into rank gains; meanwhile, Concentrates’ 73.08% MoM growth to 20.57% share suggests a tactical hedge but not yet a leadership path. The combination of a 90.23% YoY contraction in the anchor category and a 95.97% YoY drop in Pre-Roll positions the brand as overexposed to a declining core, so near-term positioning hinges on whether Concentrates’ MoM momentum can be scaled without eroding margin as average price trends 5.02% lower YoY.
Competitive Landscape
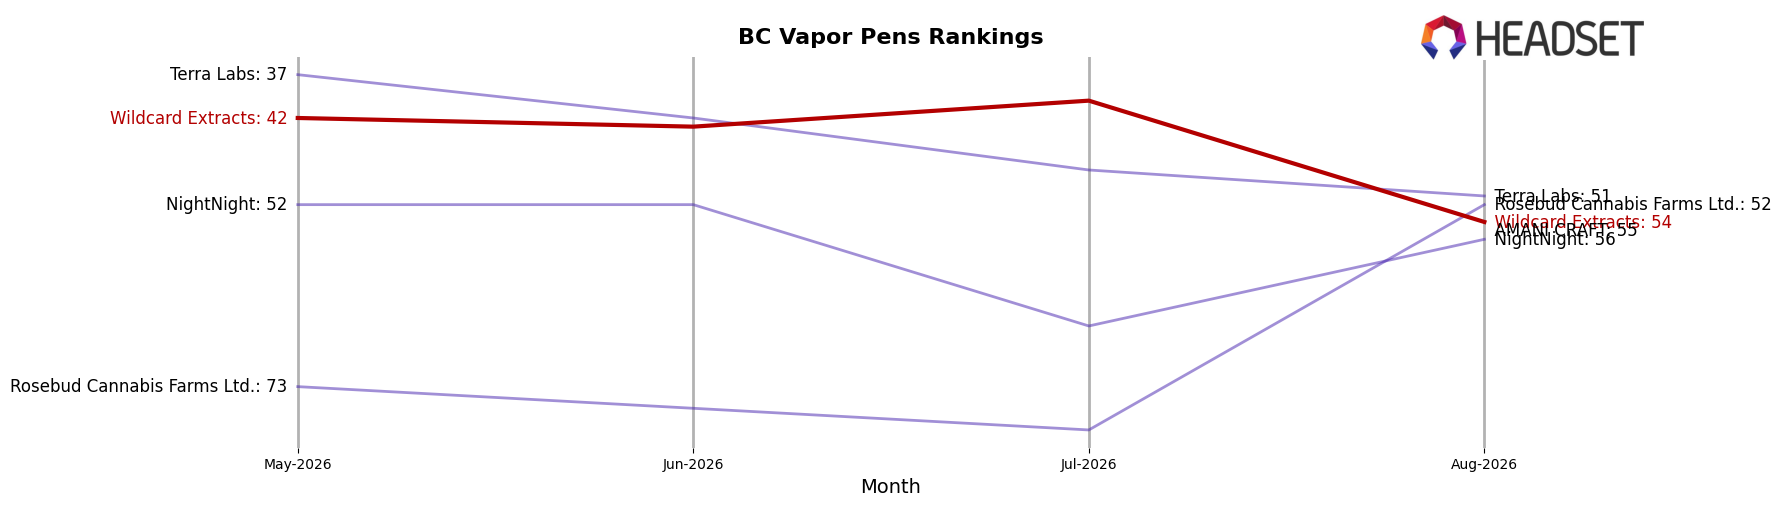
Wildcard Extracts sits at rank #54 in BC Vapor Pens in August 2026, down 38 places year over year from #16 and down 12 places since May 2026 when it was #42; this follows a prior peak at #5 in October 2025, indicating a sustained slide rather than a monthly blip. Meanwhile, Spinach rose to #1 from #3 with 242.2% YoY sales growth, and Back Forty / Back 40 Cannabis advanced to #5 from #7 with 76.5% YoY sales growth, while BoxHot edged up to #2 from #1 with 15.4% YoY growth—collectively showing competitors gaining or holding top-five positions as Wildcard Extracts moves out of the top 50. The pattern implies Wildcard Extracts is ceding share to faster-accelerating leaders, and unless rank reverses toward the prior #5 peak, the brand’s trajectory points to diminishing relevance in high-volume tiers.
Notable Products
Ziestaz Shatter (1g) posted the standout move in August 2026 with a +152% month-over-month surge to rank 2, while G Wagon Cured Resin Cartridge (1g) fell -58.7% yet still held rank 1, indicating volatility at the top rather than a clear handoff. Vape SKUs compressed broadly with Mint Chip FSE Cured Resin Cartridge (1g) down -83.0% at rank 7 and Rainbow Marker Cured Resin Cartridge (1g) down -79.1% at rank 7, whereas Dancehall Cured Resin Cartridge (1g) was an outlier at +13.9% in rank 4; the pattern points to uneven demand within Vapor Pens rather than a category-wide collapse. Two Concentrates landed in the top three as Space Panda Live Resin (1g) slipped only -3.8% at rank 3 alongside the Ziestaz jump, and four of the top ten are Vapor Pen SKUs despite steep declines, implying the brand is leaning into a high-churn pen portfolio while Concentrates provide the current growth spark.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

