
Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
CAMP (NV) is stocked at 30 licensed dispensaries across Maine and Nevada, 16 of them in Maine, with the deepest coverage in Bangor, Auburn, Berwick, Boothbay, and Brewer. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
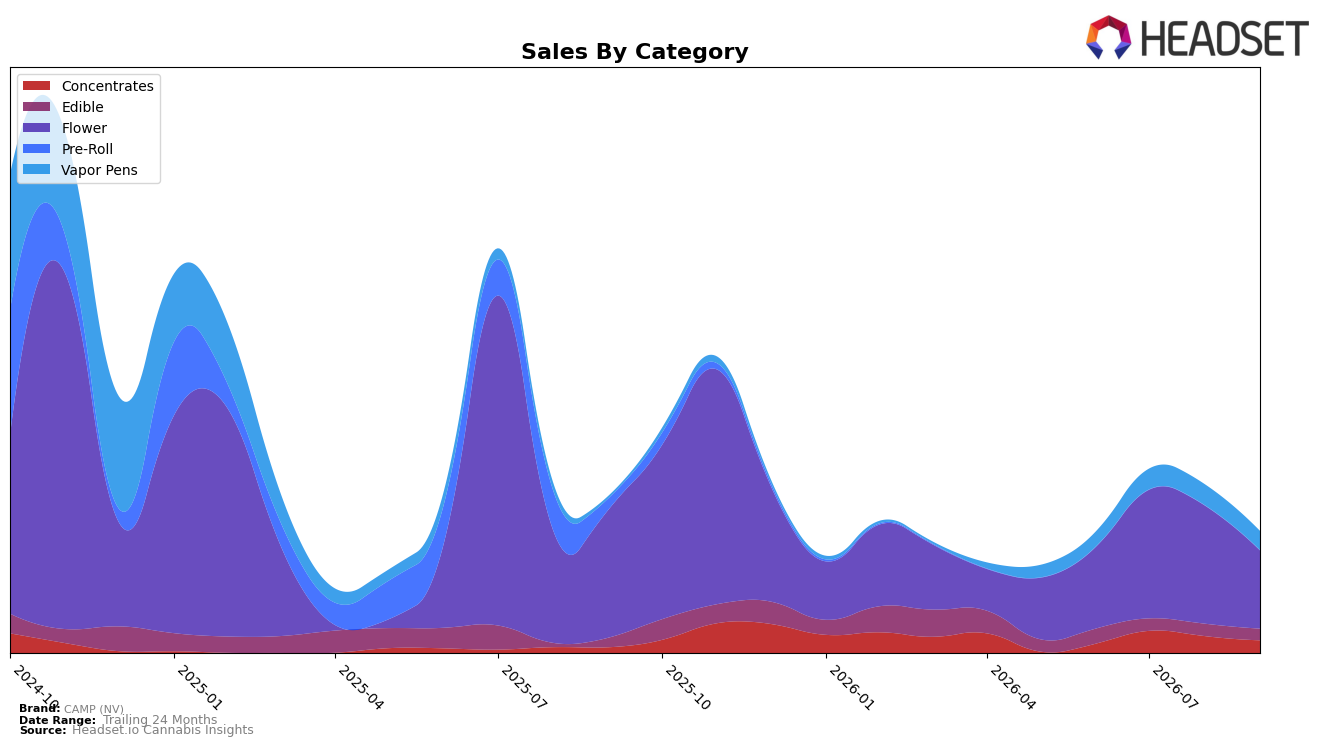
CAMP (NV) concentrated 64.49% of September 2026 sales in Flower, down 38.89% year over year and 33.94% month over month, while ranking 26 in Flower within Nevada; this heavy mix weight, paired with a -22.45% brand-level YoY sales decline and a 15.97% YoY increase in average price to $18.34, indicates the core category is dragging overall performance despite pricing uplift. Meanwhile, Vapor Pens expanded to a 15.62% share with 755.98% YoY growth but slipped 8.69% MoM, and Concentrates reached 10.50% share with 121.13% YoY growth but fell 25.08% MoM; alongside Edible at 9.39% share with 23.60% YoY growth and a 6.11% MoM dip, the portfolio shows rapid YoY diversification countered by near-term pullbacks, implying mix volatility rather than stable expansion.
The pattern implies a necessary pivot away from Flower dependence: the 64.49% Flower share combined with a 26th rank signals limited headroom, while triple‑digit YoY growth in Vapor Pens (755.98%) and Concentrates (121.13%) suggests categories where share gains can offset Flower contraction if MoM softness is managed. With Edible up 23.60% YoY yet down 6.11% MoM, and both Vapor Pens and Concentrates posting MoM declines of 8.69% and 25.08% respectively, near-term execution should target sustaining repeat velocity and price-pack architecture to convert the YoY gains into consistent share, implying CAMP (NV)’s positioning is shifting toward a multi-category portfolio that reduces risk concentration in Flower and competes on breadth rather than rank in a single category.
Competitive Landscape
CAMP (NV) sits at rank #26 in NV Flower in September 2026, down 7 positions year over year from #19, and 2 positions lower than June 2026’s #24, indicating slippage from its peak at #4 in November 2024; meanwhile, category leaders like RYTHM at #1 with +19.7% YoY sales and STIIIZY at #2 with +24.2% YoY sales are widening distance, while Alternative Medicine Association / AMA improved from #5 to #3 alongside +32.6% YoY, and Neon Moon climbed from #9 to #4 with +82.7% YoY, signaling that CAMP (NV)’s rank trajectory implies share pressure as faster-growing rivals consolidate top-10 positions and pull demand away from the mid-20s tier.

Notable Products
007 Up (3.5g) posted the steepest decline at -76.4% MoM while sliding to rank 8, whereas Glitter Bomb (3.5g) delivered the largest MoM gain at +55.3% to reach rank 2; this divergence implies a portfolio pivot away from underperforming Flower SKUs toward a narrower set of winners. First Class Funk #5 (3.5g) held rank 1 with +30.3% MoM, and four of the top ten are Flower SKUs clustered in ranks 1–4, indicating the top of the chart is concentrated in inhalable flower despite volatility at the lower end. Vapor Pens maintained presence with Glitter Bomb Flower Rosin Cartridge (0.5g) at rank 5 on +18.1% MoM and Bushido OG Live Rosin Disposable (0.5g) at rank 10 on $13,637, suggesting secondary momentum in rosin-based formats that can be extended from flagship strains. The mix points to CAMP (NV) consolidating around a few high-velocity Flower leaders while testing rosin extensions to stabilize category breadth.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

