

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
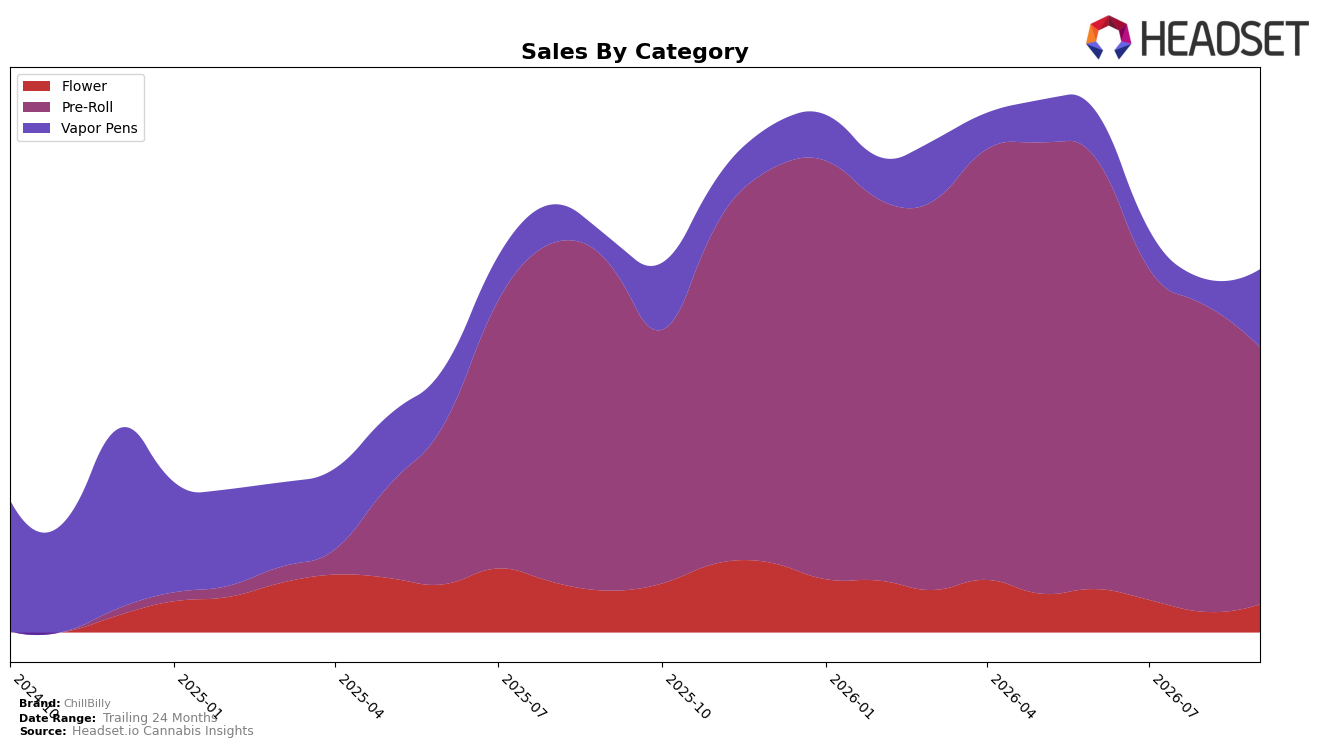
In September 2026, ChillBilly’s category mix pivoted away from Pre-Roll as its 70.85% share carried double declines, with year-over-year at -21.68% and month-over-month at -16.28%, while Vapor Pens surged to 21.44% share on triple-digit gains of 207.67% YoY and 201.73% MoM. Flower held 7.71% share with a split signal—down -32.69% YoY but up 37.67% MoM—suggesting short-term trial rather than a structural rebound; the overall average price dipped -2.42% YoY even as Vapor Pens’ average price sat near the brand mean, pointing to mix rather than discounting as the driver. With Pre-Roll rank at 34 in British Columbia, the simultaneous share expansion in Vapor Pens and contraction in Pre-Roll implies a deliberate rebalancing to reduce dependence on a weakening core while preserving volume through faster-growing formats.
The September 2026 shifts imply ChillBilly is trading category depth for breadth: Pre-Roll concentration at 70.85% alongside a Pre-Roll rank of 34 in British Columbia caps headroom, whereas Vapor Pens’ 201.73% MoM surge and 207.67% YoY growth create a second engine without requiring heavy price cuts, given the -2.42% YoY average price movement. Flower’s +37.67% MoM lift amid a -32.69% YoY backdrop suggests incremental distribution or promotional wins that may not compound, so sustaining the portfolio hinge rests on Vapor Pens continuing to absorb share while Pre-Roll stabilizes; this positioning signals a shift toward a two-format strategy aimed at volatility buffering and margin preservation.
Competitive Landscape
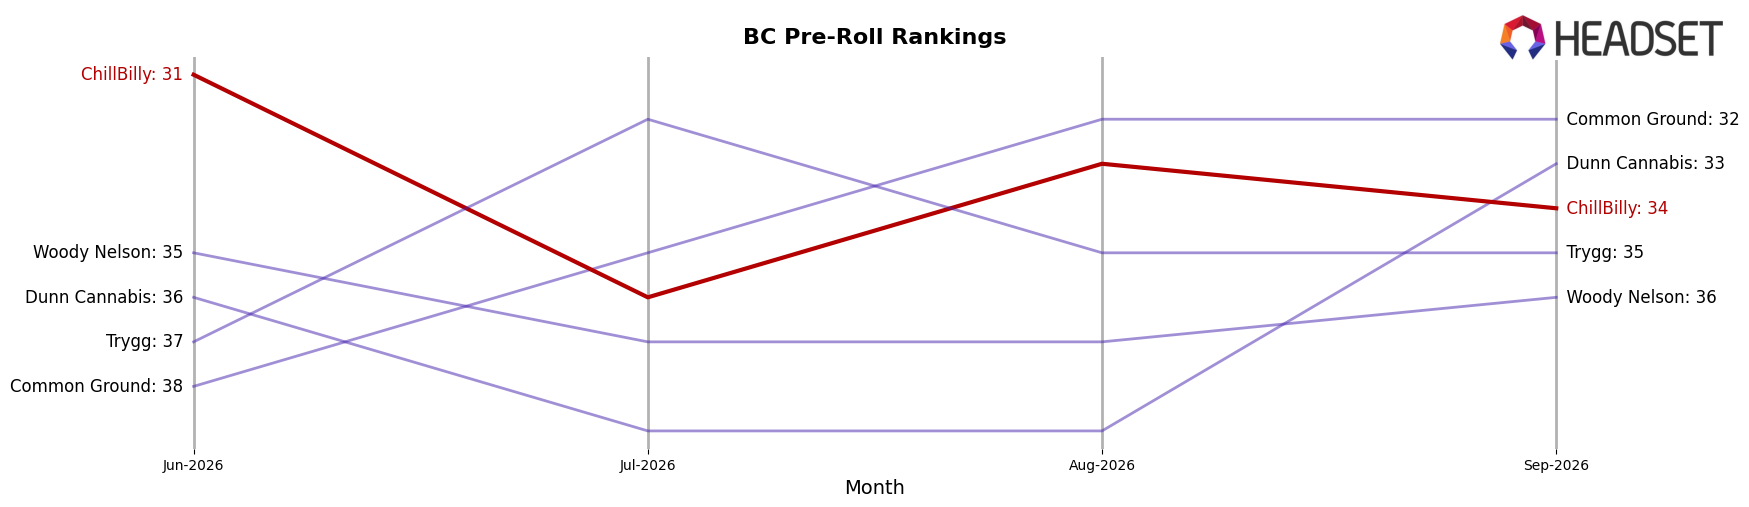
ChillBilly sits at rank #34 in BC Pre-Roll for September 2026, improving 1 position year over year from #35 while slipping 3 spots since June 2026 from #31; its peak at #22 in May 2026 contrasts with the current placement by 12 ranks. Among competitors, Weed Me rose from #2 to #1 with 28.6% YoY sales growth, and Back Forty / Back 40 Cannabis jumped from #13 to #2 alongside a 197.3% YoY sales increase, while General Admission slid from #1 to #3 with an 8.5% YoY decline; relative to these moves, ChillBilly’s 1-rank YoY gain but 12-rank gap from its May 2026 peak implies a mid-year fade that risks entrenchment in the 30s unless regained momentum converts into sustained rank recovery.
Notable Products
Max 60's - Blood Orange Triple Diamond Infused Pre-Roll 3-Pack (1.35g) posted the steepest decline at -44.45% month over month while sitting at rank 6, and Max 60's - Blue Lemonade Triple Infused Pre-Roll 3-Pack (1.35g) fell -22.27% at rank 2, signaling pressure on infused Pre-Rolls even near the top of the chart. In contrast, Jack Herer (3.5g) climbed +35.84% month over month to rank 4, while Max 60's - Frosted Grape Triple Diamond Infused Pre-Roll 3-Pack (1.35g) edged up +5.40% at rank 1, creating a split where Pre-Roll leaders hold share but not momentum. Four of the top ten are Pre-Roll SKUs, yet two of those lost at least -22% month over month and one more declined -25.77% at rank 8, implying the format remains central but flavor-led triples face volatility versus classic Flower and nascent Vapor Pens. The pattern implies ChillBilly is pivoting from concentrated reliance on triple-infused Pre-Rolls toward a more balanced mix where stable Flower and growing Vapor Pens can absorb category swings and protect rank positions.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

