

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Community Cannabis is stocked at 86 licensed dispensaries across California and Oregon, 57 of them in California, with the deepest coverage in Los Angeles, San Diego, Long Beach, San Francisco, and Blythe. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
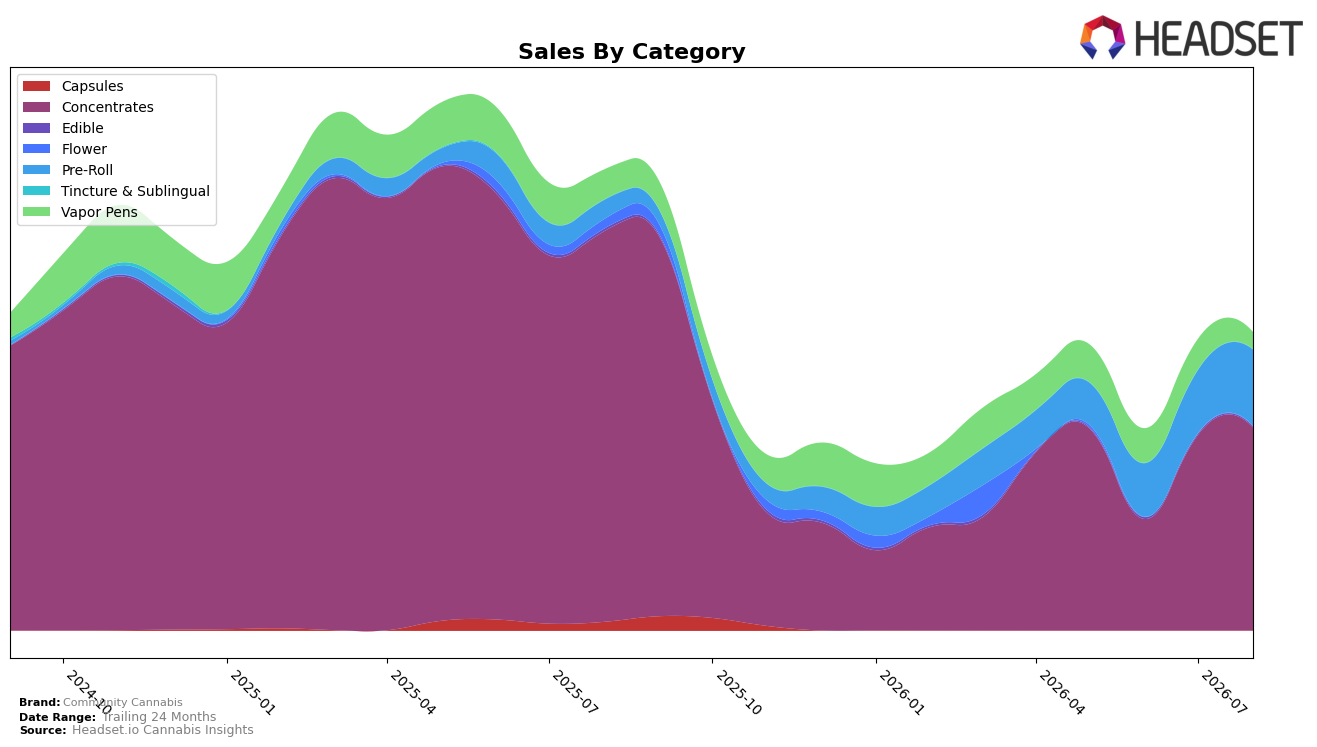
Community Cannabis concentrated its August 2026 mix in Concentrates at 68.45% share with a 3.80% month-over-month lift yet a 48.10% year-over-year decline, while Pre-Roll expanded to 25.65% share with 20.94% month-over-month growth and a 305.06% year-over-year surge. Vapor Pens compressed to 5.62% share with a 45.15% month-over-month drop and a 43.998% year-over-year decline, and Edible held 0.28% share with a 16.40% month-over-month decline and a 60.77% year-over-year fall. With brand sales down 35.48% year over year and average price down 36.54%, the pattern implies a deliberate pivot toward value-forward Pre-Rolls while defending a still-dominant but contracting Concentrates core.
Given a number 20 rank in Concentrates in California and a 68.45% category share inside the portfolio, incremental gains in Pre-Roll at 25.65% appear to trade margin for volume as average price sits at $21.98. The simultaneous 3.80% month-over-month uptick in Concentrates alongside a 20.94% month-over-month surge in Pre-Roll implies a barbell approach that stabilizes the core while accelerating a lower-priced entry point; however, the 45.15% month-over-month decline in Vapor Pens and 16.40% month-over-month decline in Edible suggest intentional deprioritization of peripheral formats to concentrate resources on the two primary lanes.
Competitive Landscape
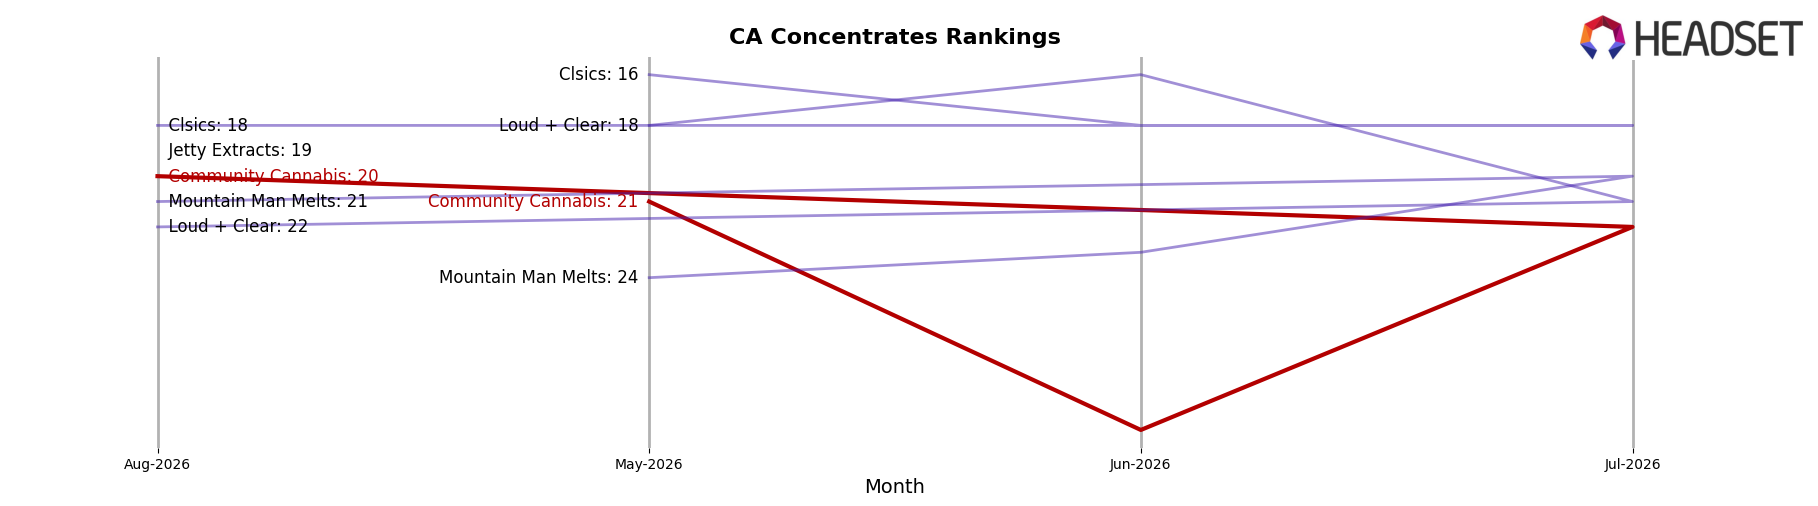
Community Cannabis sits at rank #20 in August 2026 in CA Concentrates, down 10 positions year over year from #10, and nearly flat versus May 2026 at #21; this slippage contrasts with Raw Garden holding #1 year over year at #1 with a 9.9% sales lift and 710 Labs advancing from #4 to #2 alongside a 33.5% YoY sales increase. While Community Cannabis once peaked at #8 in April 2025, its current placement at #20 and a 1-rank improvement from the trailing three months indicate stalled momentum relative to peers like STIIIZY slipping from #2 to #3 with a -2.3% YoY sales change but still outperforming on rank; the pattern implies Community Cannabis is ceding rank to faster-advancing incumbents and must reverse multi-quarter erosion to avoid drifting further from its prior #8 ceiling.
Notable Products
Bird Watchers Blunt 2-Pack (2g) posted the headline move in August 2026 with a +98% month-over-month surge to the number 1 rank, while Purple Hills Pre-Roll 2-Pack (2g) fell 27% and slipped to rank 2. Bakery Pre-Roll 14-Pack (7g) also accelerated with an +81% increase at rank 4, and three of the top four ranks are Pre-Rolls, indicating a concentrated shift toward multi-pack inhalables. Onesie Pre-Roll (1g) rose 49% but remained at rank 3 behind the larger pack formats, whereas Peach Panther Cold Cure Rosin (1g) declined 32% at rank 6, creating a divergence between Pre-Rolls and Concentrates. The pattern implies Community Cannabis is leaning into value-forward Pre-Roll formats as demand consolidates around higher-volume SKUs, while select Concentrates face share pressure.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

