

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Strane is stocked at 322 licensed dispensaries across Massachusetts, Maryland, and 3 other states, 102 of them in Massachusetts, with the deepest coverage in Boston, Worcester, Fall River, Lowell, and Brockton. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
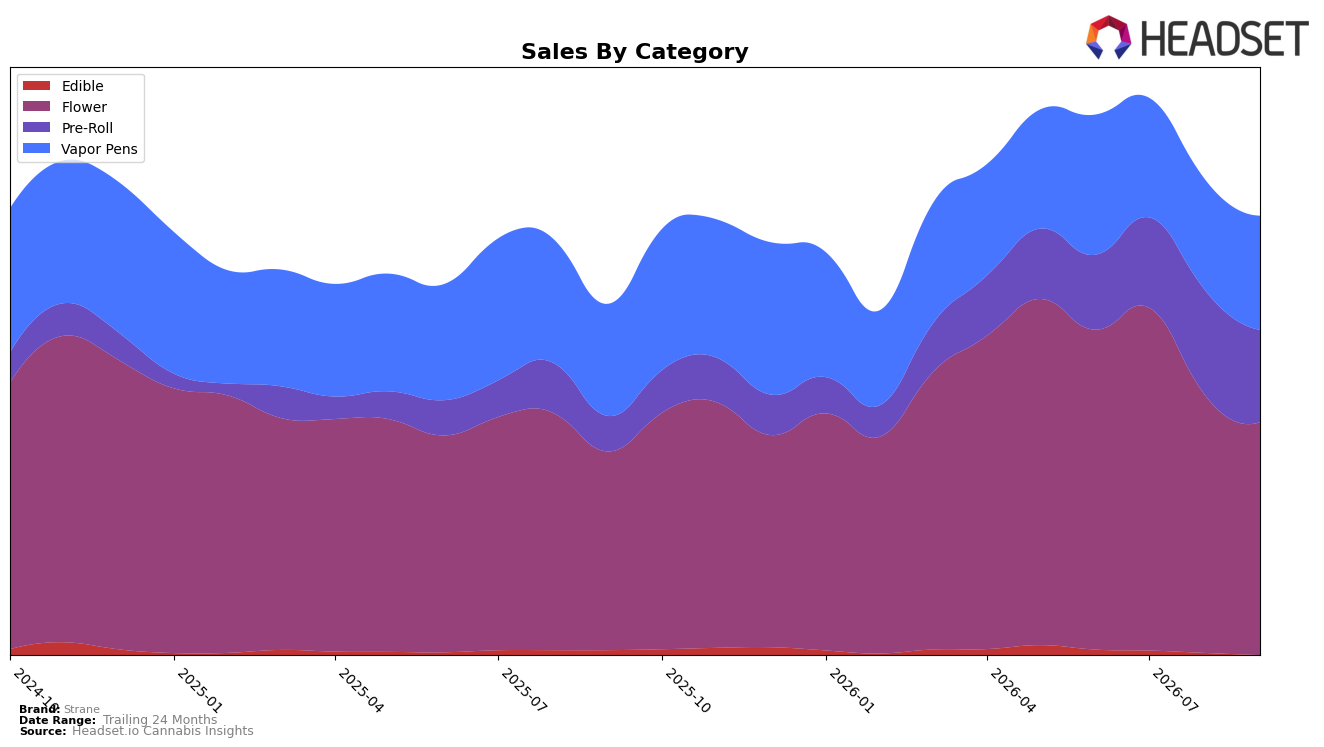
Strane’s category mix in September 2026 tilted toward Flower at 48.88% share with year-over-year growth of 15.74% but a month-over-month decline of 9.12%, while Pre-Roll held 21.57% share with a 104.78% year-over-year surge alongside a 10.30% month-over-month drop. Vapor Pens contributed 25.82% share with 1.52% year-over-year growth and a 2.67% month-over-month increase, and Edible accounted for 3.72% share with a 20.46% year-over-year decline and a 10.16% month-over-month decline. The mix implies a pivot toward inhalables where Pre-Roll expansion offsets Flower’s monthly softness, positioning Strane to trade volume across adjacent format preferences even as average price fell 13.32% year-over-year.
These shifts imply Strane is consolidating around combustibles while maintaining a stabilizing hedge in Vapor Pens, evidenced by Flower ranking 5th in Maryland and holding a 48.88% share as Pre-Roll’s 104.78% year-over-year growth broadens reach despite a 10.30% month-over-month pullback. With overall brand sales up 20.65% year-over-year against a 24‑month trend of -5.94%, and average price at $21.20 down 13.32% year-over-year, the current positioning favors price-accessible, high-velocity formats; the implication is that sustaining September 2026 momentum will depend on converting Pre-Roll trial into repeat while using Vapor Pens’ 2.67% month-over-month gain to buffer Flower’s 9.12% month-over-month contraction.
Competitive Landscape
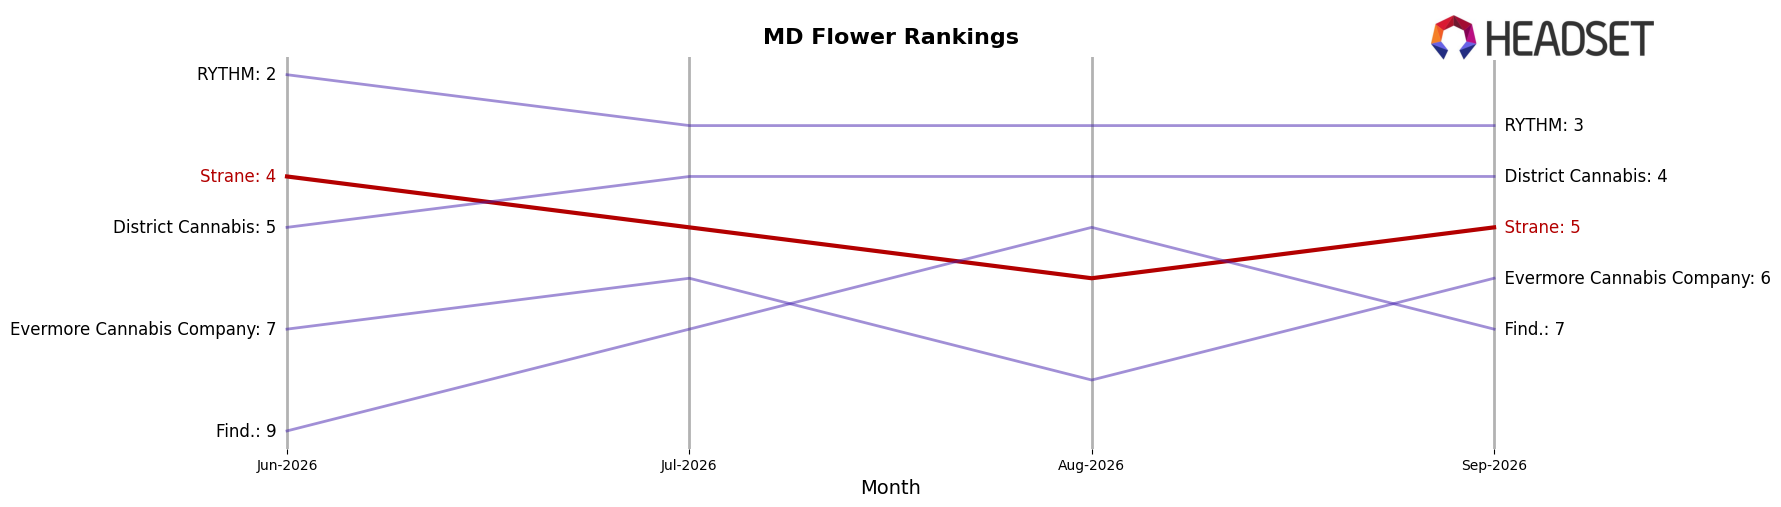
Strane sits at rank #5 in September 2026, an improvement of 5 positions from #10 in September 2025, but it slipped 1 spot from #4 in June 2026 when it hit its peak. Meanwhile, SunMed held #1 year-over-year and remains #1 in September 2026 with sales up 11.8%, and District Cannabis fell from #2 to #4 with a 29.4% YoY sales decline, indicating Strane’s climb is occurring amid mixed competitor momentum rather than across-the-board market lift; the pattern implies Strane’s rank trajectory is upward but vulnerable to near-term churn around the #4–#5 band.
Notable Products
Frosted Jungle (3.5g) posted the steepest decline in September 2026 at -48.8% MoM while sliding to rank 10, and Alien Mints (3.5g) fell -32.4% MoM at rank 7, signaling acute pressure in Flower even as Reserve - Super Gremlin (3.5g) rose +40.4% to rank 5. At the top of the chart, Alien Mints Pre-Roll 2-Pack (1g) held rank 1 with +3.9% MoM and Highaleah Pre-Roll 2-Pack (1g) sat at rank 2 with +6.2% MoM, while Banana Cream Pop Pre-Roll 2-Pack (1g) dipped -7.9% at rank 3, indicating stable share for small Pre-Roll formats despite mixed performance. Six of the top ten are Flower SKUs, yet only one Flower item logged growth, implying a category mix that is broad but currently inefficient versus Pre-Roll momentum. The pattern implies Strane should lean into winning Pre-Roll formats while triaging underperforming Flower strains, reallocating support toward proven SKUs and price tiers rather than spreading inventory across lagging varieties, with roughly $229,784 tied up in a Flower item outside the top five.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

