

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Curio Wellness is stocked at 342 licensed dispensaries across Missouri, Maryland, and 2 other states, 168 of them in Missouri, with the deepest coverage in St. Louis, Kansas City, Columbia, Springfield, and Joplin. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
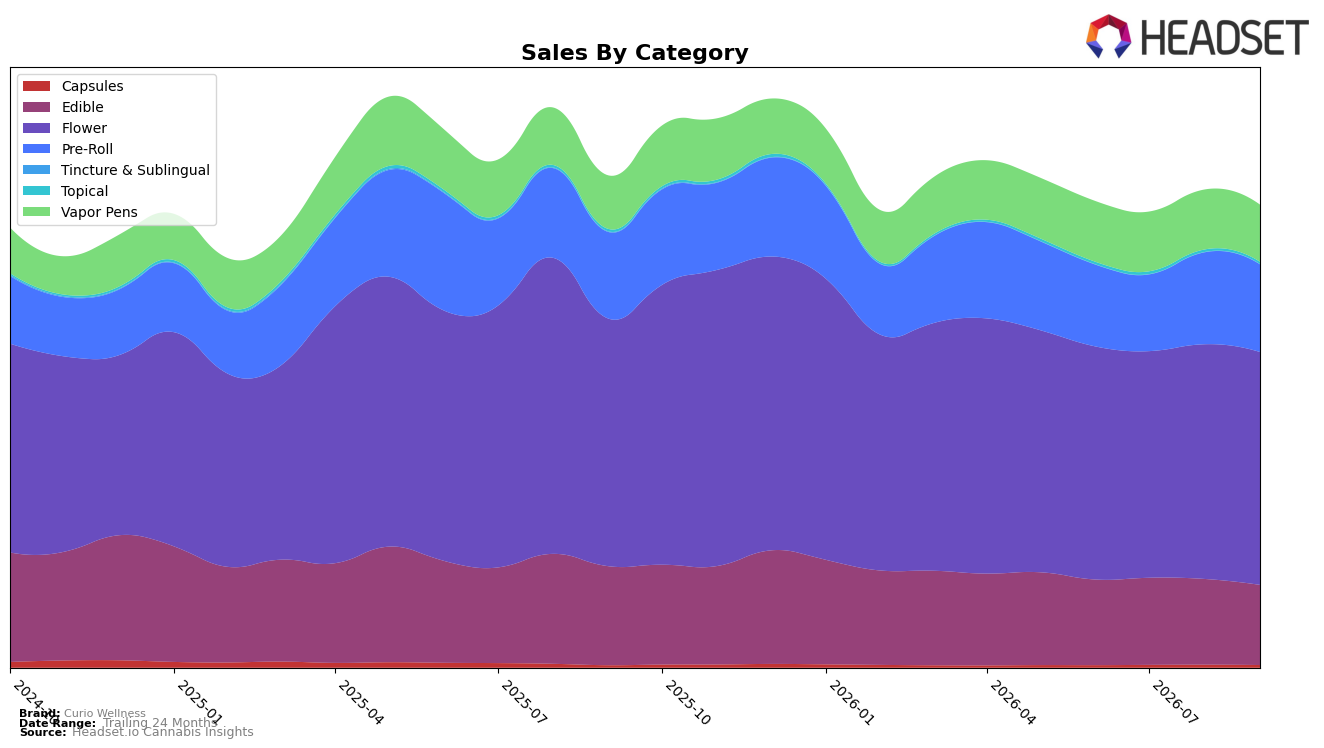
In September 2026, Curio Wellness concentrated 50.43% of sales in Flower with year-over-year change of -5.98% and month-over-month change of -0.79%, while Pre-Roll held 18.95% share with +1.27% YoY but -4.64% MoM. Edible accounted for 17.32% share with -19.13% YoY and -6.55% MoM, and Vapor Pens reached 12.33% share with +6.79% YoY yet -4.74% MoM. Niche formats were small: Capsules at 0.53% share with +7.82% YoY and -12.14% MoM, and Topical at 0.43% share with -7.70% YoY and -11.49% MoM. With average price down 0.78% YoY to $22.36 and overall brand sales down 5.97% YoY, the mix signals reliance on Flower and a defensive tilt toward value within inhalables.
Category shifts imply a positioning anchored in inhalables efficiency: Flower’s near-half share paired with an 11th rank in Maryland Flower points to depth rather than breadth, while Vapor Pens’ +6.79% YoY against a -4.74% MoM suggests episodic wins not yet sustained. The -19.13% YoY in Edible alongside Pre-Roll’s modest +1.27% YoY indicates the brand is ceding non-inhalable occasions while leaning on quick-turn formats, and the -12.14% MoM in Capsules reinforces limited traction in wellness-adjacent use cases. Net effect: Curio Wellness is competing on immediacy and price-sensitive inhalable options, a stance that can stabilize share in peak inhalable months but leaves exposure when edible-oriented demand rises.
Competitive Landscape
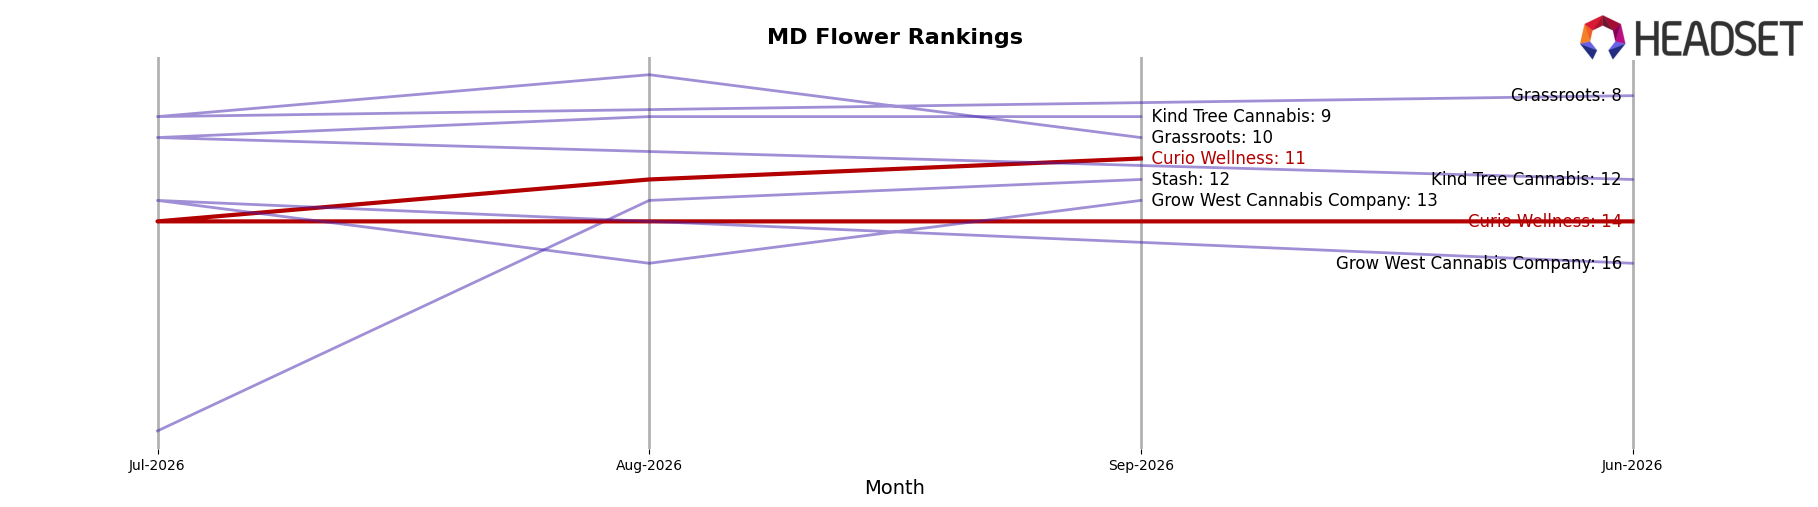
Curio Wellness sits at rank #11 in MD Flower in September 2026, down 3 positions year over year from #8, and up 3 positions from #14 three months ago; against a field where SunMed held #1 with a 0-position YoY change and 11.8% YoY sales growth while RYTHM is #3 with a 1-position YoY improvement but a -3.6% YoY sales decline. The category’s reshuffle also includes District Cannabis sliding from #2 to #4 with -29.4% YoY sales and Strane climbing from #10 to #5 with 46.0% YoY sales growth, while Curio Wellness remains below its April 2025 peak of #5, indicating mid-pack pressure and that recent quarter-on-quarter recovery has not reversed the longer-term rank erosion.
Notable Products
Pineapple OG Pre-Roll 2-Pack (1g) posted the steepest movement in September 2026 with a -39.5% month-over-month decline while sliding to rank 6, contrasting with Opals and Banonoze Pre-Roll 2-Pack (1g) up 21.6% at rank 5. At the top of the chart, Alien OG Pre-Roll 2-Pack (1g) held rank 1 despite a -3.4% dip, and Blissful Wizard Pre-Roll 2-Pack (1g) fell -18.4% at rank 3, indicating volatility clustered near the front of the lineup. Eight of the top ten SKUs are Pre-Rolls, concentrating share of shelf and signaling Curio Wellness is leaning into multi-pack inhalables as the brand’s commercial anchor.
Exclusive - Scotch & Soda (3.5g) stands out as the lone Flower SKU in the top ten at rank 9 with a -15.3% month-over-month change and the month’s highest dollar sales at $128,781, while Crumpets Pre-Roll 2-Pack (1g) softened -6.4% at rank 2. The combination of a -39.5% drop for Pineapple OG Pre-Roll 2-Pack (1g) and a 21.6% rise for Opals and Banonoze Pre-Roll 2-Pack (1g) shows substitution within the same format rather than category switching, implying Curio Wellness’s near-term growth depends on refreshing specific Pre-Roll strains more than shifting categories.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

