

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Fleur is stocked at 56 licensed dispensaries across Nevada and Arizona, 39 of them in Nevada, with the deepest coverage in Las Vegas, Henderson, Reno, Carson City, and Sparks. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
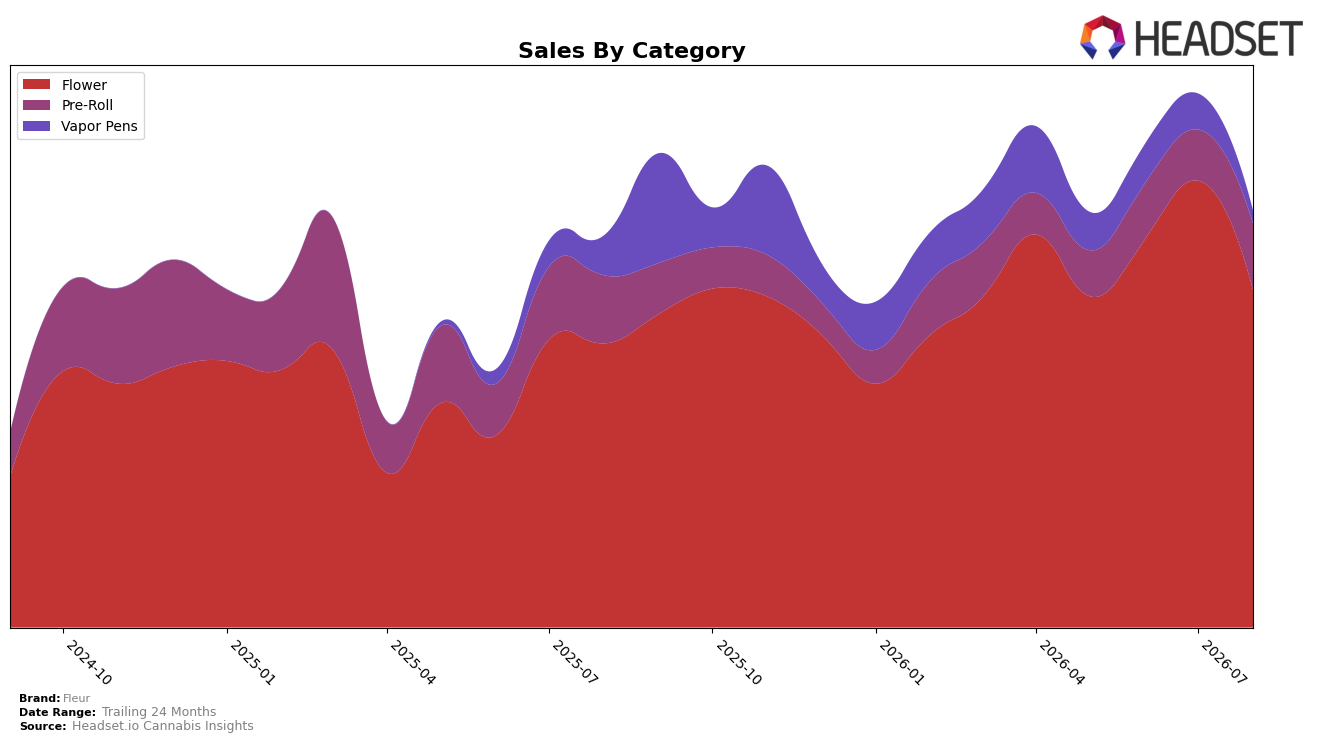
In August 2026, Fleur concentrated 80.99% of sales in Flower with 18.71% year-over-year growth but a 24.56% month-over-month decline, while Pre-Roll held 15.90% share with a 2.36% YoY dip yet a 30.26% MoM rise; Vapor Pens slipped to 3.10% share with a 67.41% YoY drop and a 63.90% MoM contraction. Average price rose 6.15% YoY to $22.79, and within Flower the average price stood at 31.53, as the brand’s Flower rank in Nevada sat at 33; the pattern implies a deliberate concentration in Flower that lifts annual momentum while near-term retrenchment and a Pre-Roll rebound rebalance mix risk.
With Flower at 80.99% share and ranked 33 in Nevada, the 24.56% MoM pullback alongside a 30.26% MoM gain in Pre-Roll indicates room to trade some dependency from a single category toward a two-pillar portfolio, especially as Flower’s 18.71% YoY rise contrasts with Vapor Pens’ 67.41% YoY decline. The 6.15% YoY average price increase, against Vapor Pens’ 63.90% MoM volume contraction and Pre-Roll’s 2.36% YoY dip, implies pricing power is presently anchored in Flower while positioning benefits from expanding Pre-Roll to cushion volatility and de-emphasizing Vapor Pens until its demand path stabilizes.
Competitive Landscape
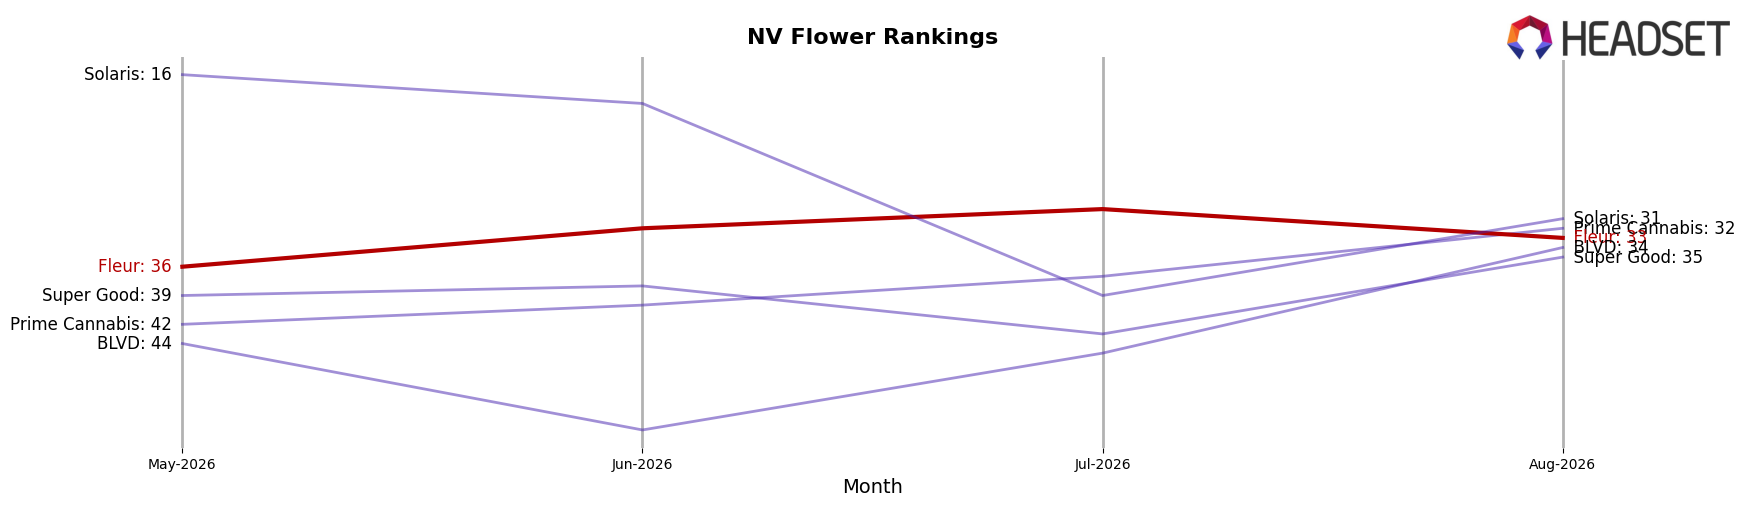
Fleur sits at rank #33 in NV Flower for August 2026, improving 9 positions year over year from #42 and tightening 3 spots since May–June levels near #36; however, it slipped 3 places from its peak at #30 in July 2026 to #33 in August 2026, a 10% relative drop in rank position month over month. Competitive pressure is acute at the top: STIIIZY advanced from #2 to #1 with a 50.5% year-over-year sales increase, while Neon Moon jumped from #13 to #3 alongside 159.5% year-over-year growth, indicating upward mobility that outpaces Fleur’s 9-rank annual climb. The pattern implies Fleur’s rank trajectory is improving on a yearly basis but lacks the acceleration needed to defend its July 2026 peak against faster-rising leaders, signaling a need to convert mid-year gains into sustained share capture.
Notable Products
Fleur’s August 2026 story is led by a contraction: Bushido OG (14g) fell 29.4% MoM to an estimated $26,984 while Bushido OG (3.5g) slid 27.9% at rank 1, and Grape Monster (3.5g) dropped 15.6% at rank 3; with four of the top ten being Flower SKUs, the concentration in Flower amplified downside risk as rank leadership did not prevent volume erosion. Offsetting signals came from Pre-Rolls, where Grape Monster Pre-Roll (1g) jumped 45.1% at rank 7 and Tiger Head Pre-Roll (1g) rose 36.1% at rank 10 as Bushido OG Pre-Roll (1g) gained 27.9% at rank 2, implying momentum is rotating from larger Flower formats toward ready-to-use Pre-Rolls and should steer mix and promo focus accordingly.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

