

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
From the Soil is stocked at 125 licensed dispensaries across Washington and Michigan, 115 of them in Washington, with the deepest coverage in Spokane, Seattle, Vancouver, Olympia, and Everett. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
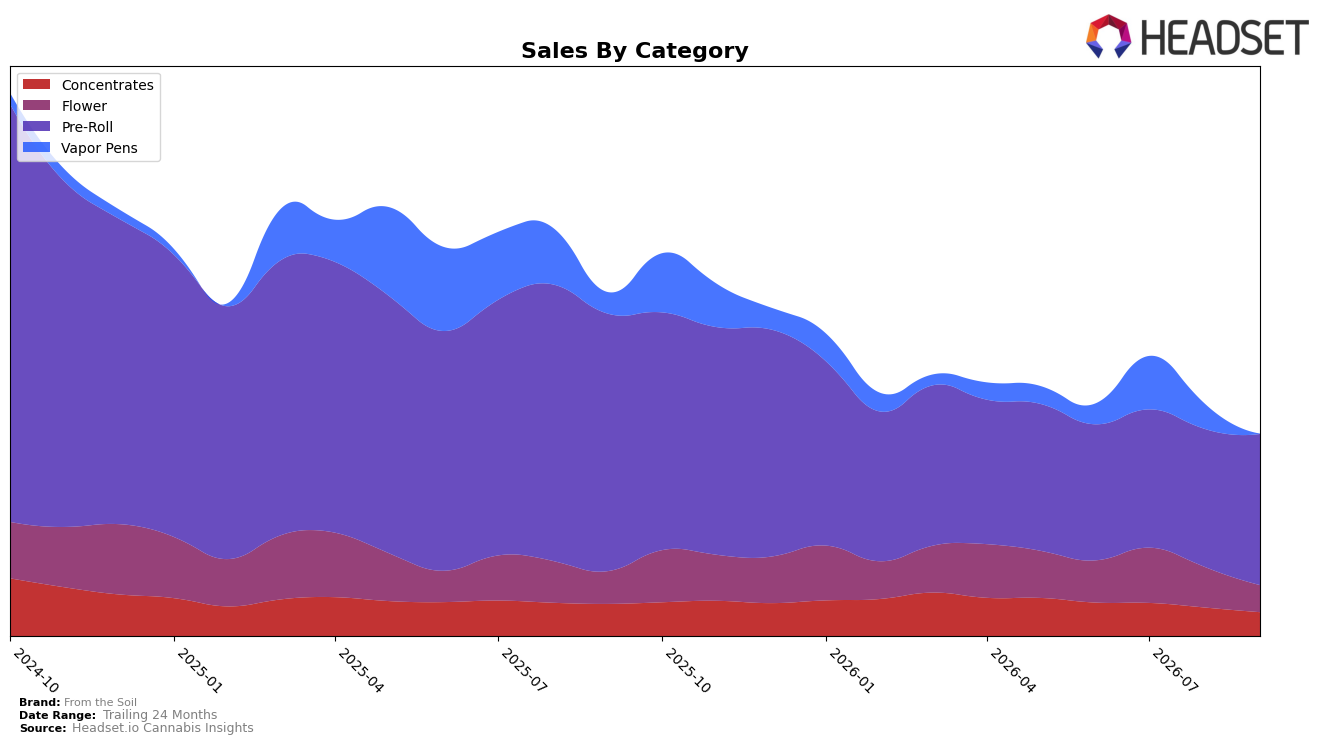
From the Soil concentrated 63.23% of September 2026 sales in Pre-Roll, up MoM within the mix as Pre-Roll grew 8.57% while Flower declined 24.30% and Concentrates fell 10.70%; Vapor Pens contracted 61.73% MoM with a 5.89% share, shifting the portfolio further toward value-priced inhalables. On a YoY basis, Pre-Roll sales were down 38.98% and Vapor Pens down 57.79%, compared with smaller declines in Flower at 12.01% and Concentrates at 17.48%; paired with an 8.48% YoY drop in average price and a 34.98% YoY brand sales decline, the mix now leans heavier into lower-price-per-unit formats, implying revenue is being maintained via unit velocity in Pre-Roll rather than through premium categories.
Pre-Roll’s expanded centrality raises execution stakes in Washington, where the brand sits at rank 18 in Pre-Roll, because further share recovery will likely depend on sustaining the 8.57% MoM gain despite category-wide pricing pressure and a 38.98% YoY sales contraction in that format. With Flower holding 16.04% share and a comparatively smaller 12.01% YoY decline versus Vapor Pens’ 57.79% YoY drop, the implied positioning skews toward affordable, high-throughput SKUs, suggesting the path to stabilizing the 34.98% YoY brand decline is to deepen promotional and assortment focus in Pre-Roll while selectively rebuilding Flower to offset volatility from Vapor Pens’ 61.73% MoM retrenchment.
Competitive Landscape
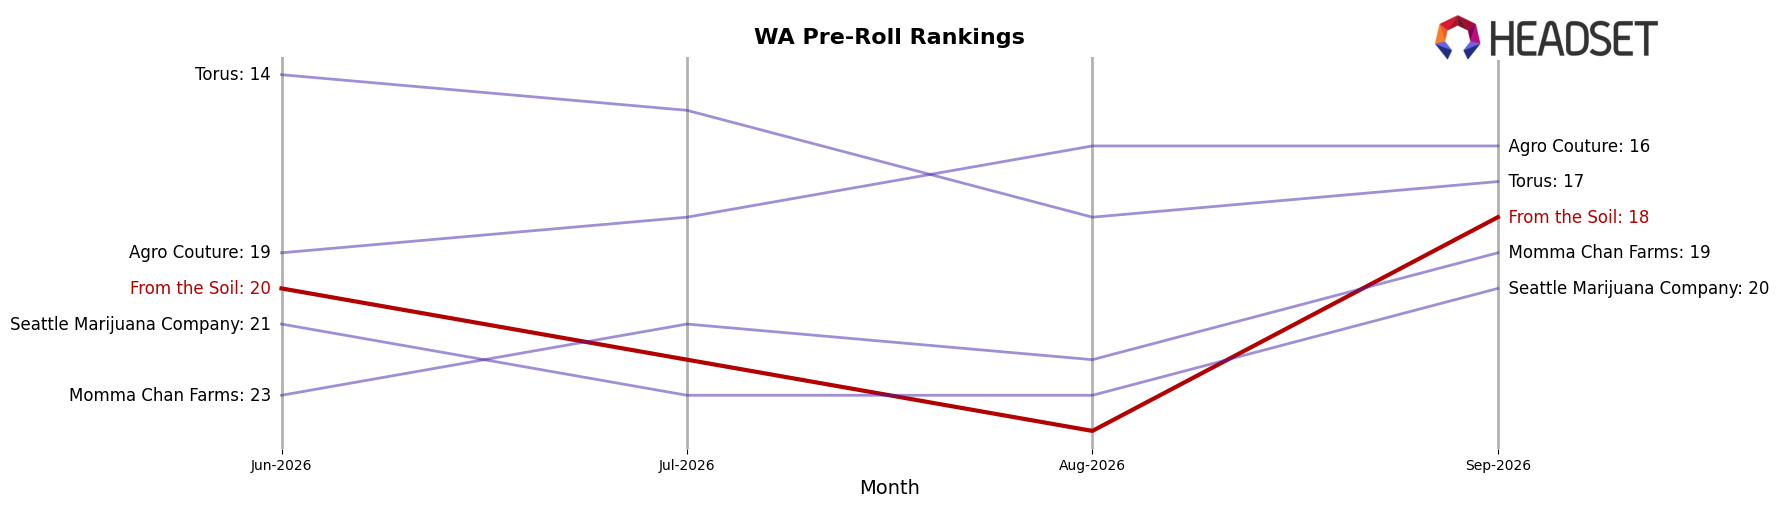
From the Soil sits at rank #18 in WA Pre-Roll for September 2026, down 6 positions year over year from #12, and up 2 spots since June 2026 when it was #20; by contrast, Ooowee held #1 with a 57.7% year-over-year sales increase while Lifted Cannabis Co moved from #5 to #4 alongside a 16.4% YoY gain. The brand’s current #18 stands far from its peak #6 in September 2024, and competitors like Phat Panda at #2 with 7.6% YoY growth reinforce that the category’s upper tier is consolidating, implying that From the Soil’s downward YoY rank shift and limited quarter-on-quarter recovery signal a need to address share erosion amid faster-rising leaders.
Notable Products
BangBerry Rush Pre-Roll 2-Pack (1.5g) posted the steepest movement in September 2026 at -28.4% month over month while sliding to rank 7, contrasting with the Indica RSO Syringe (1g) rising 18.8% to hold rank 1 and Lemon Amnesia Pre-Roll 2-Pack (1.5g) climbing 23.3% at rank 2. Within the top ten, eight SKUs are Pre-Rolls, and that concentration alongside a Concentrates leader suggests From the Soil is leaning on a Pre-Roll-heavy portfolio buffered by a single Concentrates anchor, pointing to a strategy where flavor rotation volatility in Pre-Rolls is offset by a steadier RSO Syringe revenue stream near $14.6k.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

