

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
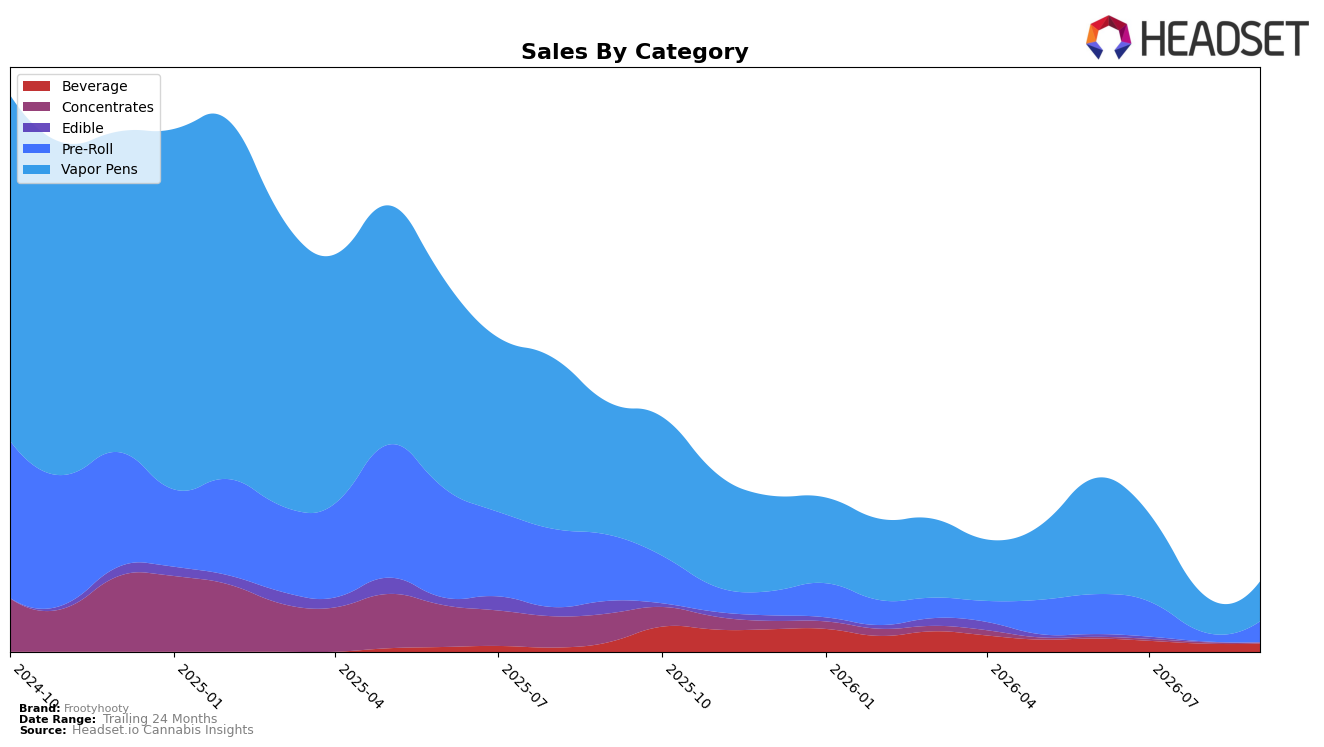
Frootyhooty’s category mix in September 2026 consolidated around Vapor Pens at 57.42% share with a month-over-month increase of 8.47% but a year-over-year decline of 70.06%, while Pre-Roll expanded to 29.67% share on a 136.12% month-over-month jump despite a 68.88% year-over-year drop. Beverage held 11.98% share with a modest 2.02% month-over-month gain against a 12.85% year-over-year decline, as Concentrates fell to 0.86% share with a 49.20% month-over-month decrease and a 97.92% year-over-year contraction; Edible compressed to 0.07% share with an 87.54% month-over-month decline and a 99.60% year-over-year fall. With Frootyhooty ranked 36 in Vapor Pens in Saskatchewan and an average price down 31.03% year over year to $16.54, the pattern points to a volume-chasing pivot into two lead formats while retreating from low-scale niches.
The surge in Pre-Roll mix alongside a stabilizing Beverage base implies a diversification hedge away from a single-format dependency, as Vapor Pens still command first-position share at 57.42% but face heavier year-over-year erosion of 70.06% than Beverage’s 12.85%. The split signals a value-oriented repositioning: Pre-Roll’s 136.12% month-over-month lift coupled with the 31.03% brand-level price reduction suggests price-led trial and trading-down dynamics, whereas the 49.20% month-over-month pullback in Concentrates and the 87.54% decline in Edible indicate pruning of low-velocity SKUs; collectively, the mix suggests Frootyhooty is concentrating on accessible formats to defend rank 36 in Vapor Pens while using Pre-Roll growth to keep total-share attrition in check.
Competitive Landscape
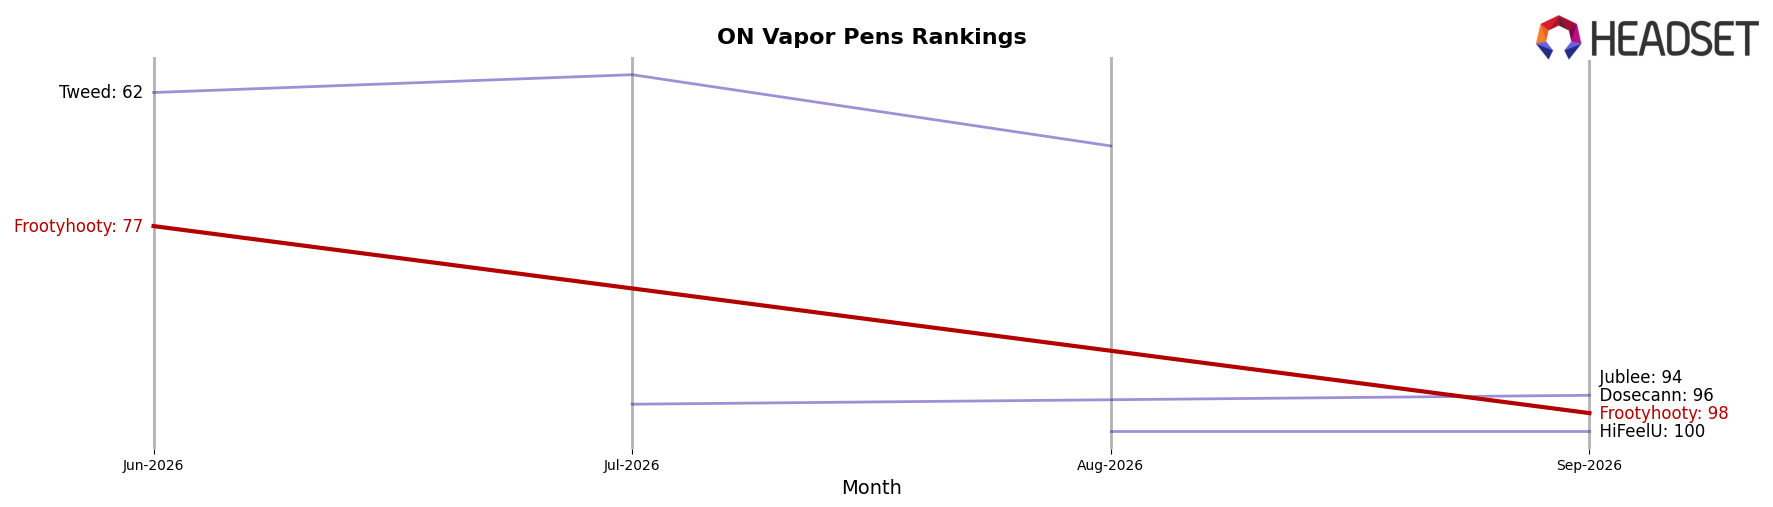
Frootyhooty sits at rank #98 in ON Vapor Pens in September 2026, down 34 positions year over year from #64 and 21 positions below its June 2026 rank of #77, while also sitting 55 places below its peak of #43 from September 2024; in contrast, Spinach rose from #4 to #1 with 172.5% YoY sales growth and Kolab climbed from #14 to #5 with 93.0% YoY growth, whereas General Admission slipped from #3 to #4 with an 12.0% YoY sales decline. With leaders consolidating in the top five and Frootyhooty drifting from #77 to #98 over three months and from #64 to #98 over twelve months, the pattern implies Frootyhooty is losing rank share to faster-advancing competitors and must reverse multi-period slippage to re-enter the top 50.
Notable Products
Plum & Done Diamond + Kief Coated Infused Pre-Roll 3-Pack (1.5g) posted the largest move in September 2026 with a 76.7% month-over-month gain, jumping to rank 3, while Poppin Peach Splash Zero Soda (10mg THC, 12oz, 355ml) in rank 1 rose a smaller 6.8% as Splash Zero Pink Lemonade Sparkling Beverage (10mg THC, 12oz, 355ml) at rank 2 slipped 4.6%. With three Pre-Roll SKUs landing inside the top 7 and Vapor Pens occupying ranks 5, 6, 8, 9, and 10, the assortment tilts toward inhalables even as beverages anchor the top two spots. The combination of a double-digit Pre-Roll surge and minor single-digit declines in key Vapor Pens at ranks 5 and 10 suggests mix is rotating toward higher-impulse infused formats rather than steady beverage add-ons. This pattern implies Frootyhooty is leaning into Pre-Roll momentum to capture quick-turn increments while beverages serve as traffic-driving leaders.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

