
Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Full Spec is stocked at 189 licensed dispensaries across Washington, with the deepest coverage in Seattle, Tacoma, Spokane, Vancouver, and Bellingham. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
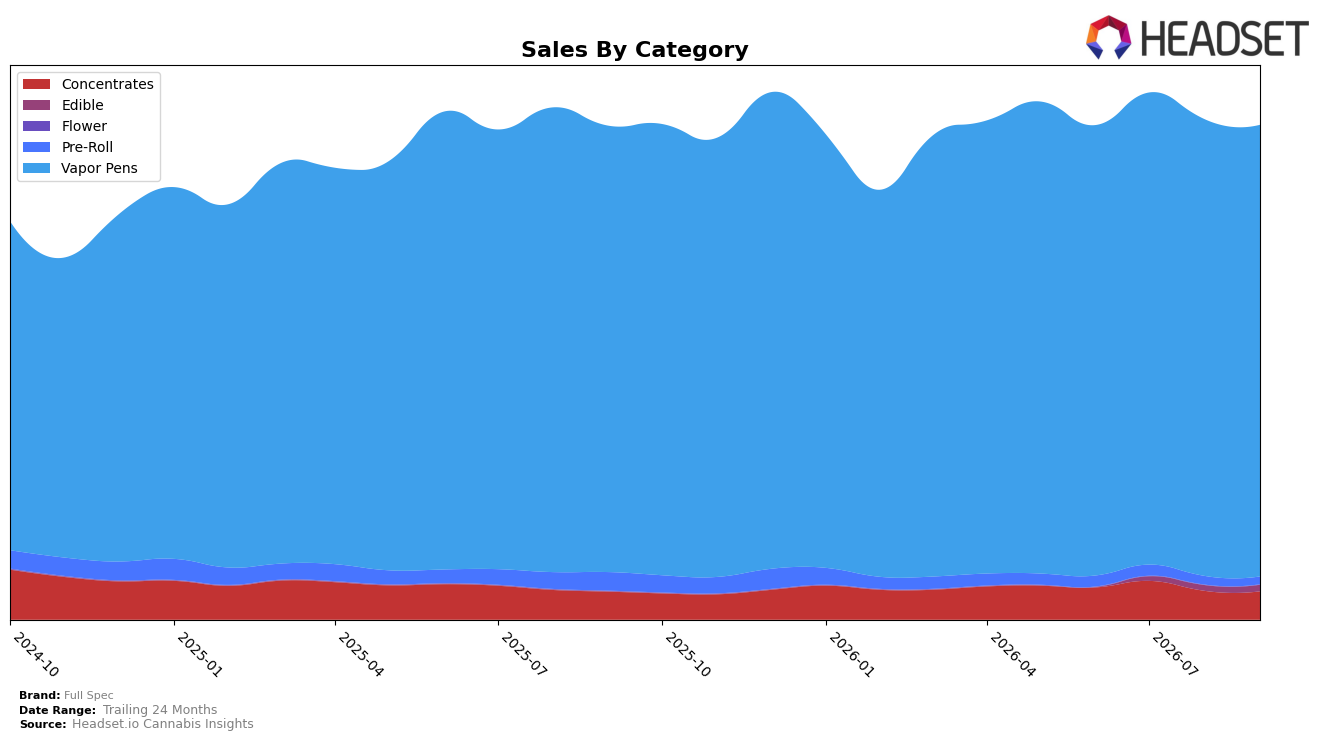
Full Spec concentrated 91.58% of September 2026 sales in Vapor Pens with a year-over-year gain of 116.98% but a month-over-month dip of 1.11%, while Concentrates held 5.68% share with 119.94% YoY and a 1.77% MoM decline; Pre-Roll slid to 1.50% share with a 59.34% YoY contraction and a 10.32% MoM drop, as Edible expanded to 1.24% share with 9,359.46% YoY and 15.29% MoM growth. Average price rose 4.01% YoY to $18.76 as Vapor Pens averaged $19.62 and Edible $10.97, and within Washington Vapor Pens the brand ranked 4; the pattern indicates a portfolio anchored in Vapor Pens with nascent diversification via Edible offsetting Pre-Roll attrition, while modest MoM pressure suggests near-term mix volatility around the dominant category.
The shift toward a two-tier mix — Vapor Pens scale with 91.58% share and rapid Edible entry up 15.29% MoM — implies pricing power concentrated where rank 4 confers visibility, while double-digit Pre-Roll decline at 10.32% MoM and 59.34% YoY reduces exposure to a weak lane. With brand sales up 17.17% YoY and 45.71% over 24 months, but core Vapor Pens down 1.11% MoM, the positioning hinges on defending pen rank while using Edible momentum to diversify revenue risk; this mix suggests prioritizing cross-category activation that leverages the $19.62 pen price point without diluting the improving $18.76 average.
Competitive Landscape
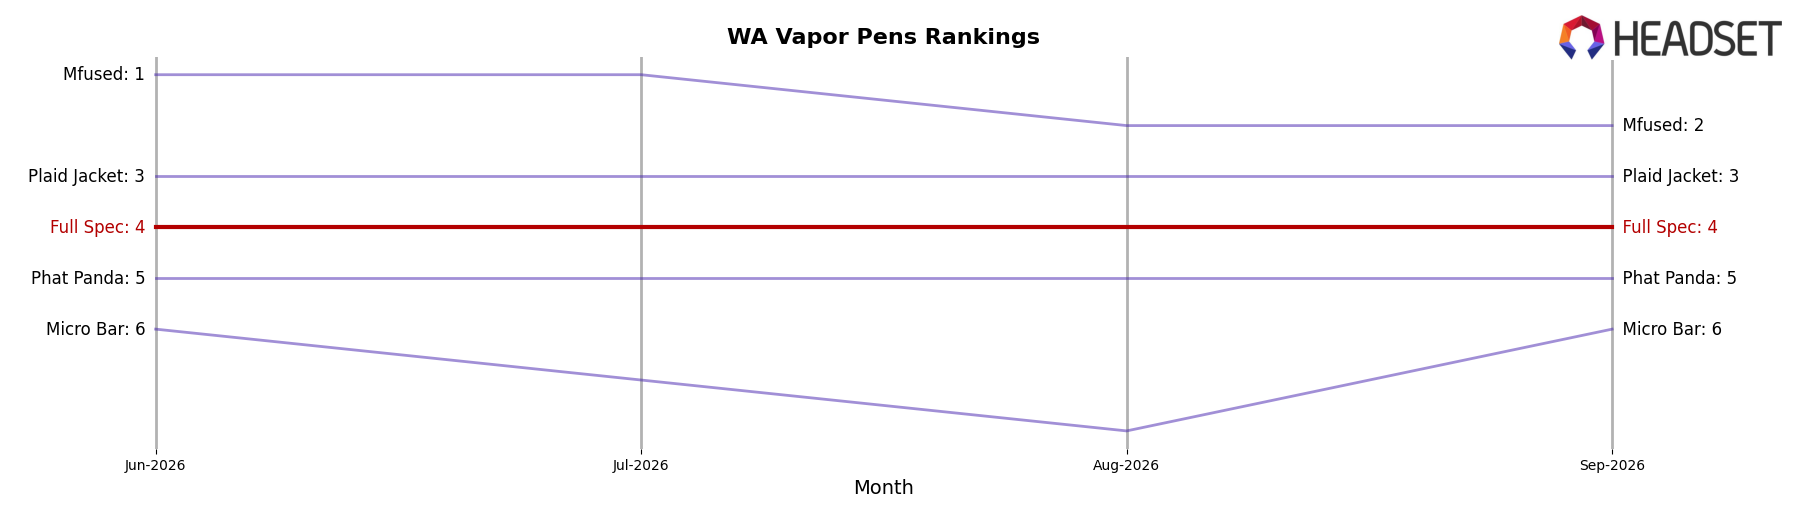
Full Spec is ranked #4 in Washington Vapor Pens in September 2026, unchanged from #4 year over year, with stability also evident versus June 2026 at #4 and a prior peak of #3 in May 2026; meanwhile, Crystal Clear holds #1 after rising from #3 year over year while growing sales 26.4%, and Mfused sits at #2 after dropping from #1 with sales down 30.9%. Plaid Jacket advanced from #6 to #3 alongside 23.3% sales growth, whereas Phat Panda fell from #2 to #5 with a 25.1% decline, indicating pressure just above and below #4; the pattern implies Full Spec’s flat rank is defensive rather than momentum-driven, and holding #4 will require either reclaiming May 2026’s #3 position or absorbing share from a weakening #5.
Notable Products
Elite - Dirty Girl Live Resin Cartridge (1g) posted the steepest month-over-month decline at -40.9% while sliding to rank 7, and Elite - Night Nurse Live Resin Cartridge (1g) fell -11.8% at rank 6, pointing to pressure on legacy Elite variants within the top 10. By contrast, Elite - 509 Fuego Live Resin Cartridge (1g) dipped a milder -7.6% at rank 4 and Kiwi Sorbet Live Resin Cartridge (1g) was down -9.0% at rank 5, indicating mid-pack softness that has not yet dislodged their positions. With Vapor Pens occupying all top-10 slots and three Elite-labeled SKUs posting negative MoM percentages between -7.6% and -40.9%, the mix implies a pivot toward newer flavor-led entries as the tactical path to sustain September 2026 rankings and margin depth.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

