

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Garden First is stocked at 140 licensed dispensaries across Oregon, with the deepest coverage in Portland, Bend, Eugene, Medford, and Salem. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
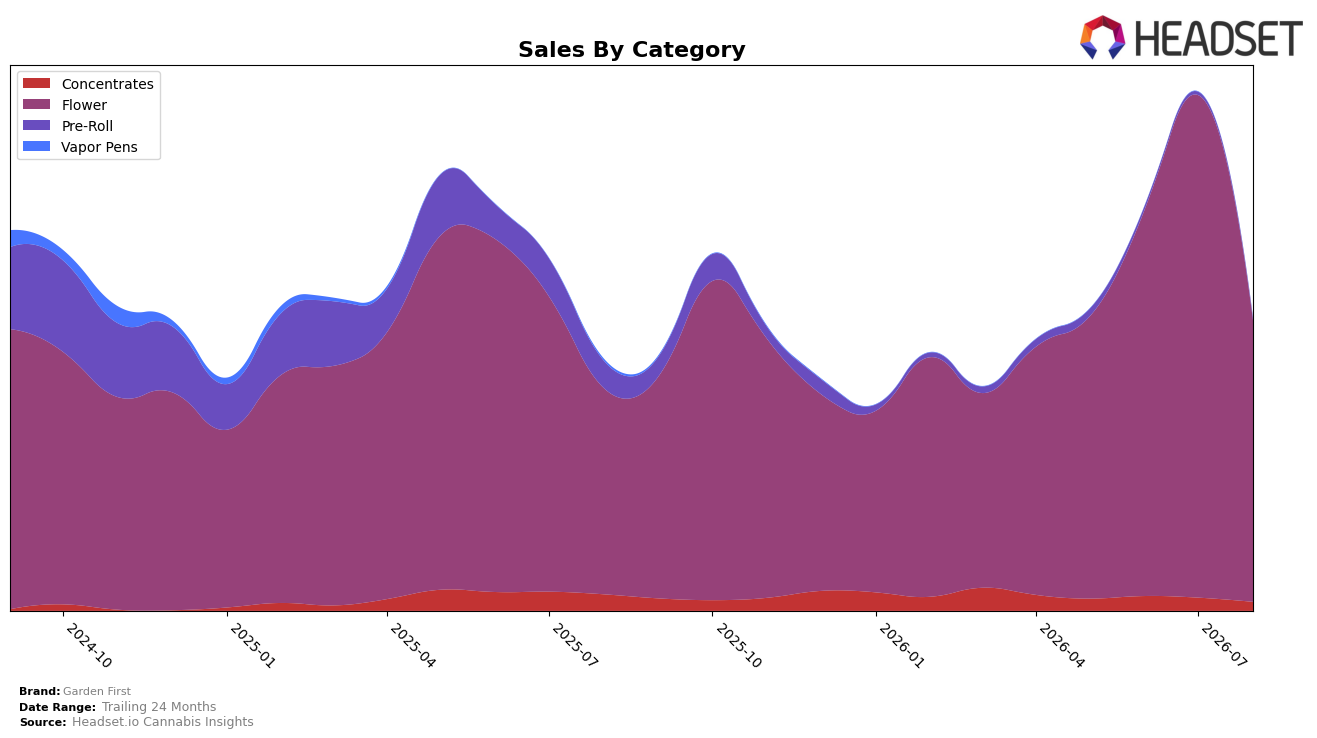
In August 2026, Garden First concentrated 96.25% of sales in Flower, where year-over-year sales rose 36.36% even as month-over-month sales fell 44.17%, while Concentrates held 2.94% share with a 46.85% YoY decline and a 33.09% MoM drop; Pre-Roll slipped to 0.81% share with a 91.18% YoY drop and a 19.12% MoM decline. The brand’s average price fell 17.23% YoY to $16.38 as Flower’s average price sat at $16.63, implying mix-driven volume gain alongside price compression; in Oregon Flower, the brand ranked 22, so the combination of higher YoY sales growth and steep MoM pullback points to a demand base that is expanding annually but sensitive to short-cycle pricing and inventory swings.
The category shifts suggest Garden First is leaning into a single-category scale strategy: a 96.25% Flower mix with 36.36% YoY growth and a concurrent 44.17% MoM contraction implies exposure to harvest timing and promotion cadence, while collapsing shares in Concentrates at 2.94% with a 46.85% YoY decline and Pre-Roll at 0.81% with a 91.18% YoY decline reduce cross-category insulation. With the brand ranked 22 in Oregon Flower and a 17.23% YoY price decrease, the positioning skews toward value-driven Flower volume rather than portfolio breadth, implying that stabilizing month-to-month volatility will require either tighter price architecture within Flower or selective re-entry into adjacent formats to smooth demand.
Competitive Landscape
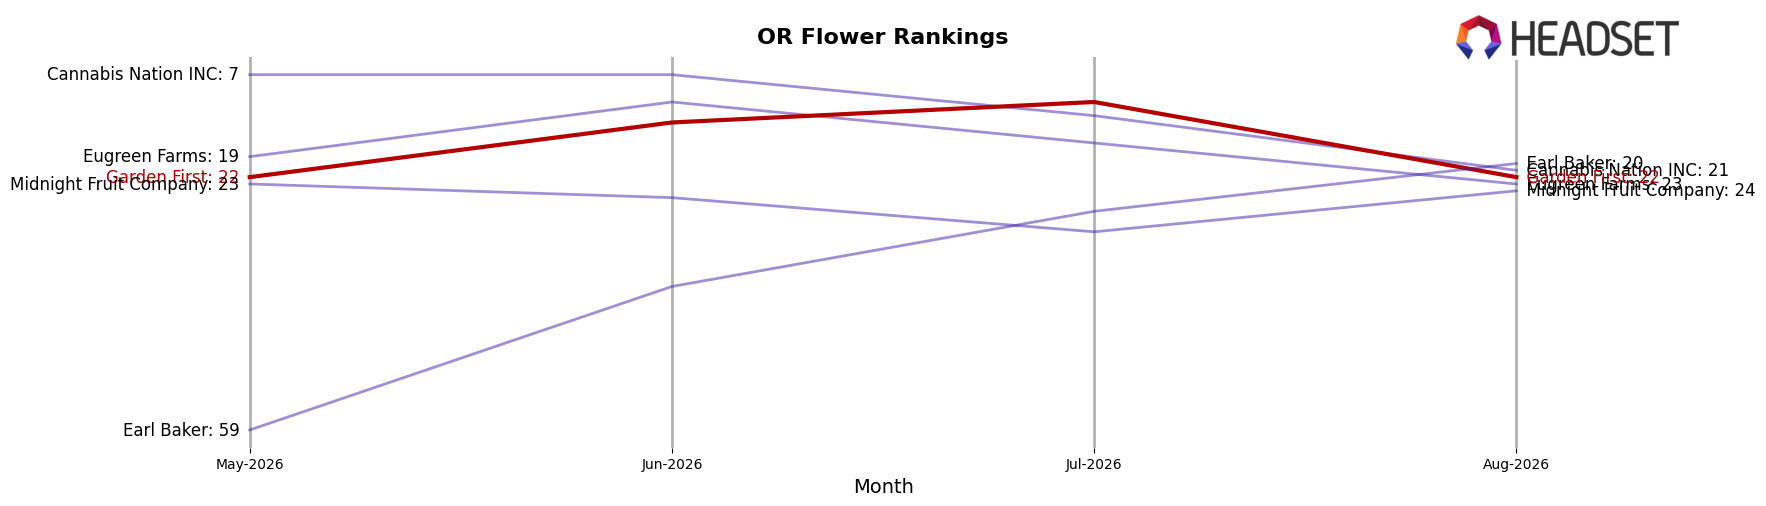
Garden First sits at rank 22 in OR Flower in August 2026, improving 12 spots YoY from rank 34, and holding flat versus May–July with a 0-position change from May 2026 to August 2026; however, its peak at rank 11 in July 2026 contrasts with the current 11-place slide month-over-month, while Grown Rogue climbed from rank 3 to rank 1 and Oregrown advanced from rank 23 to rank 3 with a 182% YoY sales lift. Meanwhile, PRUF Cultivar / PRŪF Cultivar slipped from rank 1 to rank 2 alongside a 17% YoY sales decline, and Panda Farms surged from rank 99 to rank 4 with a 1,060% YoY sales increase, indicating that Garden First’s mid-pack stability at rank 22 amid rapid upward moves by multiple rivals points to a need for velocity gains to avoid further share compression.
Notable Products
Classics Sunset Sherb x Gelato (1g) posted the steepest movement in August 2026 with a -55.7% month-over-month drop while sliding to rank 5, and Golden Goat (Bulk) also fell -55.1% while holding at rank 10. In contrast, Golden Goat (1g) rose +17.0% MoM to rank 1 with $48,413 in sales, while Iced Mocha (1g) declined -31.1% at rank 8. With all top-10 SKUs concentrated in Flower and two bulk formats declining more than -55% as the leading 1g climbed, the pattern implies a pivot toward smaller-pack velocity over bulk volume for Garden First.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

