

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Gelato is stocked at 780 licensed dispensaries across Michigan, California, and Arizona, 411 of them in Michigan, with the deepest coverage in Detroit, New Buffalo, Monroe, Grand Rapids, and Kalamazoo. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
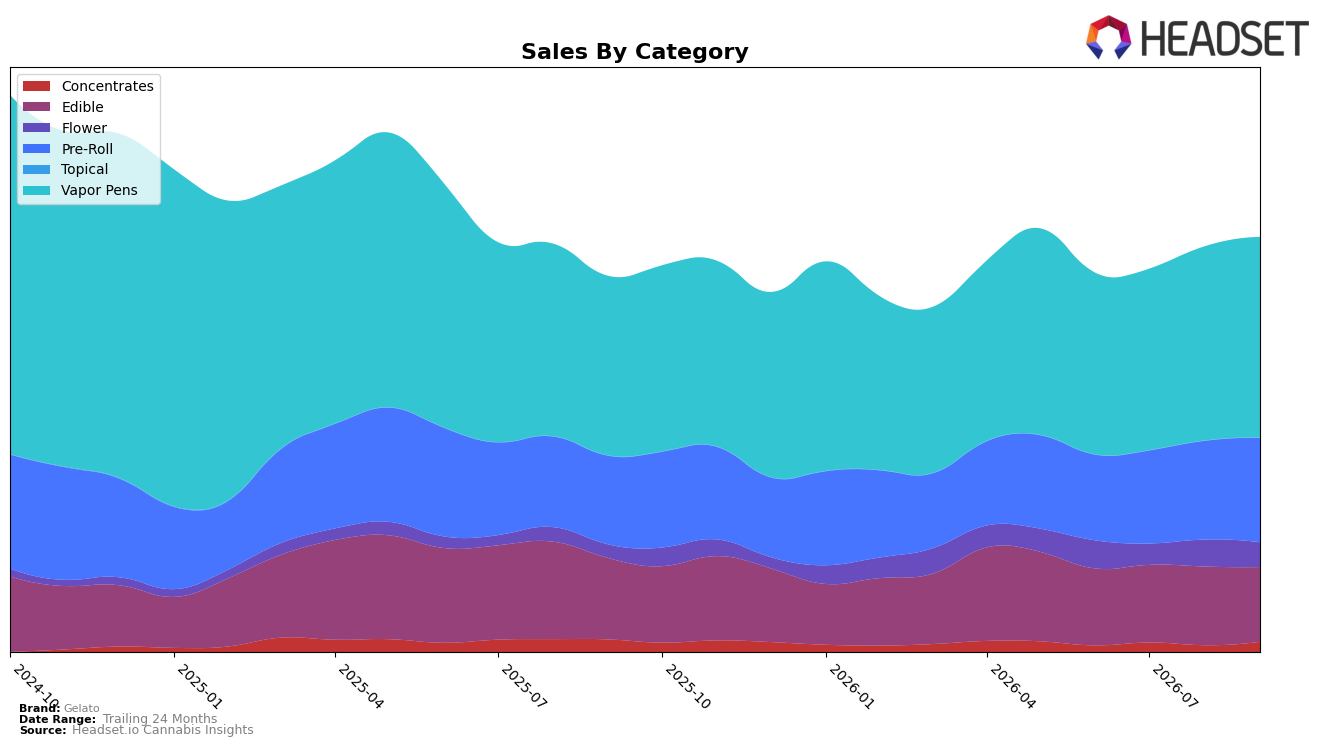
In September 2026, Gelato’s mix tilted toward Vapor Pens at 48.43% share with 11.76% YoY growth and 3.31% MoM, while Pre-Roll held 25.17% share with 17.88% YoY and 5.75% MoM, signaling the brand’s volume is concentrating in two inhalable formats even as average price fell 17.47% YoY. Edible contracted to 17.97% share with -8.31% YoY and -5.12% MoM, and Flower held 5.92% share with 83.78% YoY but -7.83% MoM, as Concentrates remained smaller at 2.51% share with -18.23% YoY but a 49.73% MoM rebound. The pattern implies Gelato is relying on Vapor Pens and Pre-Roll to offset price compression and 24‑month sales decline of -23.85%, using near-term momentum in Concentrates to diversify without disrupting the core.
Given a Vapor Pens rank of 21 in California and a 48.43% category share within the brand, Gelato’s positioning hinges on defending pen visibility while reallocating marginal effort toward Pre-Roll’s 17.88% YoY and Concentrates’ 49.73% MoM to capture incremental trial. The contrasting Edible decline of -8.31% YoY alongside Flower’s 83.78% YoY but -7.83% MoM suggests shifting consumer elasticity: value-driven inhalables can carry volume while Edibles require SKU pruning, implying Gelato should concentrate assortment around sub-$15 pen and sub-$6 pre-roll price bands to convert September 2026 traffic into sustained rank gains.
Competitive Landscape
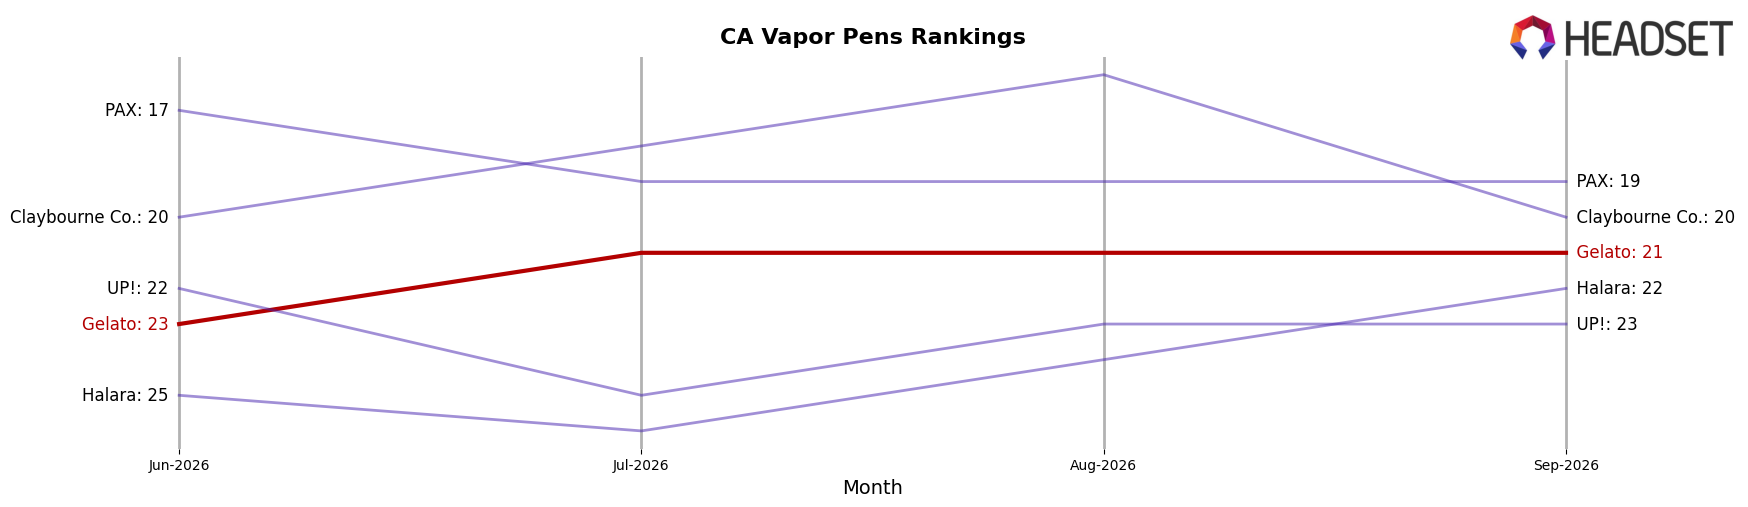
Gelato sits at rank #21 in CA Vapor Pens in September 2026, unchanged from #21 year over year, while moving up 2 positions from #23 over the last three months; this stability contrasts with Jetty Extracts advancing from #4 to #3 alongside a 45.2% YoY sales lift and Plug Play slipping from #3 to #4 with a 13.5% YoY decline, indicating the competitive middle is fluid even as Gelato holds steady. Despite a historical peak of #12 in October 2024, Gelato’s flat YoY rank at #21 and modest 3-month improvement from #23 to #21, against STIIIZY remaining #1 year over year despite a 16.7% YoY sales contraction and Raw Garden holding #2 with a 0.6% YoY gain, implies Gelato’s current trajectory is one of share defense rather than recovery toward prior peak positioning.
Notable Products
Skywalker OG Pre-Roll (1g) delivered the standout move in September 2026 with a +120.8% month-over-month surge to the number 1 rank, while Pineapple Punch Pre-Roll (1g) slid -11.6% at rank 10. Citrus Punch Pre-Roll (1g) also declined -14.7% at rank 6, contrasting with Northern Lights Pre-Roll (1g) up +20.0% at rank 8. With ten of the top ten SKUs coming from the Pre-Roll category and one leader clearing $52,113, the mix implies Gelato is consolidating around Pre-Rolls where spikes at the top offset mid-tier softness.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

