

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Is this your brand?
See your full sales and distribution data: where you sell, how you're priced, and how you rank against the brands next to you on the shelf.
See your brand's dataCarry this brand in your store?
Headset Retailer is free. Connect your POS and see what's selling and what's sitting.
Sign up freeWhere to Buy
Glass Meadows is stocked at 102 licensed dispensaries across New Jersey, with the deepest coverage in Jersey City, Atlantic City, Bloomfield, Newark, and Somerset. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
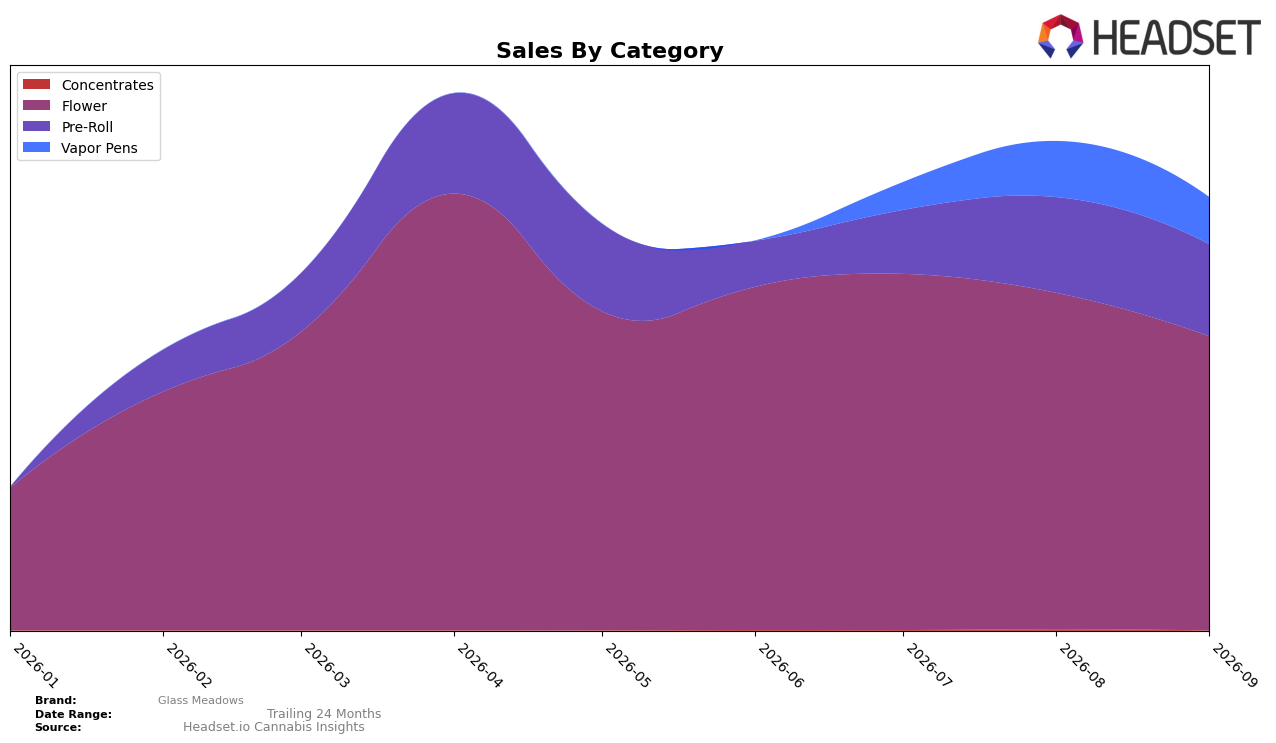
Glass Meadows concentrated 67.97% of September 2026 sales in Flower with a month-over-month decline of 12.60%, while Pre-Roll held 21.21% with a 3.80% MoM drop and Vapor Pens accounted for 10.82% with a 16.15% MoM contraction. Within its core state of New Jersey Flower, the brand sat at rank 31, indicating mid-pack visibility as Flower’s share outweighed Pre-Roll by 46.76 percentage points and Vapor Pens by 57.15 percentage points. This composition and the sharper MoM pullback in Vapor Pens versus Pre-Roll imply that September 2026 category demand leaned toward Flower for Glass Meadows, but reliance on a single category amplified volatility risk.
The 12.60% MoM decline in Flower alongside a rank position of 31 in New Jersey suggests headroom to stabilize core assortment, while the 3.80% MoM dip in Pre-Roll versus a 16.15% MoM slide in Vapor Pens indicates Pre-Roll as the nearer-term buffer for mix resilience. With Flower eclipsing Pre-Roll by 46.76 percentage points and Vapor Pens by 57.15 percentage points, the brand’s positioning tilts toward a high-share anchor that can support scale, but the steeper Vapor Pens contraction signals that expansion levers likely sit in tightening price-pack architecture in Pre-Roll and selective Flower SKU rationalization rather than heavier investment in Vapor Pens in October 2026.
Competitive Landscape
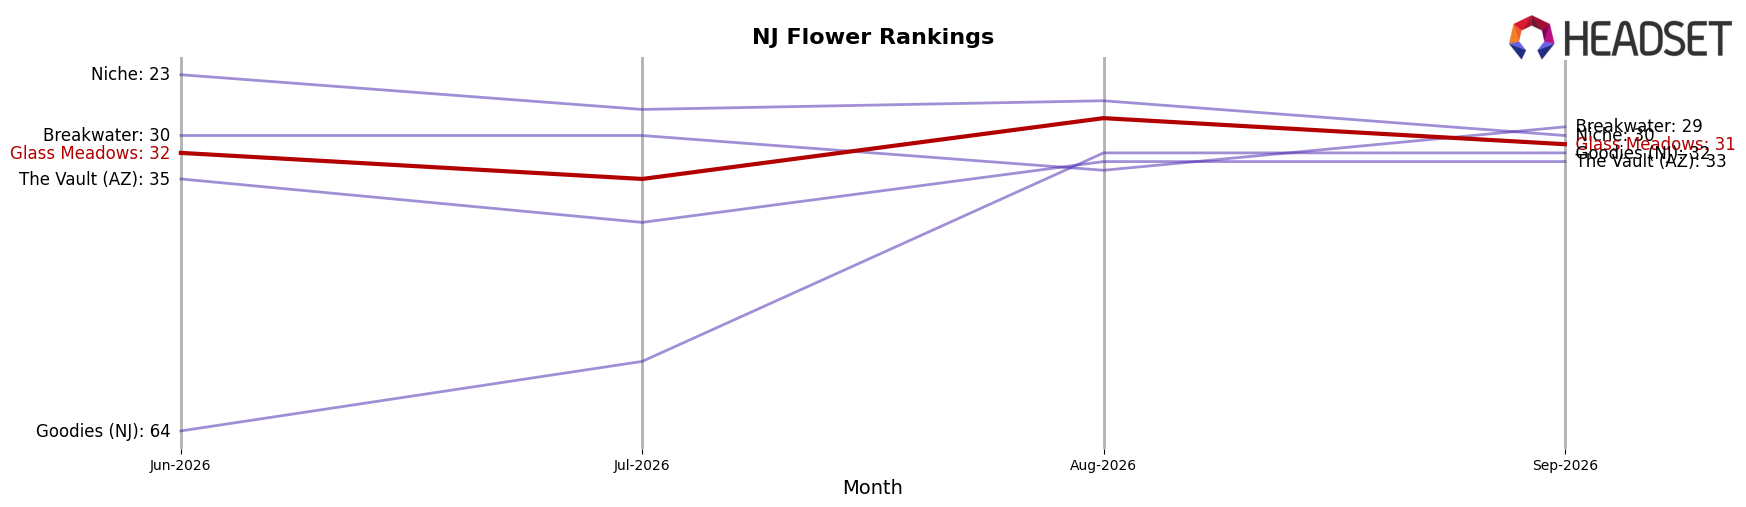
Glass Meadows sits at rank #31 in New Jersey Flower with no year-over-year rank available, edging up 1 spot from #32 in June 2026 to #31 in September 2026 while having peaked at #28 in August 2026; by contrast, Find. climbed to #1 with a +6 YoY rank change and 111.6% YoY sales growth, and Ozone holds #2 despite a 2-rank YoY gain paired with -2.8% YoY sales, indicating that Glass Meadows’ brief August peak followed by a step back to #31 points to a ceiling near the high-20s unless it converts short-lived spikes into sustained share gains.
Notable Products
YeaNo Pre-Roll (1g) posted the steepest decline at -39.1% MoM while holding rank 5, and Papaya Crush Pre-Roll (1g) fell -32.9% MoM at rank 3, indicating demand compression within the core format. With Hawaiian Fruitcake Pre-Roll (1g) at rank 1 and Maple Nectar Pre-Roll (1g) at rank 2, six of the top ten are Pre-Roll SKUs, yet Mint Granita Pre-Roll (1g) slid -34.9% MoM at rank 10, pointing to a tiered mix where only a few leaders anchor share while mid-pack products retrench. Super Lemon Haze Smalls (7g) entered the top tier at rank 8 with $25,421 alongside Blue Zushi Smalls (3.5g) at rank 9, suggesting Flower is encroaching on Pre-Roll placements as Pre-Roll decline rates outpace stability at the top. The pattern implies Glass Meadows is leaning into a barbell product mix where flagship Pre-Rolls carry rank leadership while Flower Smalls capture incremental basket share during September 2026.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

