
Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
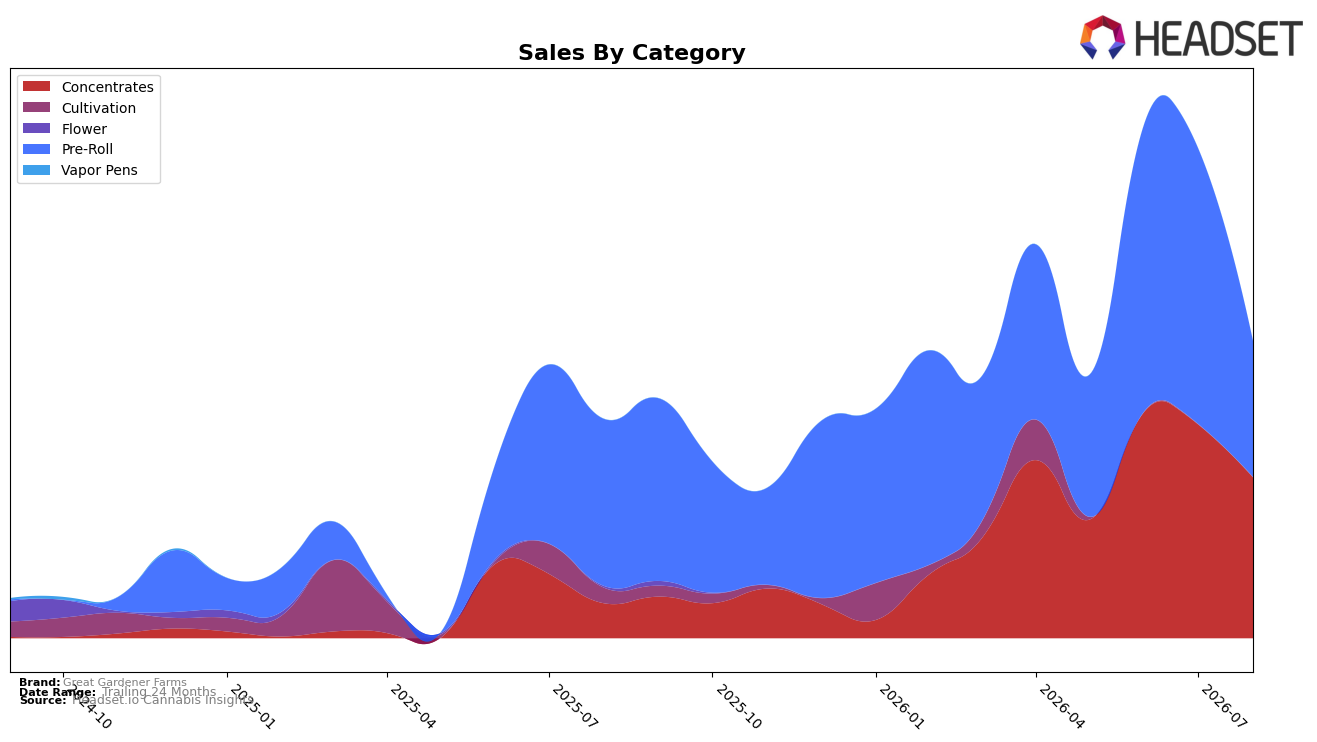
In August 2026, Great Gardener Farms derived 54.24% of sales from Concentrates and 45.76% from Pre-Roll, with Concentrates up 361.93% year over year but down 24.90% month over month, while Pre-Roll fell 18.81% year over year and 50.87% month over month. The brand’s average price rose 37.51% year over year to $21.99, alongside a higher Concentrates average price of 40.85, and the brand ranked 26 in Concentrates within British Columbia; this pattern implies a pivot toward higher-priced Concentrates that buoy annual growth even as short-term declines compress volume in Pre-Roll.
The mix shift toward Concentrates at 54.24% share and a 361.93% year-over-year surge, combined with a 24.90% month-over-month pullback and a simultaneous 50.87% Pre-Roll month-over-month drop, positions Great Gardener Farms as more exposure-weighted to a premium potency segment with higher price points. Given the 37.51% brand-wide price increase and a category rank of 26 in British Columbia Concentrates, the pattern implies a strategy that trades near-term unit elasticity for margin and category depth, with August 2026 volatility suggesting the need to stabilize monthly sell-through while consolidating gains in Concentrates.
Competitive Landscape
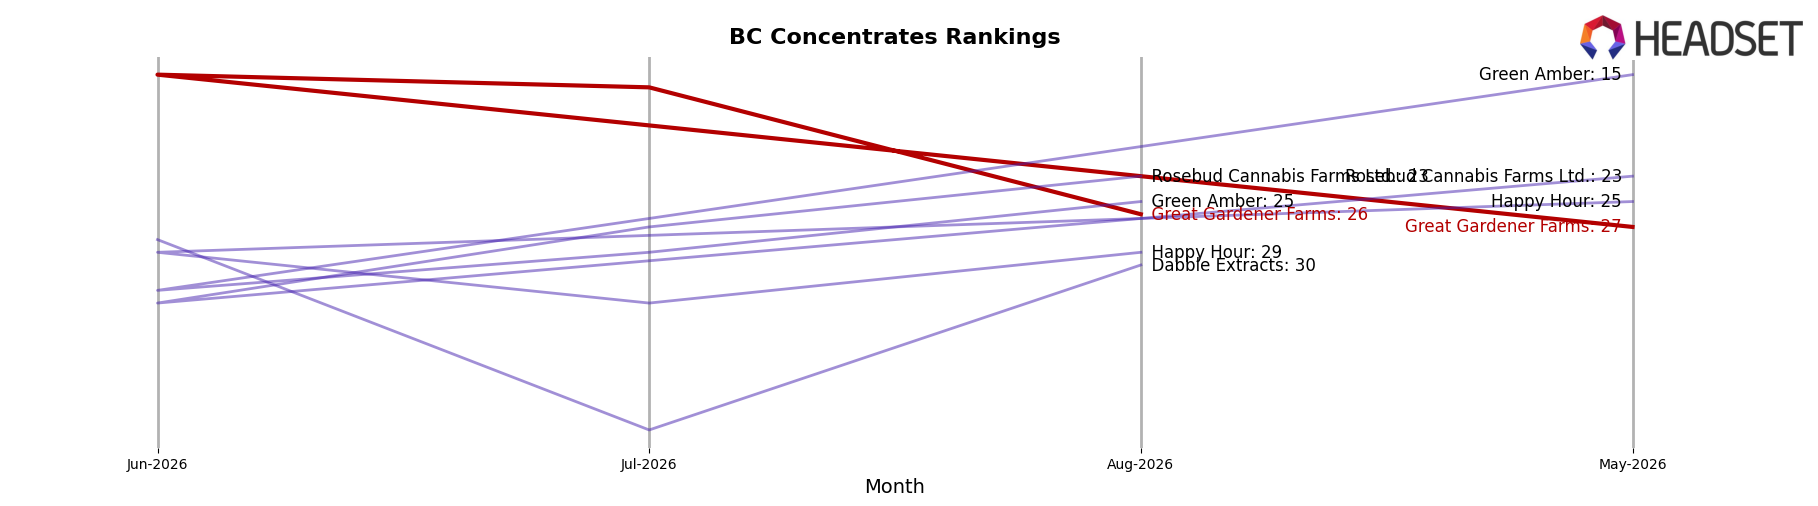
Great Gardener Farms sits at rank 26 in August 2026, improving 17 positions from rank 43 year over year, and edging 1 place from rank 27 in May 2026 to 26 by August 2026; its June 2026 peak at rank 15 marks an 11-place slide from that high, indicating mid-year retrenchment. In contrast, Dab Bods climbed from rank 4 to rank 1 alongside 127.2% year-over-year sales growth, while BoxHot moved from rank 7 to rank 2 with 161.9% growth, and Endgame fell from rank 1 to rank 4 with a 50.3% year-over-year sales decline; these rank shifts frame Great Gardener Farms’ 17-position annual gain as momentum off a lower base rather than consolidation near the top. The pattern implies Great Gardener Farms is stabilizing in the mid-20s after a June 2026 spike, and without acceleration relative to leaders that advanced 2–6 ranks, the current trajectory points to incremental share recovery rather than a sustained return to the top 15.
Notable Products
Fruit Joy Live Rosin Infused Pre-Roll (1g) posted the steepest decline in August 2026, falling 67.9% MoM to rank 3, while Barbara Bud Live Rosin Infused Pre-Roll (1g) also slid 33.0% MoM despite holding rank 1. Barbara Bud Cold Cure Live Rosin (1g) was the outlier with a 14.9% MoM increase at rank 2, creating a split performance where infused pre-rolls contracted as concentrates stabilized. With two of the top four in Concentrates and two in Pre-Roll, the mix indicates a tilt toward solventless concentrates as the more durable volume base, implying Great Gardener Farms is leaning into Barbara Bud-led rosin formats while culling underperforming infused pre-roll depth.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

