

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Himalaya is stocked at 126 licensed dispensaries across California, with the deepest coverage in Sacramento, Santa Rosa, Fresno, Modesto, and Oakland. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
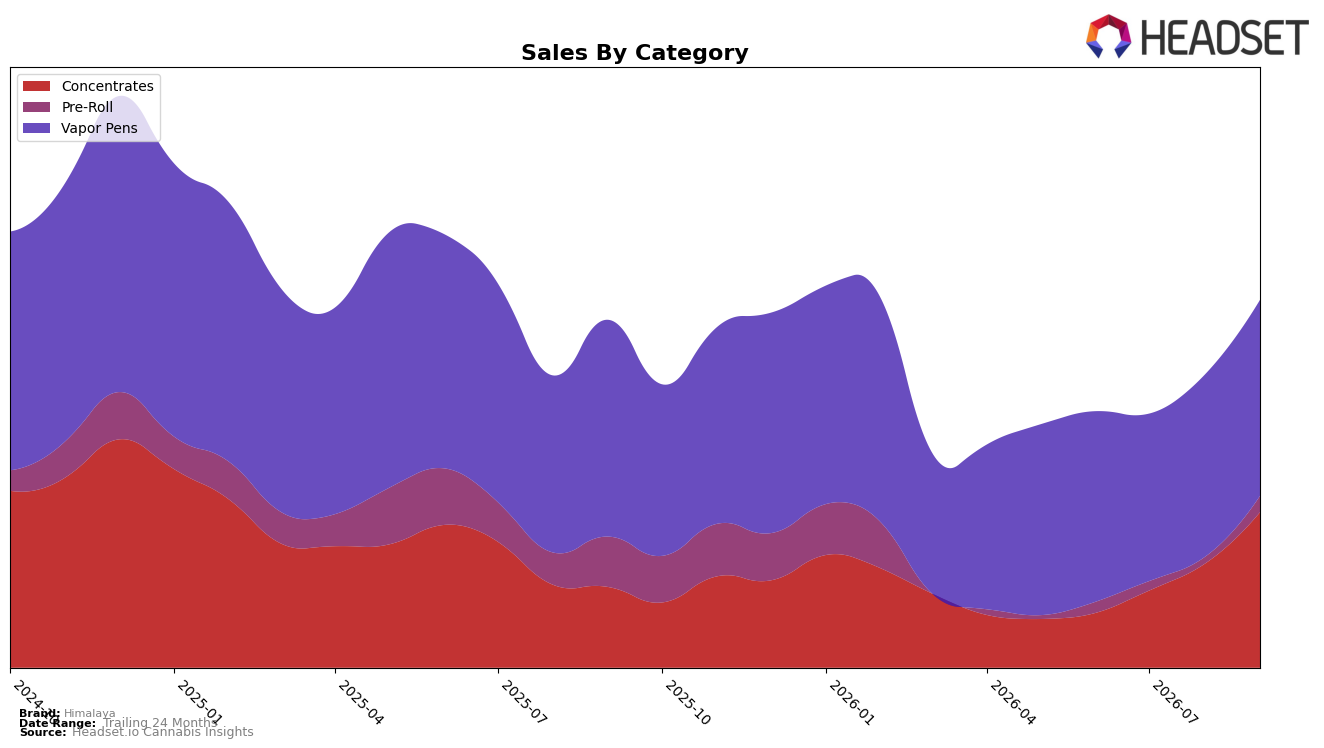
In September 2026, Himalaya’s mix tilted toward Vapor Pens at 48.13% share despite a -8.01% year-over-year decline, while month-over-month sales in that category rose 6.11% and the average price increased 2.01% YoY to $15.07 at the brand level. Concentrates expanded to 39.97% share with 60.57% YoY growth and a 35.21% MoM jump, contrasting with Pre-Roll at 11.90% share where sales fell -36.59% YoY but climbed 19.25% MoM; together, this split helped overall brand sales grow 4.18% YoY even as the 24‑month trend sits at -9.68%. The pattern implies Himalaya is leaning into Concentrates momentum to offset Vapor Pens’ YoY drag while using MoM gains in both Vapor Pens and Pre-Roll to stabilize near‑term mix.
With Vapor Pens still the largest slice but ranking 40th in California for that category, the -8.01% YoY pressure suggests Himalaya’s competitive position in its lead segment is lagging, whereas the 60.57% YoY and 35.21% MoM surges in Concentrates point to a scalable growth vector that can rebalance reliance on a mid‑pack rank. Given Pre-Roll’s -36.59% YoY but 19.25% MoM lift, the brand’s September 2026 configuration implies a positioning pivot: prioritize Concentrates to capture share gains while using targeted Vapor Pen improvements to defend a 48.13% anchor and selectively test Pre-Roll where quick MoM traction can be converted into sustained contribution.
Competitive Landscape
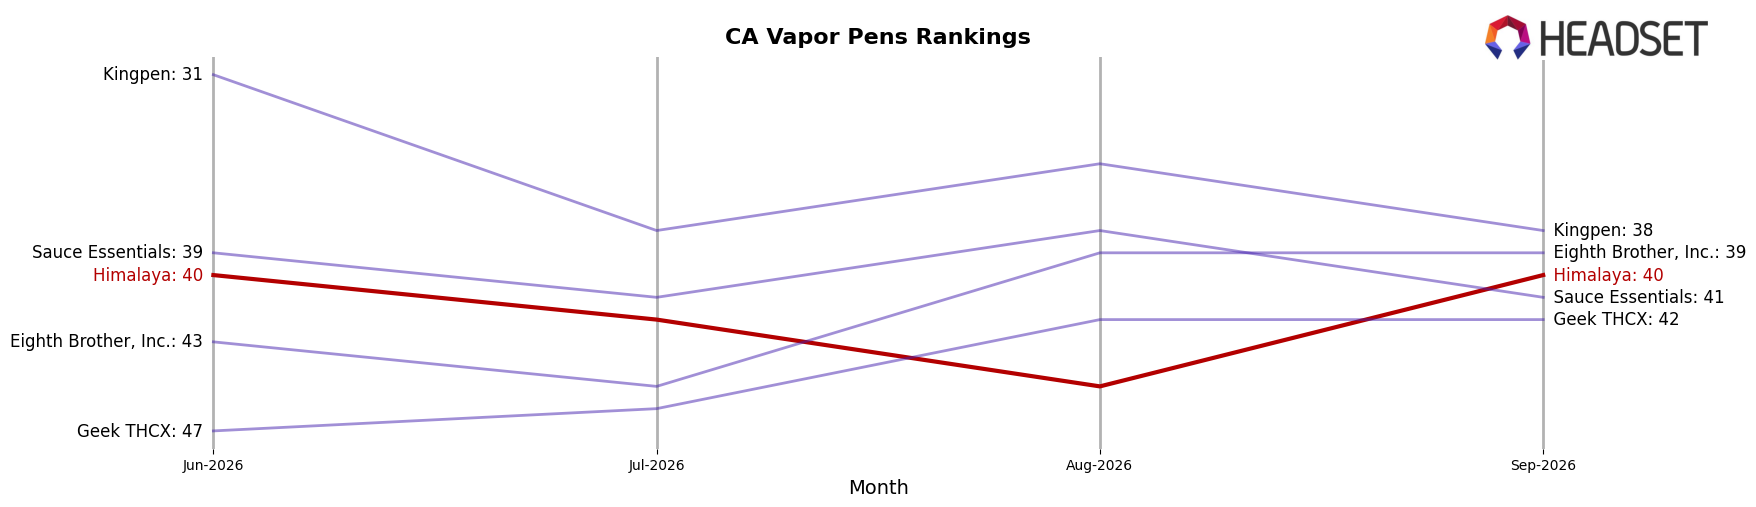
Himalaya sits at rank #40 in California Vapor Pens in September 2026, down 2 positions from #38 year over year, and flat versus June 2026 at #40, while its historical peak of #30 in December 2024 underscores a 10-rank slide from peak to present; in contrast, Jetty Extracts improved position from #4 to #3 year over year alongside a 45.21% sales lift, whereas Plug Play slipped from #3 to #4 with a 13.53% sales decline, indicating competitive movement near the top even as Himalaya remains stationary in the lower tiers—this trajectory implies Himalaya’s share is at risk of gradual erosion unless it reclaims momentum toward the prior #30 peak.
Notable Products
24K Goat Live Resin Terp Sugar (1g) set the tone in September 2026 with a 78.5% month-over-month surge and a rise to rank 1, while Galactic Runtz Infused Pre-Roll (1g) climbed to rank 10 on a 42.3% gain. Orange Malt Live Resin Terp Sauce (1g) held rank 2 with a 16.3% increase, and Cherry Gushers Live Resin (1g) slipped 3.1% yet stayed within the top 10 at rank 8. With six of the top ten coming from Concentrates and Pre-Rolls occupying four slots, the mix points to Himalaya consolidating around inhalable formats where rapid-mover SKUs can capture incremental share.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

