
Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Hyman is stocked at 409 licensed dispensaries across Michigan, with the deepest coverage in New Buffalo, Detroit, Monroe, Grand Rapids, and Flint. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
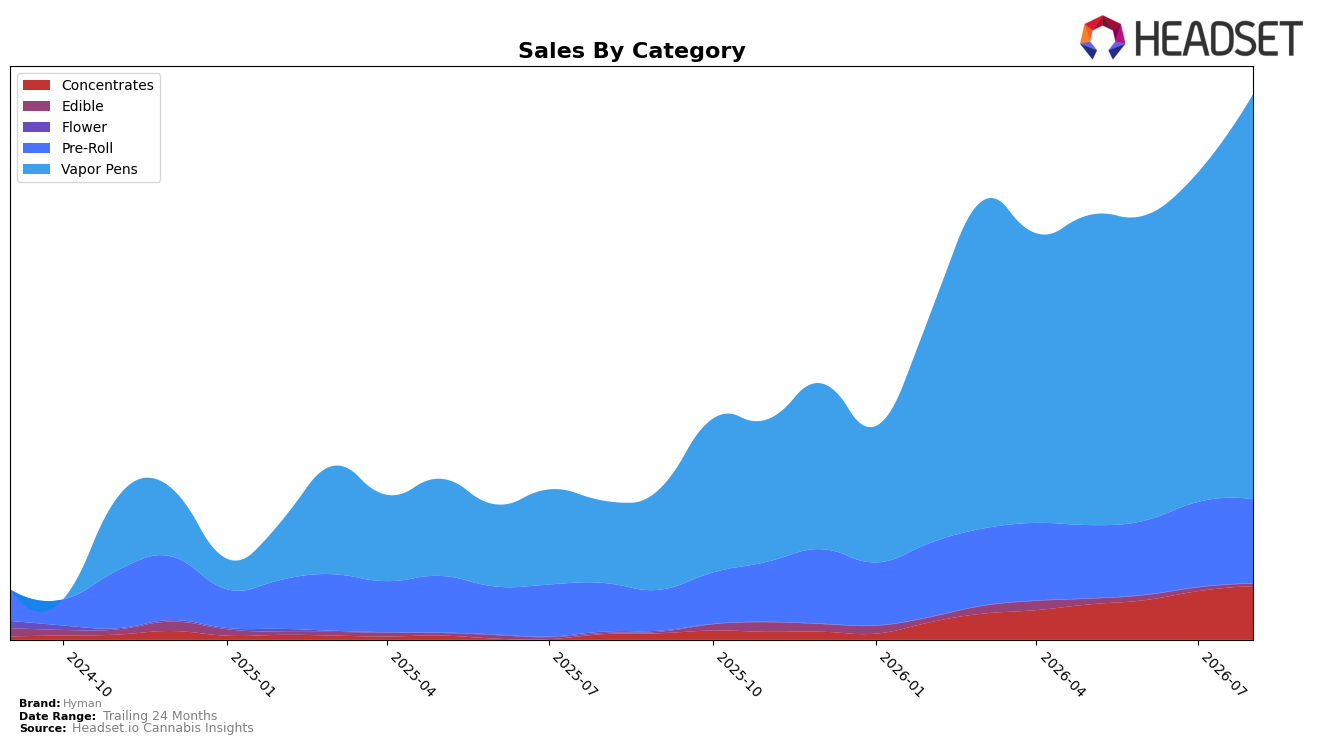
In August 2026, Hyman concentrated 74.48% of sales in Vapor Pens with year-over-year growth of 395.29% and month-over-month growth of 23.05%, while Pre-Roll held 15.34% share with 73.38% YoY but slipped -1.44% MoM. Concentrates expanded to 9.79% share with 892.35% YoY and 10.25% MoM growth, whereas Edible remained a niche at 0.38% share with 193.08% YoY yet contracted -37.78% MoM. With average price down -21.85% YoY to $18.88 and Vapor Pens ranked 9 in Michigan, the pattern implies deliberate volume-led expansion in inhalables, using price to accelerate penetration while de-emphasizing low-scale Edible.
The mix shift toward Vapor Pens (+23.05% MoM share momentum within category growth) and the surge in Concentrates (+892.35% YoY on 9.79% share) position Hyman as an inhalables-first brand, trading breadth for depth; this can raise repeat rates in core formats but heightens exposure to cartridge and extract pricing cycles. The simultaneous Pre-Roll softness (-1.44% MoM despite 73.38% YoY) and the steep Edible pullback (-37.78% MoM with only 0.38% share) indicate resource allocation away from peripheral categories; combined with a -21.85% YoY price drop and a rank of 9 in Michigan Vapor Pens, the implication is a rank-chasing strategy anchored in competitive pricing to consolidate share in one priority category while using Concentrates as a secondary growth wedge.
Competitive Landscape
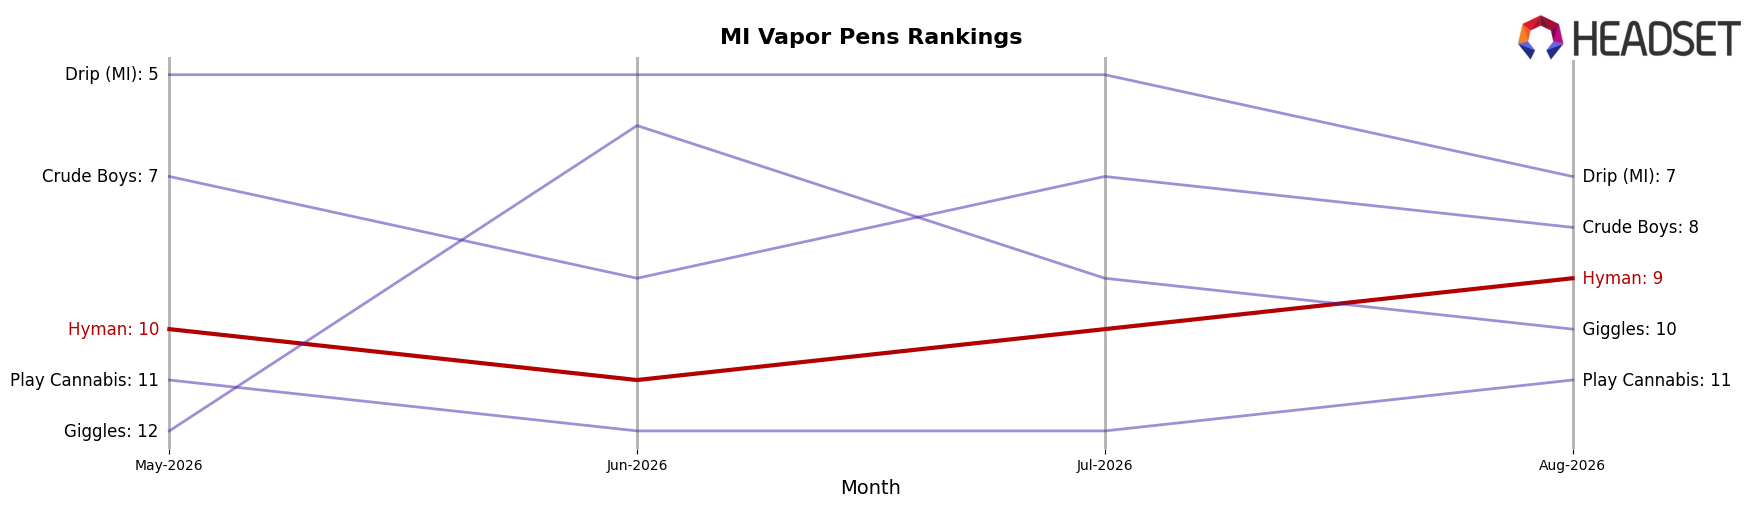
Hyman sits at rank #9 in MI Vapor Pens in August 2026, an improvement of 30 positions year over year from #39, while its three-month trajectory nudged from #10 in May 2026 to #9 and its peak position of #8 came in March 2026; in contrast, MKX Oil Company advanced from #2 to #1 and Muha Meds eased from #3 to #2 as its sales fell 8.8% year over year. Meanwhile, Mitten Extracts dropped from #1 to #3 with a 24.2% sales decline and Society C climbed from #16 to #4 on 322.5% sales growth, indicating that Hyman’s ascent into the top 10 is occurring amid accelerated turnover at the top and implies headroom for incremental share capture if the brand converts recent rank momentum into sustained placement stability.
Notable Products
Pillow Talk Live Resin Stylus Disposable (2g) posted the standout move in August 2026 with a 40.7% month-over-month increase while holding rank 4, whereas Goosebumps Live Resin Cartridge (2g) rose 36.2% at rank 1, indicating gains were concentrated at the very top rather than driven by a single breakout SKU. Screw Ball Sherbert Live Resin Stylus Disposable (1g) added 19.1% at rank 2, and with Vapor Pens occupying ranks 1 through 10, at least ten of the top ten SKUs cluster in the same category, implying a narrow but accelerating demand corridor. The absence of declines over 10% alongside multiple double-digit increases suggests mix stability even as heavier 2g formats expand share at higher ranks. Taken together, the pattern implies Hyman is consolidating around Vapor Pens with momentum favoring larger-format live resin offerings, a direction that prioritizes depth in a single category over breadth across segments.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

