
Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Jeff's Sessions is stocked at 164 licensed dispensaries across Oregon and California, 117 of them in Oregon, with the deepest coverage in Eugene, Salem, Portland, Bend, and Medford. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
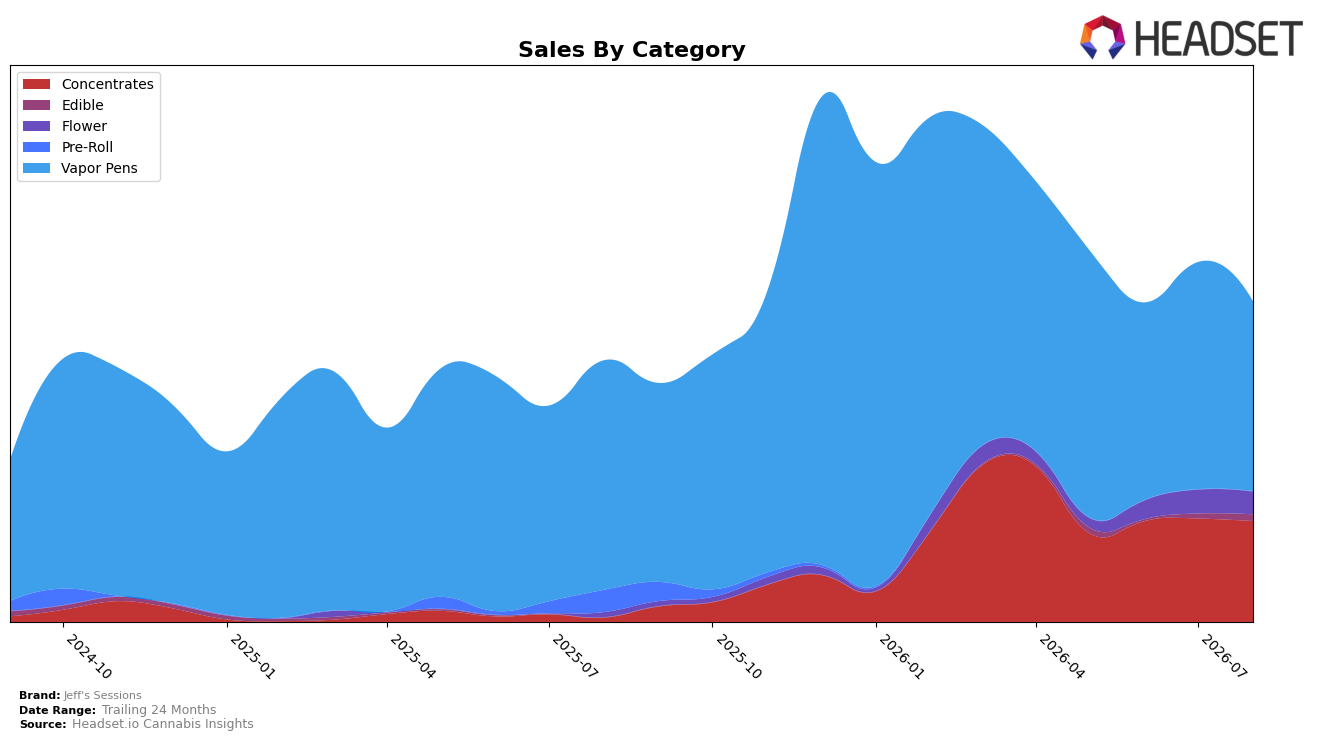
Jeff's Sessions shifted its category mix in August 2026 toward Concentrates at 31.56% share (up 2,514.60% YoY but down 2.50% MoM) while Vapor Pens, still the largest at 59.48% share, contracted by 17.37% YoY and 16.47% MoM. Flower rose to 6.996% share with 380.63% YoY growth but slid 4.97% MoM, and Edible, at 1.96% share, jumped 38.29% MoM with no YoY baseline. With brand sales up 22.68% YoY and average price up 2.78% YoY, this mix shift implies growth is being carried by rapid category diversification even as the legacy Vapor Pens base retrenches.
In California Vapor Pens where Jeff's Sessions sits at rank 100, the 16.47% MoM decline and 17.37% YoY decline in that category signal weaker traction in its lead segment, while the 2,514.60% YoY surge in Concentrates and 380.63% YoY rise in Flower suggest a repositioning toward value-driven, lower average price points ($9.42 in Concentrates vs. $13.14 in Vapor Pens) and format breadth. The combination of a 31.56% Concentrates share and a 6.996% Flower share, alongside a 38.29% MoM uptick in Edible at 1.96% share, implies the brand is hedging dependence on Vapor Pens and leaning into categories that can expand distribution and trial despite short-term MoM softness.
Competitive Landscape
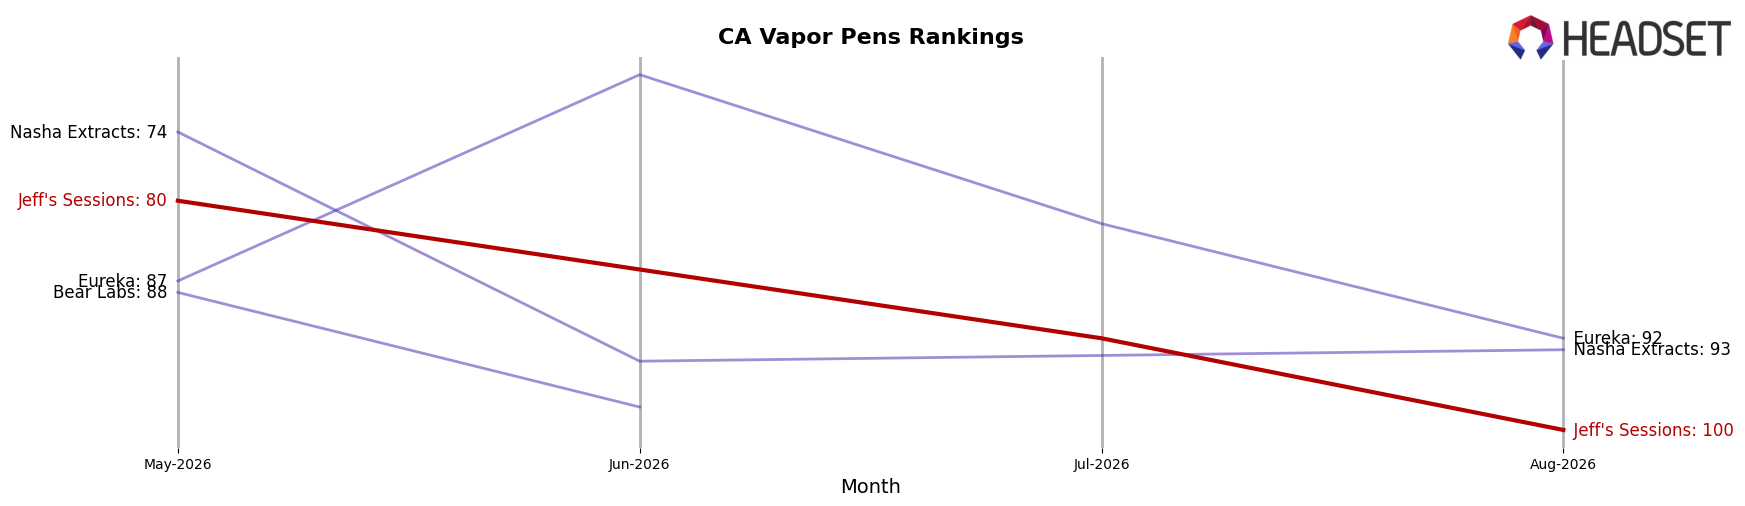
Jeff's Sessions ranks #100 in CA Vapor Pens in August 2026, down 16 places year over year from #84 and trailing its three-month position of #80 by 20 ranks, while the brand’s peak at #52 in December 2025 underscores a 48-place slide from its high-water mark; by contrast, Jetty Extracts climbed from #4 to #3 with a 40.47% year-over-year sales increase and Plug Play slipped from #3 to #4 alongside a 14.28% sales decline, indicating that Jeff's Sessions is losing relative placement as upward-momentum competitors consolidate higher ranks and even softening leaders like STIIIZY hold #1 despite an 10.93% sales drop; the pattern implies Jeff's Sessions is drifting from mid-pack relevance toward long-tail visibility, where recovery requires rank gains of 20–30 positions to re-enter competitive consideration.
Notable Products
Caramel Runtz Badder (1g) posted the steepest decline in August 2026 at -39.2% MoM and slipped to rank 8, while Banana Cake Badder (1g) fell even harder at -45.5% MoM to rank 9, indicating that two Concentrates in the badder format are rapidly losing velocity versus July. In contrast, Blue Dream Distillate Cartridge (1g) rose 34.1% MoM to rank 1 and Skywalker OG Live Resin Cartridge (1g) climbed 28.3% MoM to rank 2, putting Vapor Pens ahead of Concentrates in both growth and placement. With four of the top ten coming from Concentrates but the top two ranks held by Vapor Pens, the mix implies a pivot toward inhalables with faster-repeat formats and away from slower-moving badders, suggesting near-term allocation should favor cartridges over wax/badder despite similar price tiers, as evidenced by a $4,952 month total on the number 2 SKU.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

