


Where to Buy
Just Flower is stocked at 113 licensed dispensaries across Maryland and Arizona, 81 of them in Maryland, with the deepest coverage in Baltimore, Rockville, Silver Spring, Annapolis, and Laurel. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
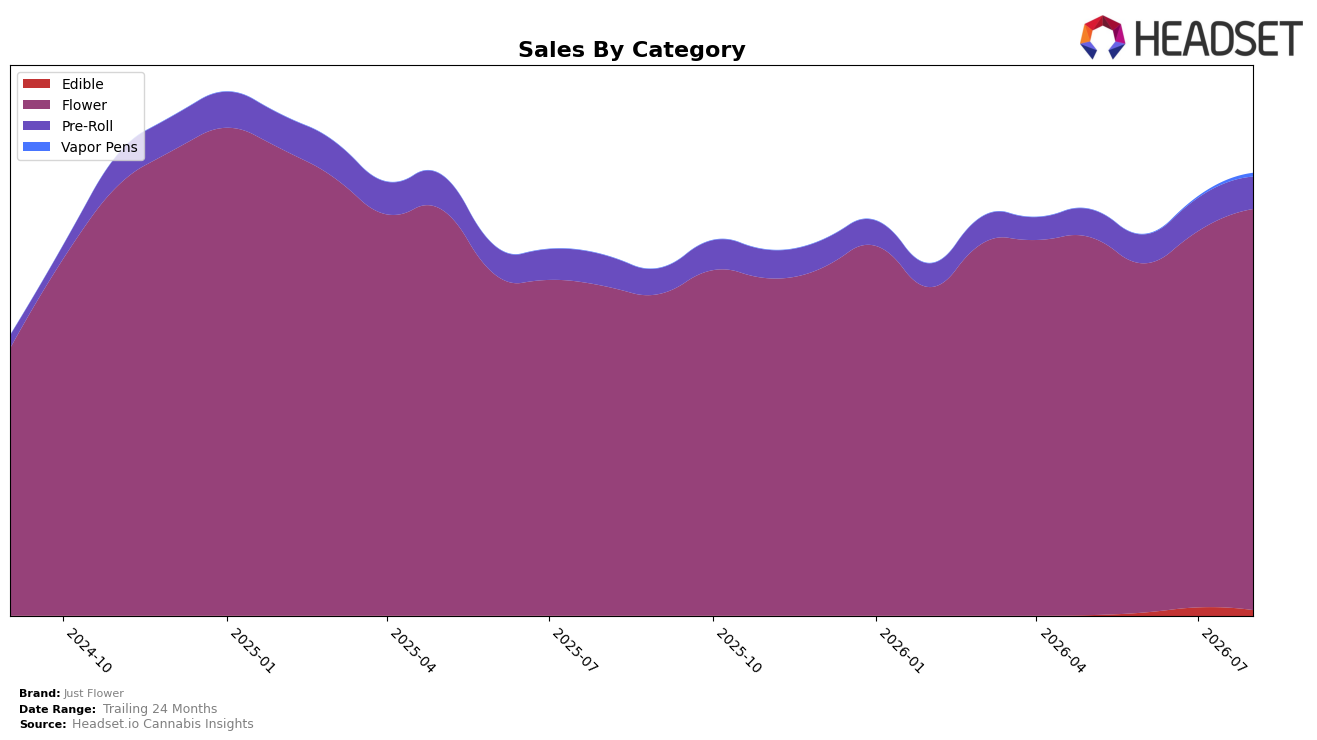
In August 2026, Just Flower concentrated 90.74% of sales in Flower with year-over-year growth of 21.72% and month-over-month growth of 6.60%, while Pre-Roll held 7.24% share with 4.43% YoY and a 3.01% MoM decline. Edible fell to 1.27% share with a 32.93% MoM contraction and no reported YoY figure, as Vapor Pens, at 0.76% share, spiked 161.61% MoM despite missing YoY data; average price for the brand rose 2.75% YoY to $21.06. In the Arizona Flower category, Just Flower ranked 1, supported by Flower’s 90.74% mix and 6.60% MoM momentum; the divergent Pre-Roll and Edible trajectories suggest a portfolio leaning harder into Flower while selectively testing Vapor Pens.
The mix shifts imply an intentional reinforcement of leadership in Flower (rank 1 in Arizona) by converting incremental demand into share defense, as a 6.60% MoM lift in a 90.74% revenue base outweighs the 3.01% MoM pullback in Pre-Roll and the 32.93% MoM cut in Edible. The 161.61% MoM jump in Vapor Pens at 0.76% share indicates a low-risk expansion lane where small absolute gains can add perceived breadth without diluting focus, while a 2.75% YoY brand-wide price increase alongside 21.72% YoY Flower growth signals pricing headroom anchored in category leadership.
Competitive Landscape
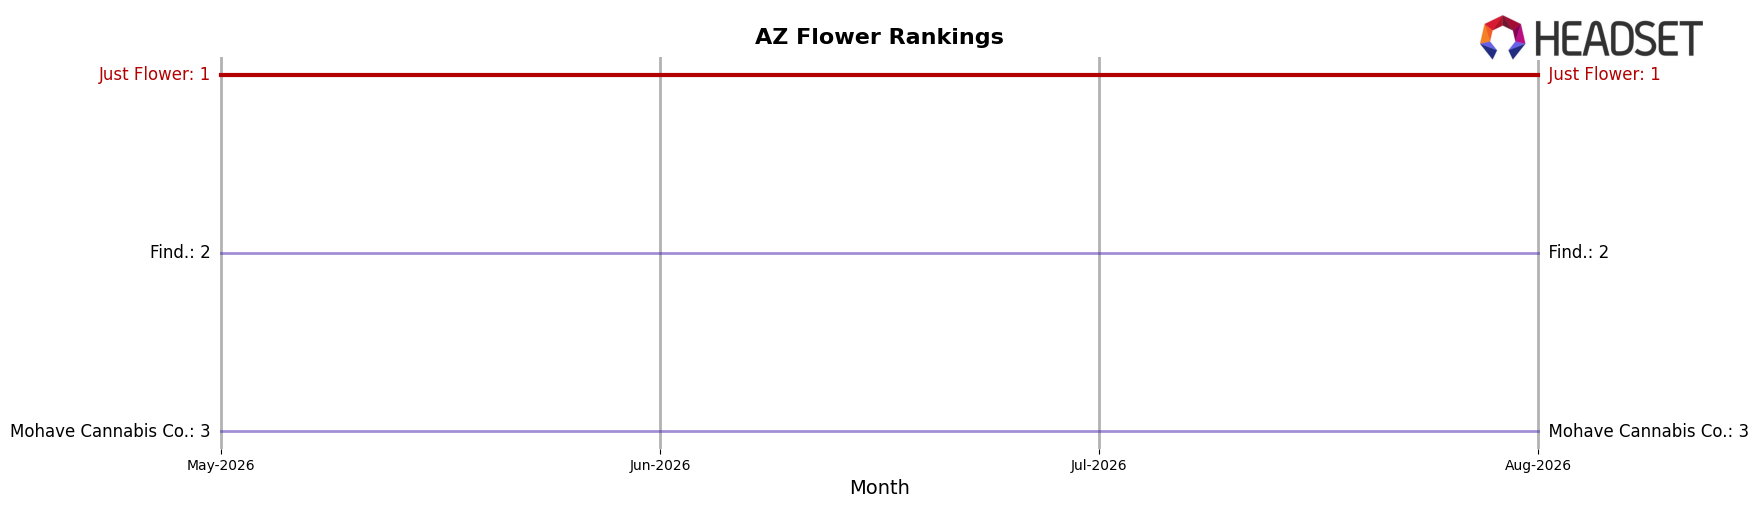
Just Flower sits at #1 in AZ Flower in August 2026, unchanged from #1 year over year, and it also held #1 three months ago, signaling no rank volatility while defending its peak rank of #1 in August 2026; meanwhile, Find. moved from #3 to #2 as of August 2026 while posting a 40.2% YoY sales increase, and Mohave Cannabis Co. slipped from #2 to #3 despite a 12.7% YoY lift, indicating that competitors are improving but not dislodging the leader; further down the leaderboard, Brown Bag held #4 with 65.2% YoY growth while The Pharm jumped from #21 to #5 on 290.0% YoY sales expansion, implying that Just Flower’s flat rank trend at #1 masks rising pressure from faster-moving challengers whose upward trajectories could compress future share even without immediate rank changes.
Notable Products
The steepest move in August 2026 is a decline, with Head Hunter (4g) sliding 9.9% month over month to rank 10 while Garlic Ghost Pre-Roll 2-Pack (1g) advanced 38.5% to rank 1. Four of the top ten are Flower SKUs clustered between ranks 2 and 10, while Pre-Rolls occupy ranks 1, 3, 4, and 6, indicating share is tilting toward smaller pack formats despite a $209,223 anchor from Cinnamon Milk (14g) at rank 2. The mix suggests Just Flower is leaning into Pre-Rolls to drive velocity while relying on large-format Flower to sustain basket value, implying a bifurcated strategy that prioritizes trial and trade-up paths in parallel.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

