

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Midweek Friday is stocked at 95 licensed dispensaries across Illinois, with the deepest coverage in Chicago, Springfield, Quincy, Addison, and Anna. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
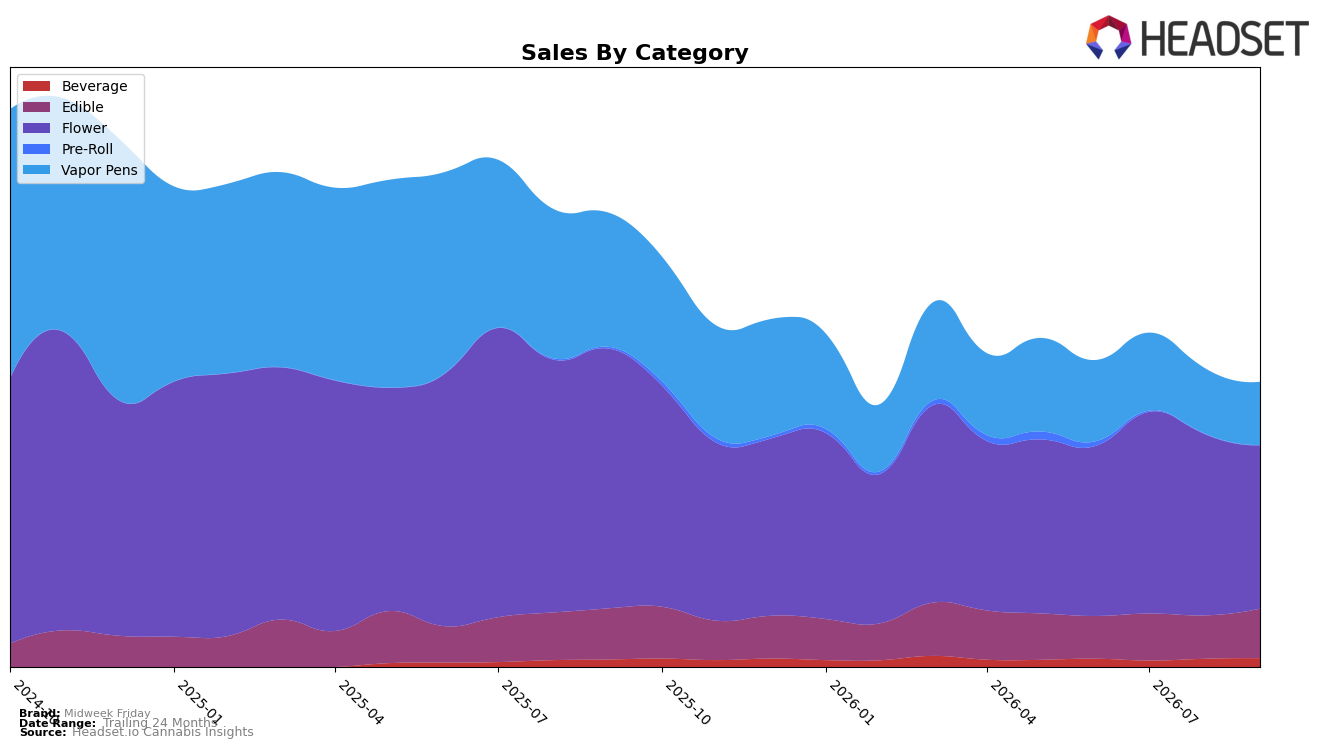
In September 2026, Midweek Friday’s mix tilted toward Flower at 57.37% share with year-over-year decline of 37.16% and month-over-month decline of 9.92%, while Vapor Pens held 22.16% share with steeper year-over-year decline of 52.99% and a 3.23% month-over-month dip. Edible expanded to 17.32% share on a 14.17% month-over-month increase but only a 3.18% year-over-year decline, and Beverage reached 3.16% share with 16.62% year-over-year growth and 6.87% month-over-month growth. With the overall brand down 37.31% year over year and average price down 12.35%, the pattern implies mix rebalancing toward lower-price-per-unit formats (Edible and Beverage) is cushioning volume while higher-priced Flower and Vapor Pens contract more sharply.
Positioning-wise, concentration in Flower at 57.37% share alongside a rank of 16 in Flower in Illinois suggests reliance on a category with sharper contraction than the brand’s emerging growth pockets, while Vapor Pens’ 52.99% year-over-year drop versus Edible’s 3.18% year-over-year dip indicates a shift toward value and accessible dose formats. The 14.17% month-over-month rise in Edible and 6.87% month-over-month rise in Beverage, against a 9.92% month-over-month decline in Flower, imply reallocation headroom in non-inhalable formats to stabilize rank and margin mix if pricing remains 12.35% below last year; the thesis is that emphasizing Edible and Beverage can offset inhalable softness and reposition Midweek Friday toward steadier, price-sensitive demand.
Competitive Landscape
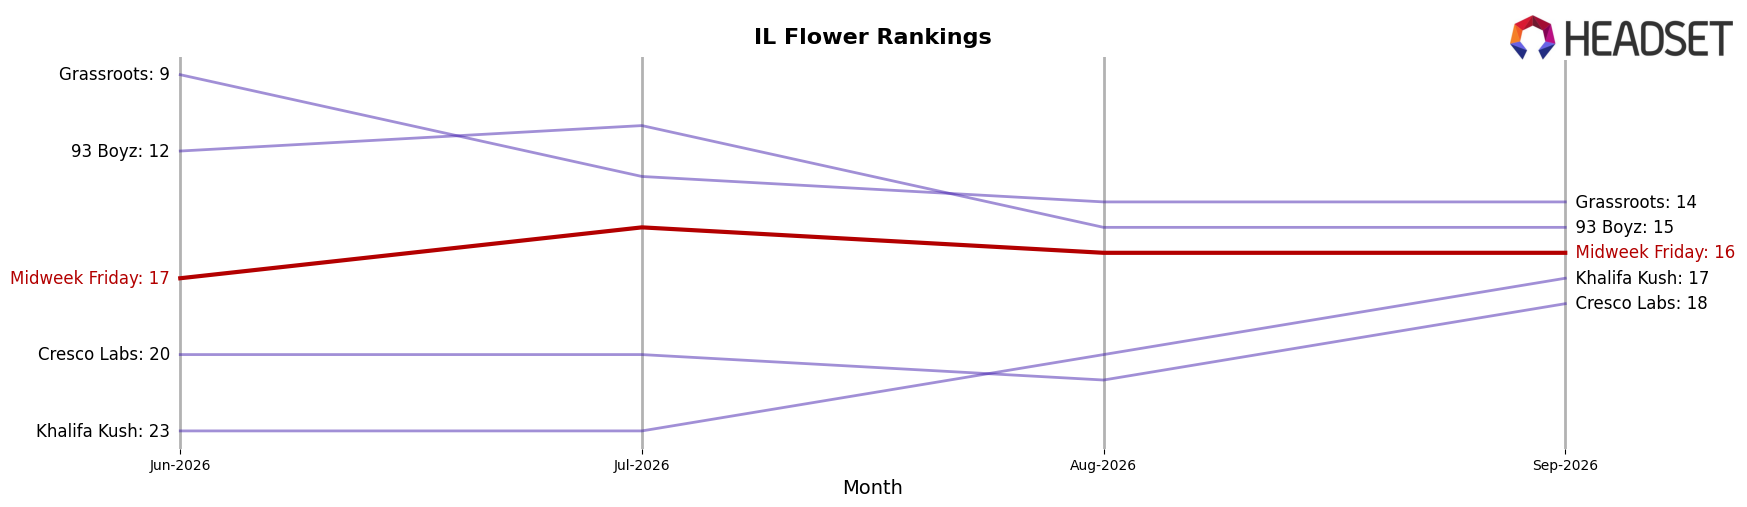
Midweek Friday ranks #16 in Illinois Flower in September 2026, down 7 positions year over year from #9, and up 1 rank versus June 2026 when it sat at #17; the brand’s prior peak was #9 in September 2025, marking a 7-rank slide from peak to current. In contrast, High Supply / Supply held #1 both year over year and currently while its sales fell 2.5%, and RYTHM remained #2 with sales up 22.0% YoY, indicating that Midweek Friday’s relative decline is more about share pressure than category contraction. With Good Green moving from #4 YoY to #3 and The Botanist rising from #27 YoY to #4 on a 495.0% YoY sales surge, the competitive set is consolidating above Midweek Friday; the rank trajectory implies Midweek Friday must either trade up in velocity or expand assortment to avoid further drift from the top 10.
Notable Products
Lemon Vibe Pectin Gummies 10-Pack (100mg) posted the standout movement in September 2026 with a +26.44% MoM lift to rank 2, while category peer Tangerine Energize Gummies 10-Pack (100mg) rose a modest +5.52% at rank 1, signaling differential momentum within the same format. Strawberry Doze Gummies 10-Pack (100mg) added +7.55% at rank 3, and with three of the top five slots held by Edible SKUs, the mix concentrates demand away from Beverage where Happy Hour - Tropical Blast Fruit Drink (100mg THC, 4oz) dipped -4.36% at rank 5. Happy Hour - Cherry Bliss Fruit Drink (100mg THC, 4oz) grew +9.66% to rank 4 but trails the faster Edible gains, implying that September 2026 product traction is consolidating around gummies over drinks and shaping assortment priorities toward flavor-led Edibles.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

