


Where to Buy
Mother Magnolia Medicinals is stocked at 142 licensed dispensaries across Oregon, with the deepest coverage in Portland, Eugene, Bend, Beaverton, and Salem. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
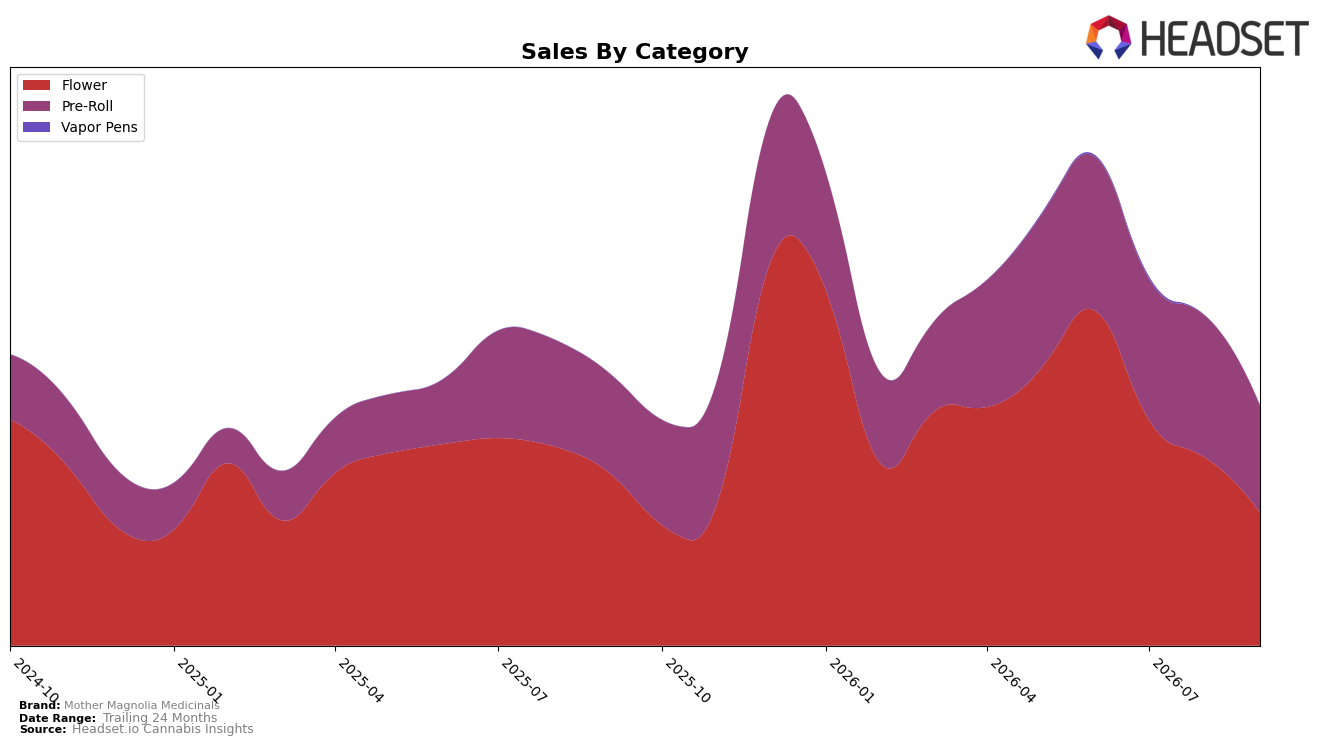
Mother Magnolia Medicinals concentrated 55.31% of September 2026 sales in Flower, where sales fell 23.46% year over year and 29.45% month over month; Pre-Roll held 44.51% share with sales up 7.25% year over year but down 24.65% month over month; Vapor Pens remained a rounding‑error at 0.18% share with a 157.29% month over month spike off a tiny base. Despite an average price decline of 31.34% year over year, total brand sales contracted 12.10% year over year and 1.33% over 24 months, and a rank of 58 in Flower in Oregon indicates the Flower-heavy mix is amplifying downside when Flower drops 29.45% month over month and 23.46% year over year, implying that category concentration is the primary drag.
The mix shift signals that reliance on Flower (55.31% share, rank 58 in Oregon) is pulling positioning toward a lower-price, volume-led stance that is not converting to growth when core demand softens by 29.45% month over month; the concurrent 7.25% year over year gain in Pre-Roll at 44.51% share suggests the brand’s relative consumer pull skews to value formats, but the 24.65% month over month drop shows that momentum is fragile without broader category diversification. With Vapor Pens at only 0.18% share despite a 157.29% month over month lift, the brand lacks a balancing premium or convenience-led pillar, implying that September 2026 positioning is overexposed to Flower volatility and reliant on discount-led Pre-Roll elasticity rather than a multi-category hedge.
Competitive Landscape
Mother Magnolia Medicinals sits at rank #58 in OR Flower in September 2026, down 14 positions YoY from #44 and sliding 35 places from #23 in June 2026, despite having peaked at #16 in December 2025; meanwhile, Grown Rogue moved from #3 to #1 YoY and Oregrown climbed from #16 to #3 alongside a 169.7% YoY sales increase, indicating that share is consolidating at the top while mid-tier ranks are thinning. With peers like PRUF Cultivar / PRŪF Cultivar dropping from #1 to #5 with a 49.3% YoY sales decline and Kaprikorn edging up from #6 to #4 on 22.0% YoY growth, the brand’s fall from #23 to #58 over three months contrasts with upward or stabilized moves among leaders, implying that Mother Magnolia Medicinals is losing rank share to faster-scaling competitors and must counter a momentum deficit rather than a broad market contraction.

Notable Products
Banana Bread Infused Pre-Roll (1g) posted the steepest slide in September 2026 at -45.8% MoM and fell to rank 9, while Lilac Diesel Pre-Roll (0.5g) also contracted by -41.2% MoM at rank 10. Tahoe Brunch Pre-Roll (0.5g) moved against this trend with a +32.3% MoM increase at rank 4, yet White Tahoe Cookies Pre-Roll (Half Gram) dropped -20.9% MoM at rank 6. With six of the top ten coming from the Pre-Roll family but showing three double‑digit MoM declines against one double‑digit gain, the pattern implies a portfolio overweight in Pre-Rolls that is fragmenting, pushing Mother Magnolia Medicinals toward stabilizing formats while selectively backing the few Pre-Roll SKUs still comping up.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

