

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
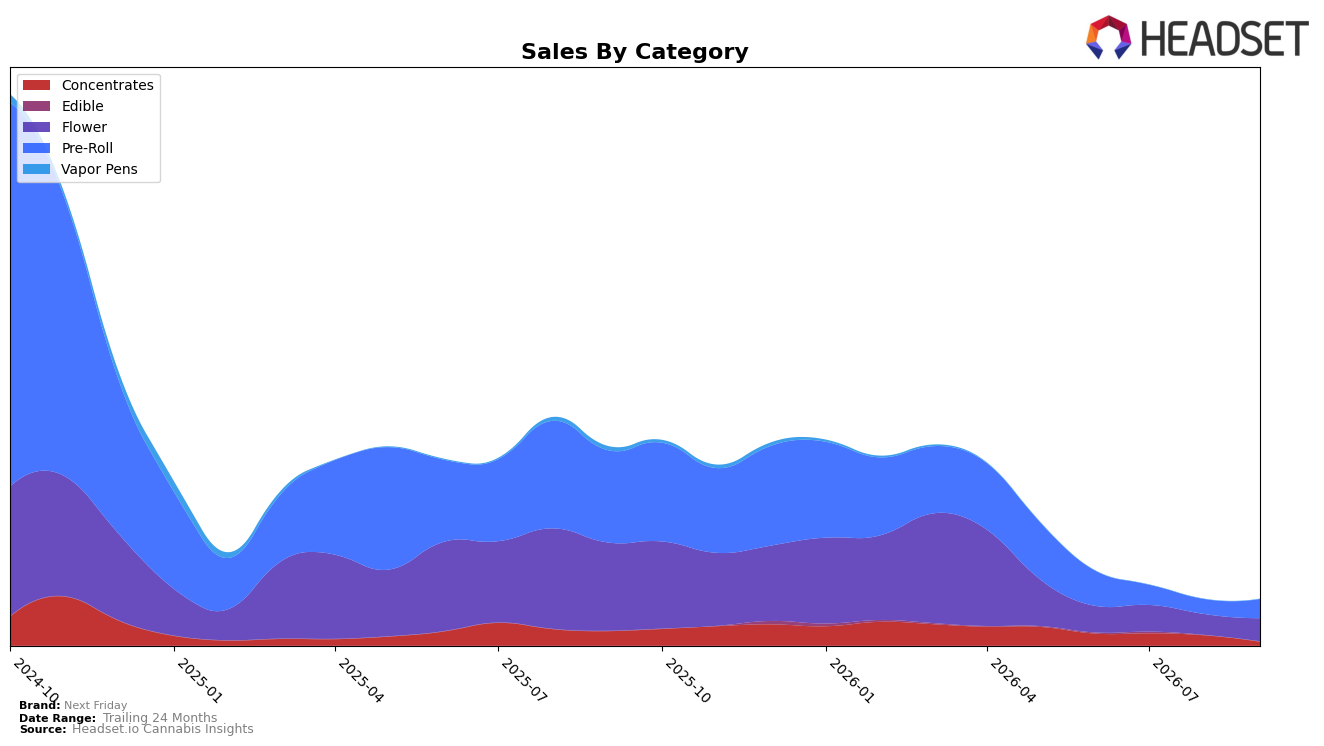
In September 2026, Next Friday concentrated nearly half of sales in Flower at 49.97% share while Pre-Roll accounted for 41.56%, with Concentrates at 8.17% and Edible at 0.30%; within that mix, Flower declined year over year by 74.20% but rose month over month by 10.81%, and Pre-Roll fell year over year by 79.48% yet gained month over month by 28.98%. Concentrates contracted sharply month over month by 63.45% despite a 74.11% year-over-year decline that was comparable to Flower, while Edible expanded 145.65% month over month off a minimal base alongside a brand-level average price that increased 14.19% year over year to $22.89; together these shifts indicate a pivot toward replenishing volume in core inhalables via promotional or mix-driven month-over-month lifts while specialty formats retreat.
The category-weighted recovery in Flower (+10.81% MoM) and Pre-Roll (+28.98% MoM) against steep brand-level sales contraction of 77.08% year over year implies a defensible base in mainstream inhalables rather than breadth across form factors, a stance reinforced by Concentrates’ 63.45% month-over-month pullback and Edible’s 0.30% share despite a 145.65% month-over-month jump. With Flower ranked 50 in Saskatchewan and the brand’s 24‑month sales down 91.76%, the mix suggests prioritizing visibility and price-pack architecture in Flower and Pre-Roll to stabilize rank while deprioritizing low-share niches until sustained share gains exceed double-digit month-over-month volatility.
Competitive Landscape
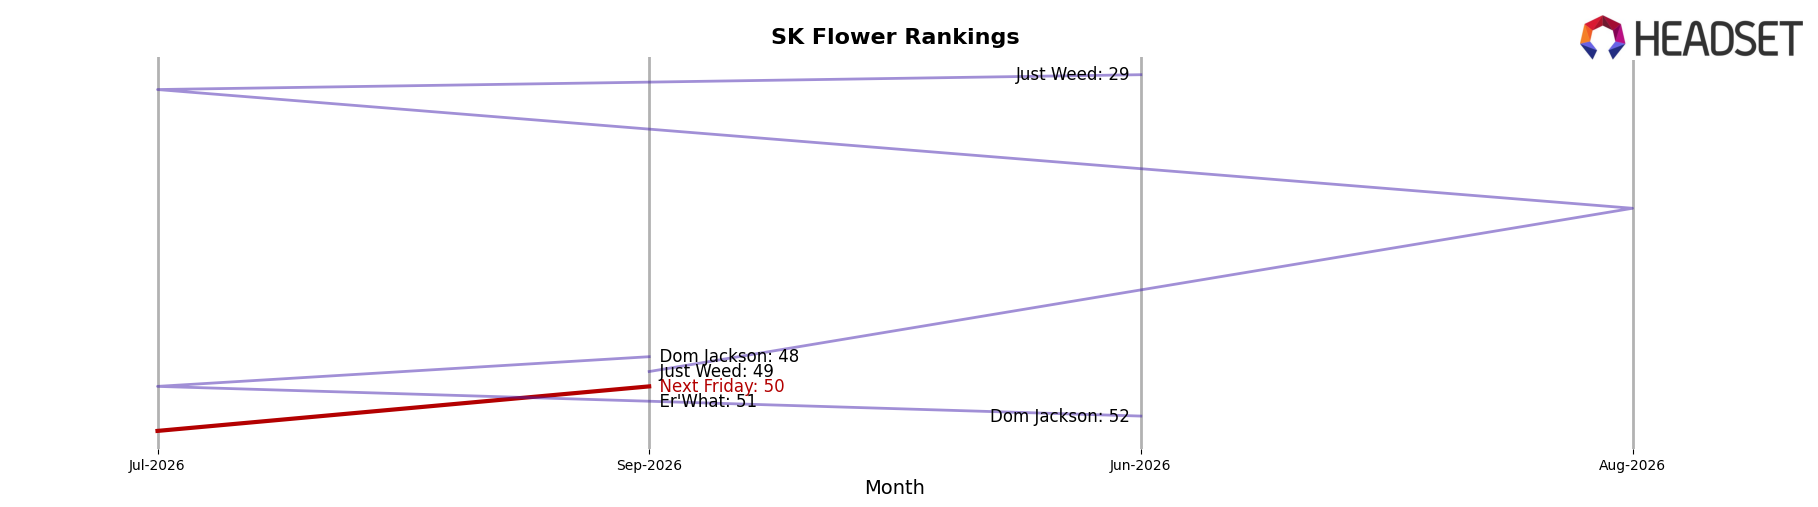
Next Friday sits at rank #50 in SK Flower for September 2026, a 10-place improvement from #60 year over year, and a 14-place climb from #64 three months ago; by contrast, Spinach advanced from #5 to #2 while Good Supply slid from #3 to #4, and the category leader Back Forty / Back 40 Cannabis held steady at #1 as its sales grew 22.8% year over year. Despite a prior peak at #31 in April 2026, the current #50 position alongside competitors moving up faster—such as Spinach with 60.2% YoY sales growth and Big Bag O' Buds rising to #3 from #6—implies that Next Friday’s recent gains are lagging the pace-setters and point to a stabilization phase rather than a return to its April 2026 peak without a share-accretive shift.
Notable Products
Blueberry Fuego Pre-Roll 3-Pack (1.5g) posted the standout movement in September 2026 with a +317% month-over-month surge to rank 5, while Blueberry Fuego Shatter (1g) fell -73% to rank 8, marking the steepest decline among the top ten. Burner Phone Special Pre-Roll 14-Pack (7g) climbed +77% to rank 3 as Burner Phone Special Pre-Roll (0.5g) slid -12.8% to rank 1, and Blueberry Fuego (7g) contracted -50.6% at rank 10. Seven of the top ten are Pre-Roll SKUs, indicating a portfolio tilt toward multi-pack and value-oriented inhalables over single-gram formats.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

