


Is this your brand?
See your full sales and distribution data: where you sell, how you're priced, and how you rank against the brands next to you on the shelf.
See your brand's dataCarry this brand in your store?
Headset Retailer is free. Connect your POS and see what's selling and what's sitting.
Sign up freeMarket Insights Snapshot
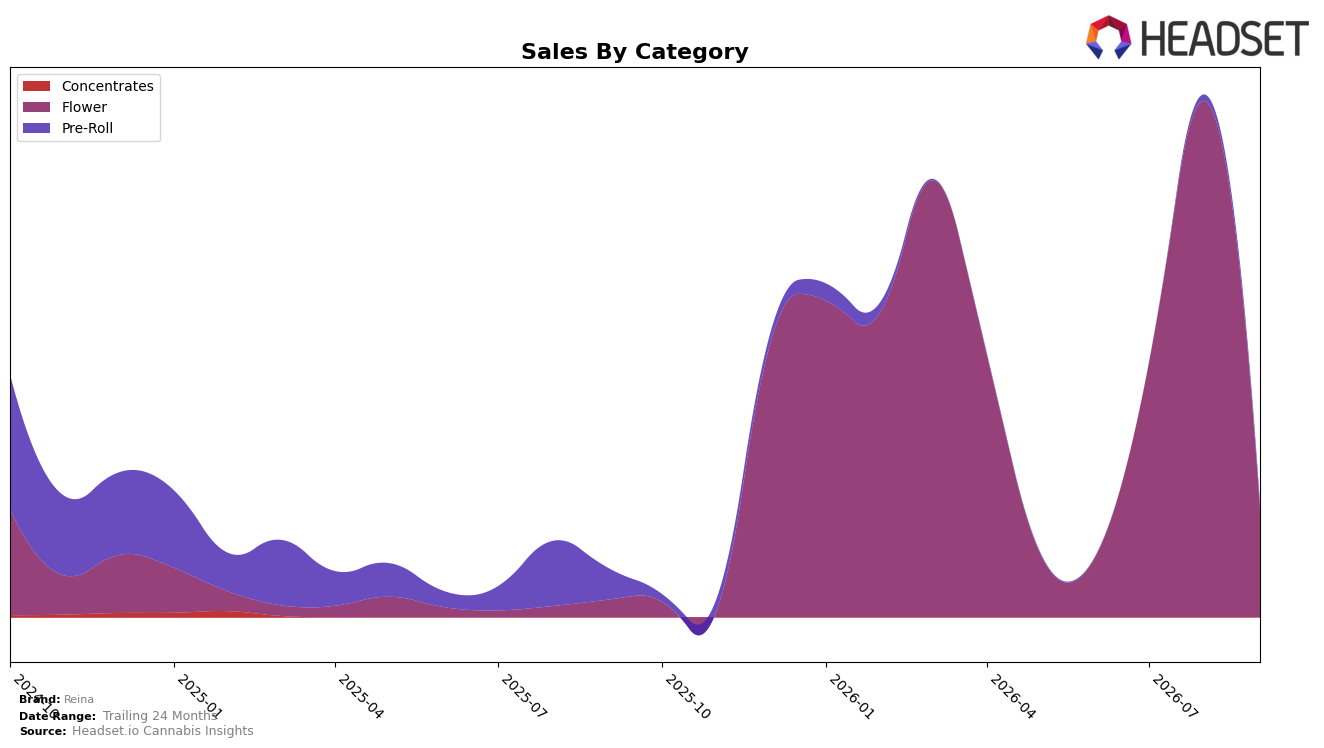
In September 2026, Reina concentrated 95.09% share in Flower with a 525.34% year-over-year change, while Pre-Roll held 4.91% share with an -82.18% year-over-year shift; month over month, Flower moved -79.14% and Pre-Roll moved -10.04%. Despite total brand sales up 133.69% year over year, the average price indexed up 288.69%, and Flower’s average price sat at $46.12 versus Pre-Roll at 4.57, pointing to a volume contraction masked by mix and price effects; the pattern implies a pivot toward premiumized Flower concentration at the expense of breadth.
With a 49 rank in Flower in Nevada and a 95.09% mix concentration, the -79.14% month-over-month in Flower versus -10.04% in Pre-Roll implies exposure to seasonal or supply-driven volatility amplified by reliance on one category; the 24-month sales change of 11.61% against a 288.69% average price rise signals margin-led gains rather than sustained unit expansion. The pattern implies Reina’s positioning is anchored to high-price Flower in Nevada, trading share stability for price-led revenue, which may cap discoverability in lower-priced formats and heighten rank sensitivity when Flower demand normalizes.
Competitive Landscape
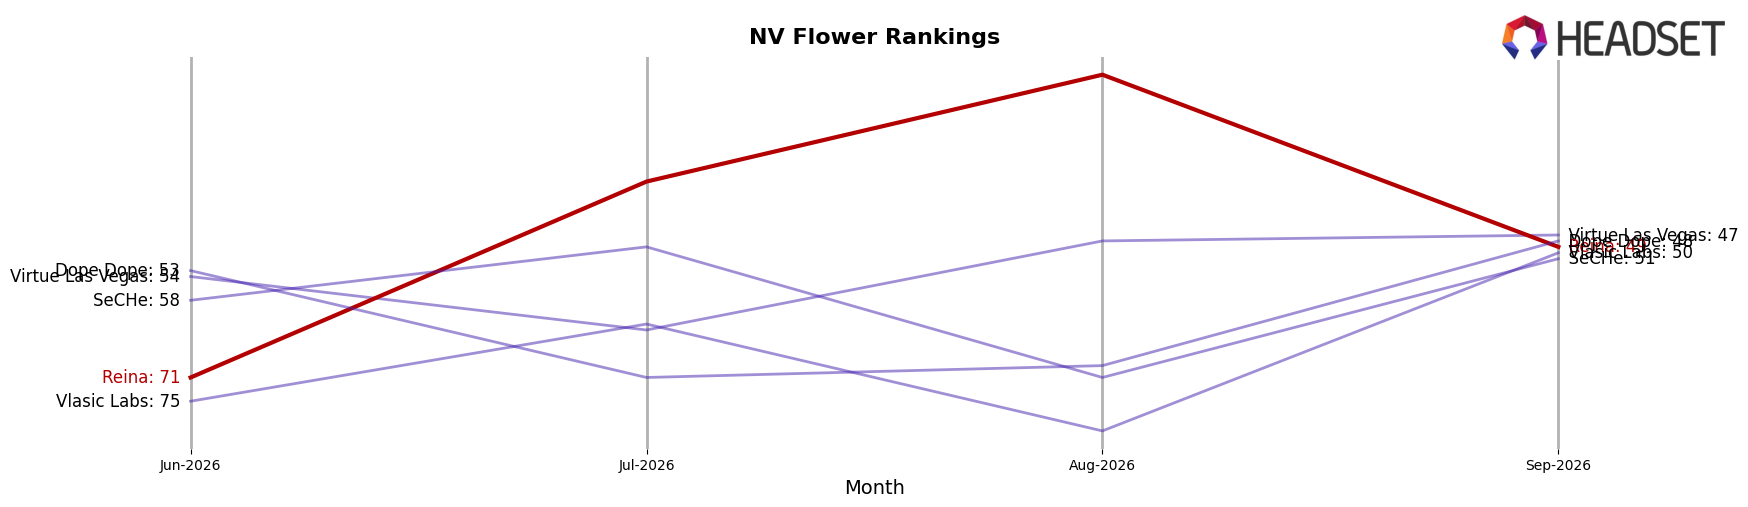
Reina sits at rank #49 in NV Flower for September 2026, improving 54 positions year over year from #103, and rising 22 spots since June 2026 when it was #71; however, the brand remains 29 ranks below its August 2026 peak at #20 and 48 places behind category leader RYTHM at #1, while STIIIZY holds #2 with a 24.2% year-over-year sales gain that outpaces Reina’s implied ascent, and Alternative Medicine Association / AMA advanced from #5 to #3 alongside a 32.6% lift; taken together, the sharp YoY climb paired with a short-lived August peak implies Reina’s trajectory is upward but still searching for sustained top-30 staying power against faster-rising incumbents.
Notable Products
Divorce Cake (14g) posted the steepest movement in September 2026 with an -83.9% month-over-month drop while sliding to rank 5, contrasted against OG Kush (14g) at rank 3 with a milder -8.8% decline. Flower occupies six of the top ten ranks, including White Truffle (14g) at rank 1 and Trainwreck (3.5g) at rank 9, indicating concentration at the top and tapering depth in lower positions; White Truffle (14g) also anchored category dollars at $30,911. The pattern implies the Flower portfolio is relying on a single flagship while a major mid-tier SKU reset is redistributing share toward smaller Flower sizes and steady Pre-Rolls, shifting Reina’s mix toward price-point diversification over uniform large-format dominance.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

