
Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Rkive Cannabis is stocked at 92 licensed dispensaries across Michigan, with the deepest coverage in New Buffalo, Detroit, Monroe, Adrian, and Sturgis. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
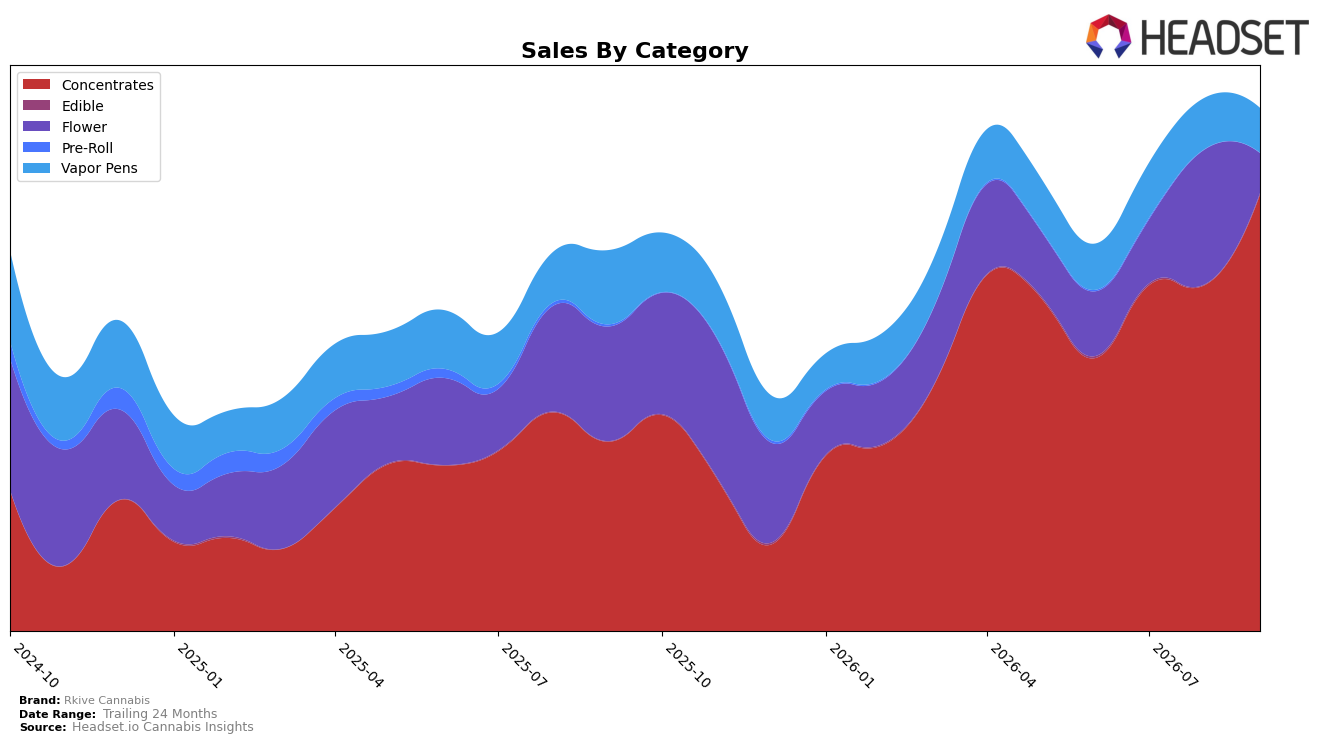
Rkive Cannabis concentrated its mix in Concentrates at 83.64% share with year-over-year growth of 130.87% and month-over-month growth of 26.19%, while Vapor Pens fell to 8.53% share with a -39.81% YoY decline and a -12.81% MoM slide. Flower contracted to 7.59% share with a -65.36% YoY drop and a -70.58% MoM pullback, even as Edible, though only 0.24% share, spiked 420.76% YoY and 210.05% MoM. With average price up 73.98% YoY to $44.24 and overall brand sales up 37.58% YoY, the mix shift implies a conscious trade-up toward higher-priced Concentrates while de-emphasizing lower-priced Flower.
Holding rank 1 in Concentrates in Michigan alongside an 83.64% category share of brand sales and 26.19% MoM growth indicates that Rkive Cannabis’s competitive moat now relies on depth in a single category, not breadth across Vapor Pens or Flower, which posted -12.81% and -70.58% MoM declines respectively. The outsized Edible growth of 210.05% MoM from a 0.24% base, combined with 130.87% YoY expansion in Concentrates, suggests the brand’s positioning is migrating toward potency-led shoppers while leaving price-sensitive segments underserved, a stance that can sustain premium pricing but increases exposure to category cyclicality.
Competitive Landscape
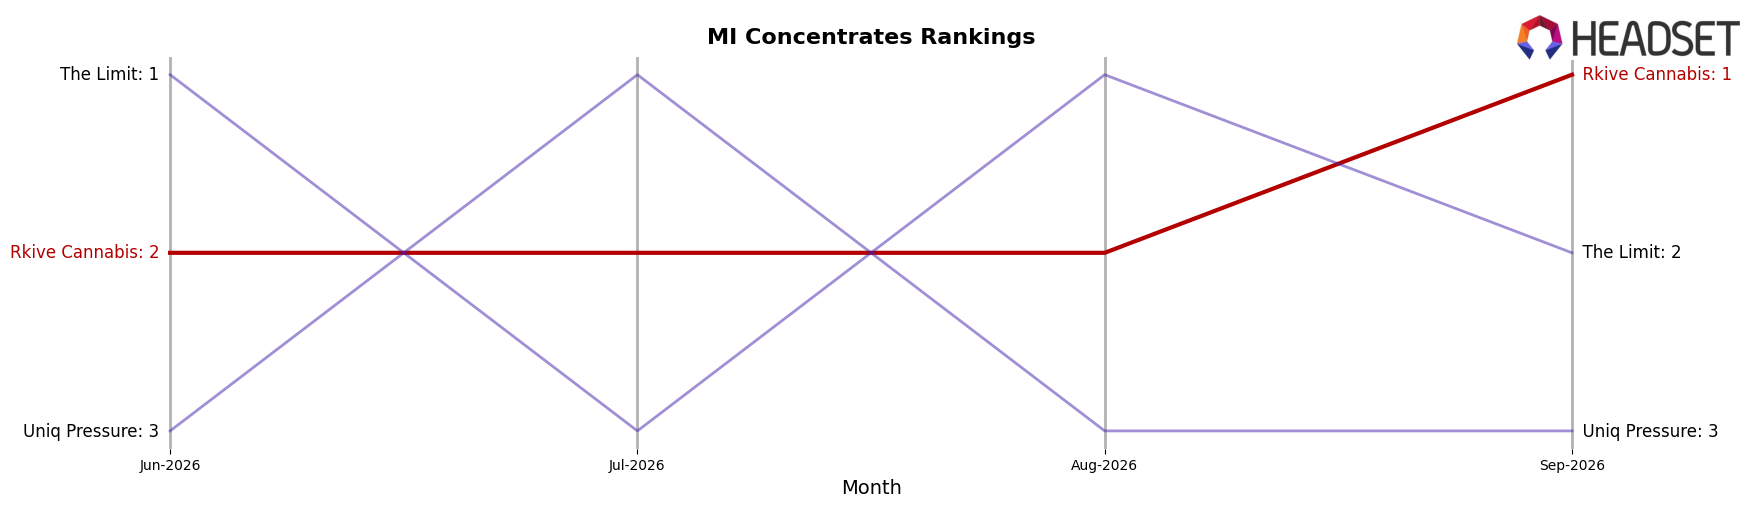
Rkive Cannabis sits at rank #1 in MI Concentrates in September 2026 after climbing 2 positions year over year from #3 to #1, and it moved up 1 position since June 2026 when it was #2; meanwhile, The Limit slipped from #1 year over year to #2 despite an 11.9% sales increase, and Uniq Pressure surged from #96 to #3 on 2,216.9% YoY sales growth, indicating that Rkive Cannabis’s ascent to a peak rank of #1 in September 2026 is a defensive position that must counter fast-rising challengers rather than a static leadership.
Notable Products
Olswell x Rkive - Candy Cartel Hash Rosin (5g) posted the standout move in September 2026 with a +56.6% month-over-month surge while climbing to rank 4, contrasted by Black Maple (3.5g) dropping -15.8% at rank 8. Olswell x Rkive - Oishii Hash Rosin (5g) held rank 1 with +16.2% growth, and Olswell x Rkive - LA Runtz Hash Rosin (5g) advanced to rank 3 on +43.8%. Five of the top ten are Concentrates SKUs, and that cluster includes three in the top five, indicating a market pull toward premium hash rosin despite Flower volatility. The mix implies Rkive Cannabis is concentrating commercial bets on high-potency concentrates, using flagship rosin gains to offset softness in mid-ranked Flower while anchoring revenue at the top with Oishii Hash Rosin (5g) around $224,907.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

