

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
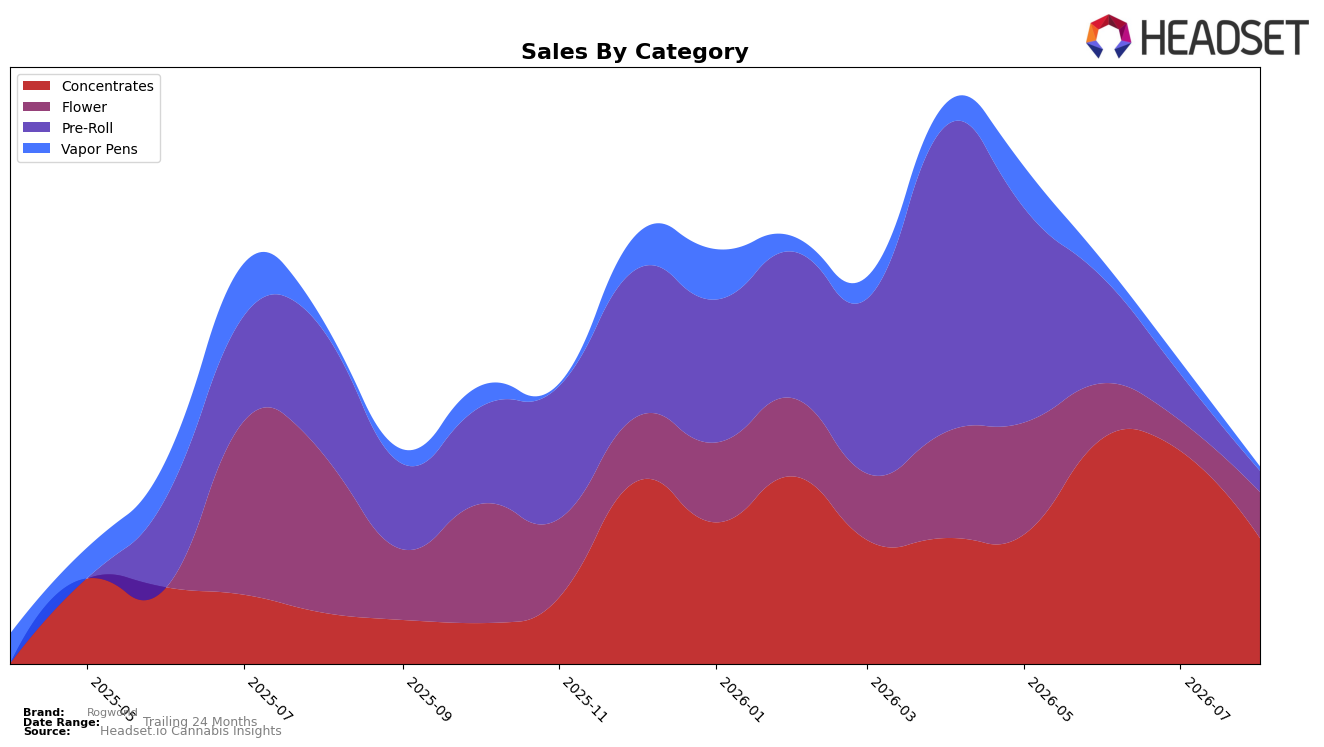
In August 2026, Rogworld concentrated 63.97% of sales in Concentrates, where sales grew 144.97% year over year but fell 40.94% month over month, while Flower held 23.31% share with a 71.03% YoY decline yet a 52.99% MoM rebound. Pre-Roll slipped to 10.63% share with YoY at -83.07% and MoM at -54.82%, and Vapor Pens accounted for 2.10% with YoY at -55.92% and MoM at -66.22%. With average price up 10.92% YoY and brand sales down 42.57% YoY, the mix points to a pivot toward higher-priced Concentrates offset by sharp month-over-month pullbacks, implying a volatility-driven dependence on a single category.
The shift toward Concentrates alongside a 52.99% MoM recovery in Flower suggests Rogworld is narrowing focus around a premium-led core while using Flower as a buffer against category-specific swings; however, rank 35 in Concentrates in British Columbia and a 66.22% MoM drop in Vapor Pens indicate limited breadth. Given that Pre-Roll contracted 83.07% YoY and 54.82% MoM while Concentrates carried nearly two-thirds of mix at 63.97%, positioning hinges on defending a mid-pack niche in Concentrates and rebalancing toward categories with steadier month-to-month trajectories.
Competitive Landscape
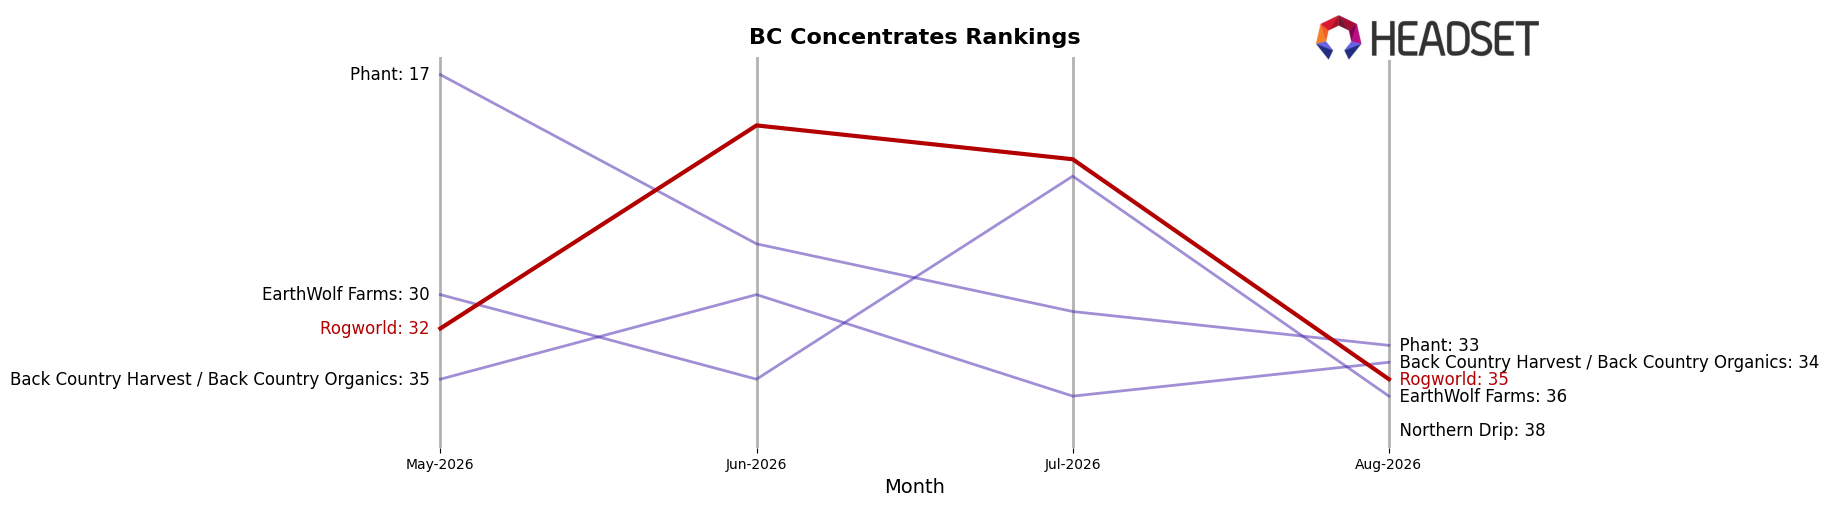
Rogworld sits at rank #35 in August 2026, improving 7 positions from #42 year over year, but sliding 3 spots from #32 since May–July quarter positioning, indicating mixed momentum versus a prior peak of #20 in June 2026; meanwhile, Dab Bods moved from #4 to #1 with 127.2% YoY sales growth and BoxHot advanced from #7 to #2 with 161.9% YoY growth, while Vortex Cannabis Inc. slipped from #2 to #3 alongside a 10.4% YoY sales decline. The combination of a 7-rank YoY climb but a 15-rank drop from the June 2026 peak implies Rogworld’s trajectory is stabilizing below earlier highs as faster-rising leaders compress the middle tier.
Notable Products
Strawberry OG Whipped Live Resin (1g) posted the steepest contraction at -73.7% MoM while falling to rank 4, even as Mango Zkittlez OG Whipped Live Resin (1g) surged +121.8% MoM to rank 1, signaling a rapid substitution within the same concentrates tier. Papaya Guava Live Rosin (1g) declined -32.6% MoM at rank 2 and Ultra Garlic Pre-Roll 3-Pack (1.5g) plunged -94.6% MoM at rank 8, while Ultra Garlic Pre-Roll 5-Pack (2.5g) slid -65.8% at rank 7, indicating fragmentation and downshift in the Pre-Roll line. With two of the top four SKUs coming from Concentrates and three Pre-Roll variants clustered between ranks 3 and 8, the assortment is bifurcating toward a concentrates-led top while Pre-Rolls lose momentum; Cadillac Rainbow (14g) countered with +119.0% MoM to rank 5 and $8,450 in sales, pointing to a secondary lift in value Flower. The pattern implies Rogworld is pivoting toward higher-velocity concentrates with selective Flower upsides, while rationalizing overlapping Pre-Roll formats could release share back to the fastest-moving concentrates.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

