


Market Insights Snapshot
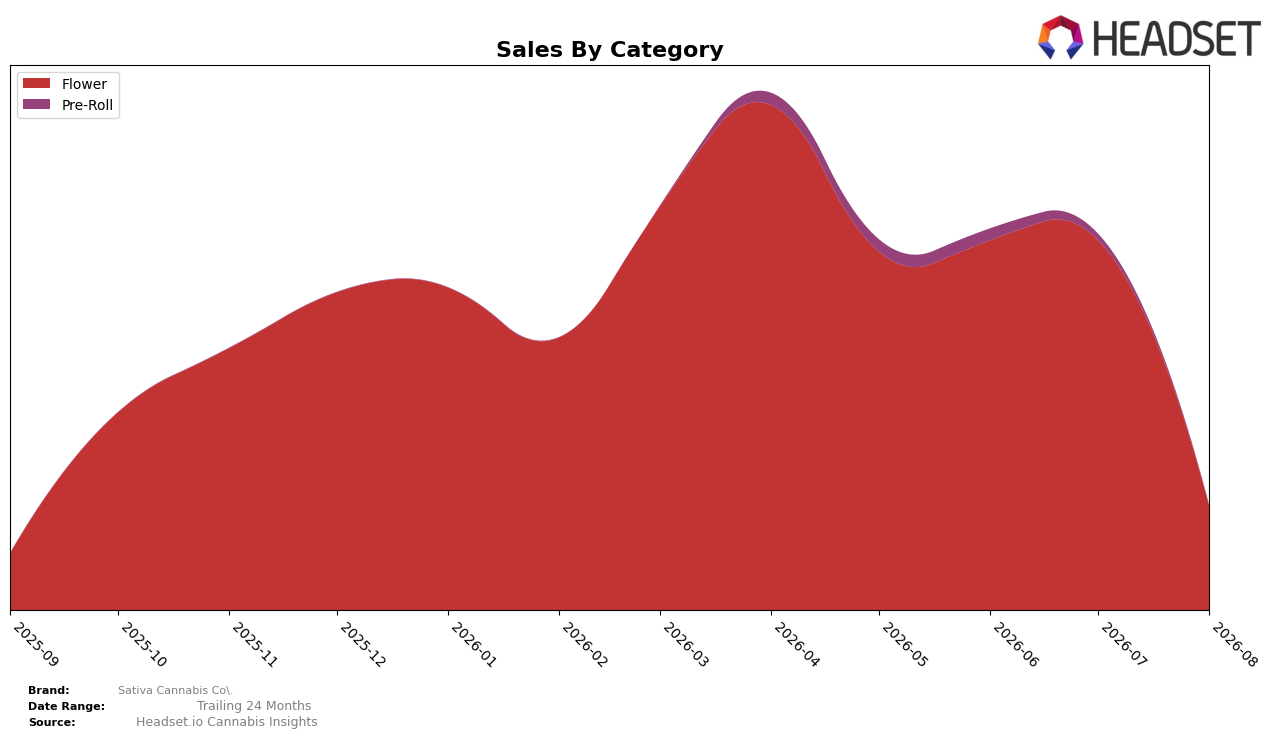
In August 2026, Sativa Cannabis Co.’s category mix was overwhelmingly concentrated in Flower at 99.14% share while Pre-Roll held 0.86% share, indicating a narrow portfolio tilt. Month over month, Flower declined by 71.86% and Pre-Roll fell by 85.40%, with the weighted average price at $46.83 and category price points diverging at $48.26 for Flower versus $10.58 for Pre-Roll. The brand’s Flower rank sat at 45 in Arizona, placing it in a lower tier of the leaderboard relative to the market’s top clusters; combined with the dual declines of 71.86% and 85.40%, this implies overexposure to a single category and limited cushion from Pre-Roll during downturns.
The August 2026 mix suggests positioning risk: with 99.14% of sales in Flower and a 71.86% month-over-month contraction, the brand’s market presence is tightly correlated to Flower volatility. The 0.86% Pre-Roll share, shrinking 85.40% month over month, indicates that cross-category spillover is not offsetting Flower softness, and a 45th rank in Arizona Flower points to limited competitive pull at current price tiers. Together, the rank of 45 and the simultaneous 71.86% and 85.40% declines imply that Sativa Cannabis Co. is positioned as a category specialist without diversification leverage, making gains contingent on Flower recovery or a rapid reweighting toward adjacent formats.
Competitive Landscape
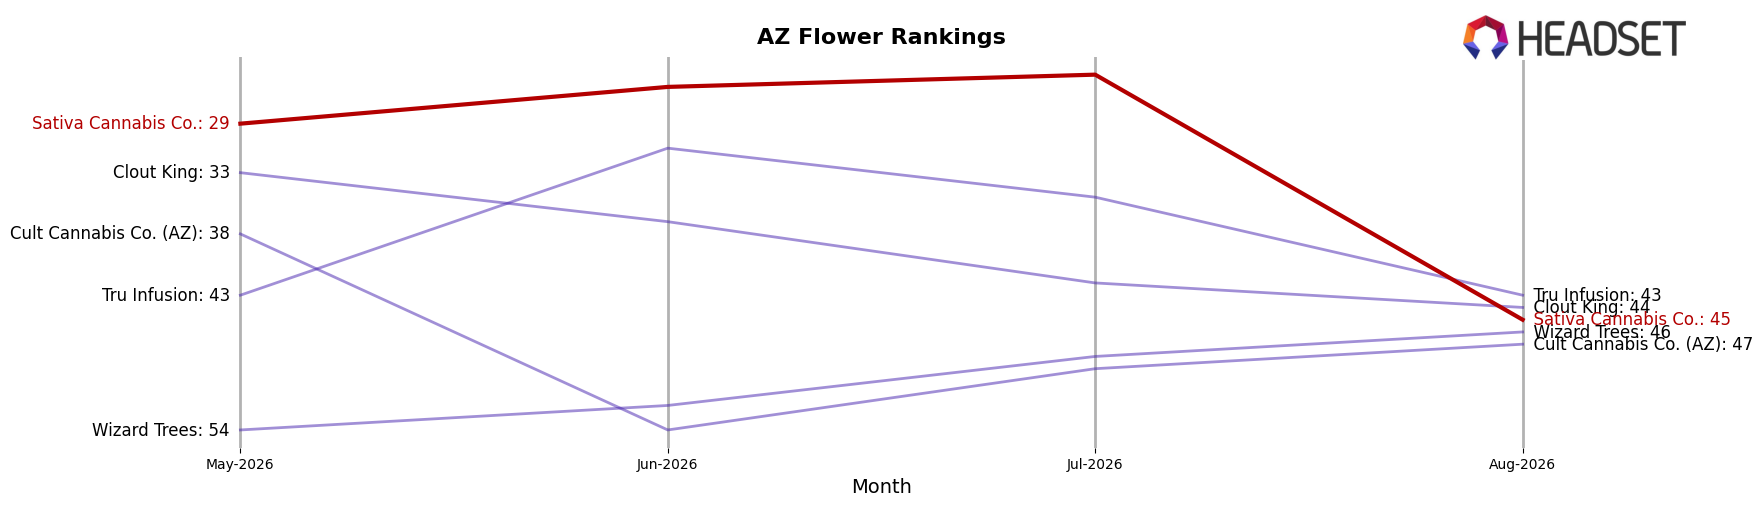
Sativa Cannabis Co. sits at rank 45 in AZ Flower in August 2026, slipping 16 positions from rank 29 in May 2026 and falling 20 spots from its peak rank 25 in July 2026; the gap to the frontier widened as Just Flower holds rank 1 while The Pharm surged from rank 21 to rank 5 year over year. Against this backdrop, competitors are expanding quickly—Find. advanced to rank 2 with 40.0% YoY sales growth, while Brown Bag is rank 4 with 65.1% YoY sales growth—indicating Sativa Cannabis Co.’s relative share is compressing despite having reached its best rank in July 2026; the trajectory implies a need to arrest multi-month rank decline to avoid sliding further from the top 25 amid accelerating leader gains.
Notable Products
Premium Diesel Popcorn (14g) posted the steepest decline in August 2026 at -84.5% MoM while sliding to rank 6, and Sour Haze Ready To Roll Shake (14g) fell -81.3% MoM at rank 8, indicating a concentrated pullback in value-oriented formats rather than a broad category collapse. Despite ranking 1, Premium Diesel (14g) dropped -70.6% MoM and Jungle Haze Popcorn (14g) at rank 2 fell -46.9% MoM, while Raspberry Haze (14g) at rank 3 declined -43.7% MoM, pointing to demand compression at the top of the Flower lineup even as the top three hold share of visibility. With all listed SKUs in Flower and at least four of the top ten being large-format 14g packs, the mix skews toward bulk that is currently under pressure, implying Sativa Cannabis Co. is over-indexed to high-volume tiers that may require price architecture or pack-size diversification to stabilize.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

