

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Soar is stocked at 12 licensed dispensaries across Mississippi, with the deepest coverage in Canton, Batesville, Brandon, Diamondhead, and Jackson. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
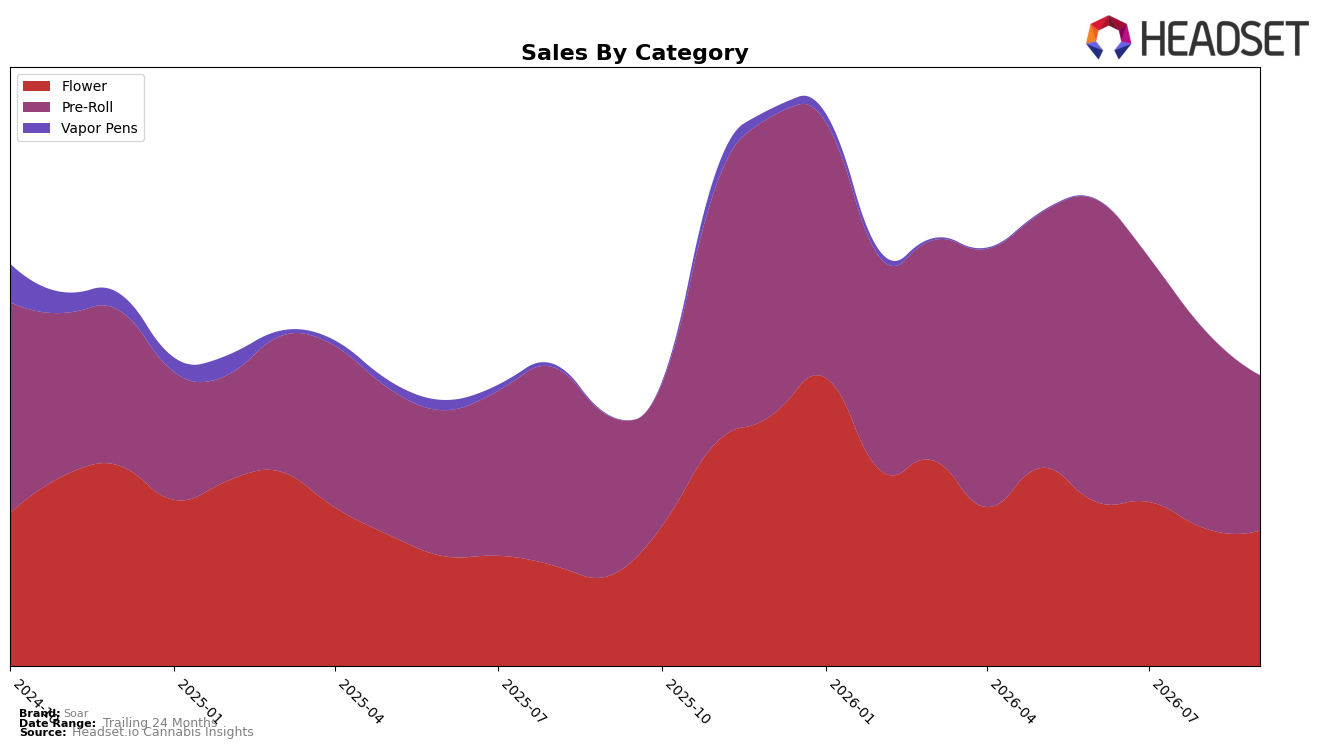
Soar’s mix in September 2026 concentrated in Pre-Roll at 53.36% share (rank 51 in Alberta Pre-Roll) while Flower held 46.64% share, and that split carried contrasting trends: Pre-Roll declined 3.32% YoY and 21.72% MoM, whereas Flower grew 50.52% YoY and slipped only 1.70% MoM. Against this backdrop, overall brand sales rose 15.77% YoY and average price increased 14.14% YoY to $22.39, implying revenue support from mix and pricing even as the largest category by share contracted MoM and the brand’s top category rank position sat at 51.
The pivot toward higher-priced Flower (average price $40.76 versus $16.06 in Pre-Roll) combined with a 50.52% YoY Flower lift and a 21.72% MoM Pre-Roll pullback implies Soar is migrating into a premium-leaning positioning where revenue per unit can offset volume softness in its legacy Pre-Roll base. With brand sales still down 50.13% versus 24 months while September 2026 logged a 15.77% YoY gain and Flower’s share approaching parity at 46.64%, the pattern implies near-term growth will rely on sustaining Flower mix gains while stabilizing a Pre-Roll rank at 51 in Alberta to prevent further share erosion.
Competitive Landscape
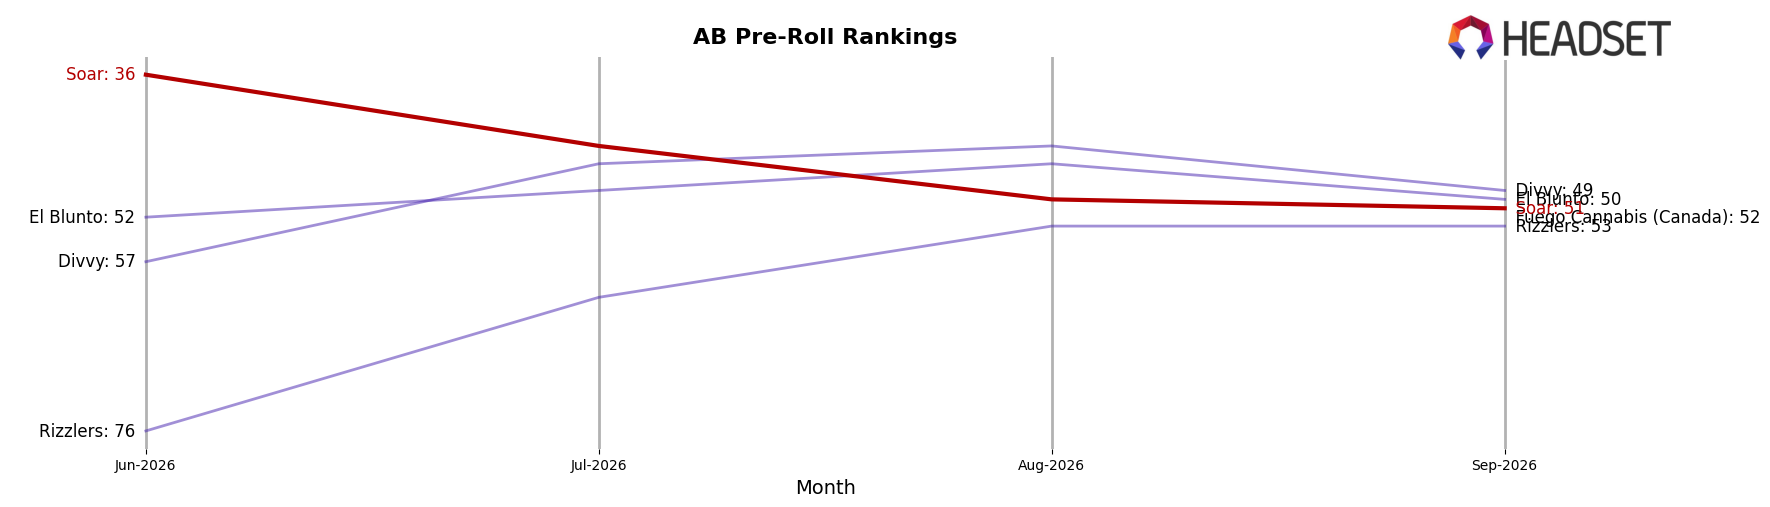
Soar sits at #51 in AB Pre-Roll for September 2026 after rising 54 positions year over year from #105, though it fell 15 places since June 2026 when it peaked at #36. Against this, Back Forty / Back 40 Cannabis advanced from #3 to #1 while growing sales 26.2% year over year, and General Admission slipped from #1 to #2 on a 27.9% year-over-year sales decline, indicating Soar’s mid-year surge to #36 did not persist into September 2026 at #51. The pattern implies Soar is gaining share versus last year but ceding short-term momentum to leaders that either climbed in rank or defended top positions, so sustaining gains will require converting its June 2026 peak at #36 into steadier placement through year-end.
Notable Products
Soar’s steepest decline came from 187 Kush Pre-Roll 3-Pack (1.5g), down 36.96% month over month and sitting at rank 3, while Brain Cake Pre-Roll 3-Pack (1.5g) fell 29.69% at rank 1. Five of the top ten are Pre-Roll SKUs, and within that group four posted double-digit MoM drops between 10.20% and 36.96%, indicating demand softness concentrated in infused and multi-pack formats. In contrast, C99 Haze (7g) in Flower rose 25.84% to rank 7 as Widow Pop (7g) edged down 4.70% at rank 6, signaling relative stability in bulk Flower versus pressure in Pre-Rolls. The mix suggests Soar is pivoting toward defending Flower-led baskets as Pre-Roll volatility erodes volume leadership, implying assortment and promo emphasis should rebalance from infused blunts toward value 7g offerings.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

