

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Summit is stocked at 63 licensed dispensaries across Colorado, Washington, and Arizona, 59 of them in Colorado, with the deepest coverage in Denver, Colorado Springs, Boulder, Pueblo West, and Grand Junction. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
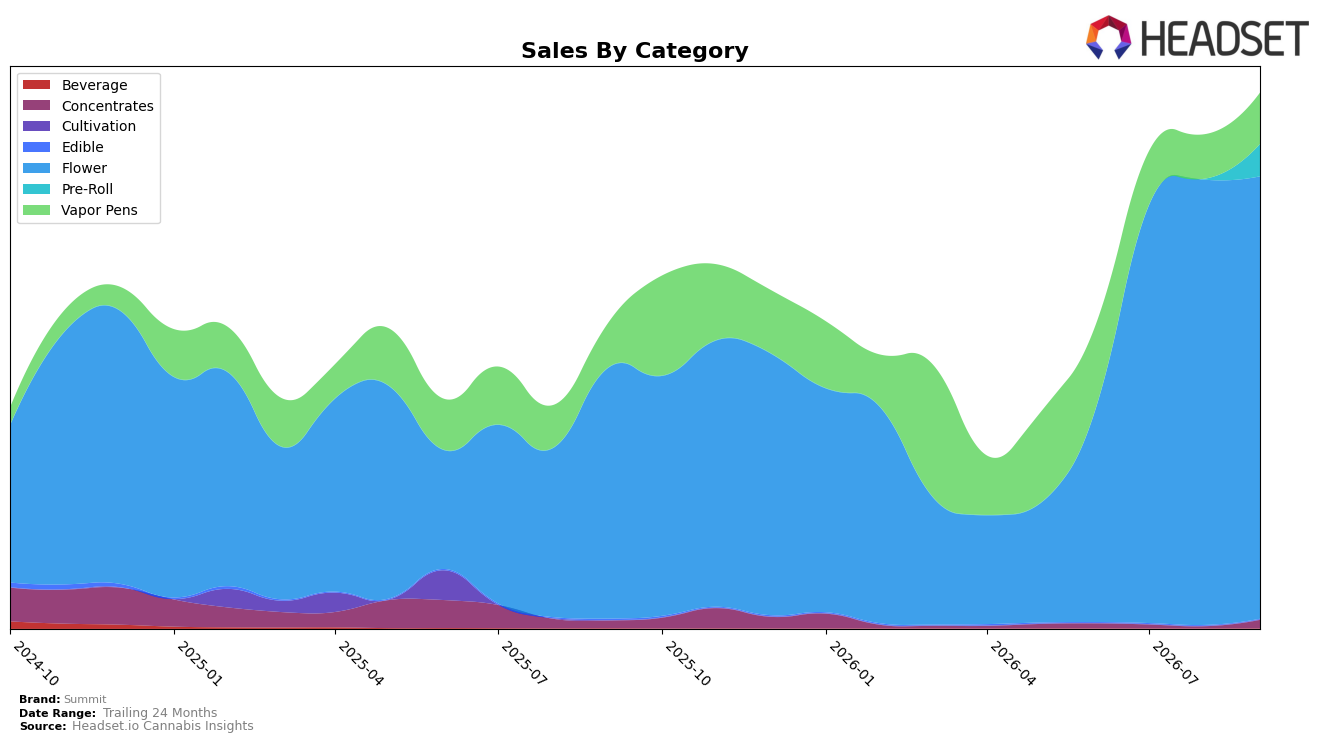
Summit concentrated 82.88% of September 2026 sales in Flower with year-over-year growth of 76.58% but a month-over-month dip of 0.65%, while Vapor Pens held 9.55% share with 14.99% YoY growth and a 15.51% MoM increase. Pre-Roll surged to 5.99% share on a 5,919.26% MoM spike, and Concentrates rose to 1.53% share with 351.98% MoM growth and 11.46% YoY growth, as Edible contracted to 0.05% share with a 73.56% YoY decline and a 33.86% MoM drop. With brand-level sales up 75.95% YoY and average price down 17.25%, the mix implies volume-led expansion centered on Flower, while emerging traction in Pre-Roll and Concentrates provides incremental breadth without yet shifting the core.
Holding rank 19 in Flower in Colorado alongside an 82.88% category concentration and a 0.65% MoM Flower dip suggests Summit’s positioning relies on defending distribution and price architecture in its primary aisle as the brand leans into lower pricing. The 15.51% MoM rise in Vapor Pens and the 351.98% MoM lift in Concentrates, paired with the 5,919.26% MoM jump in Pre-Roll, indicate targeted extensions that can mitigate risk from Flower volatility, while the 73.56% YoY pullback in Edible signals de-prioritization; taken together, the pattern implies Summit should anchor merchandising around Flower rank while intentionally scaling accessory categories to convert share without diluting the core price-volume thesis.
Competitive Landscape
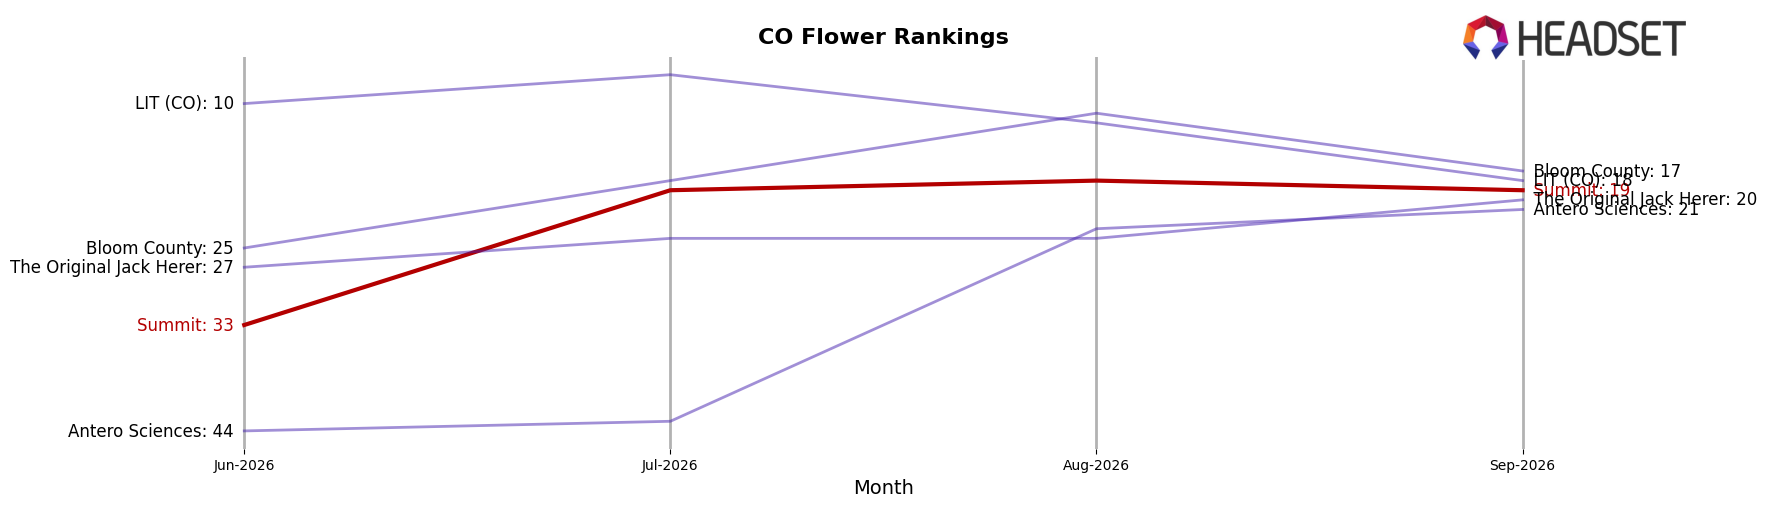
Summit sits at rank #19 in CO Flower in September 2026, improving 7 positions from #26 year over year, and tightening versus three months ago when it was #33; however, it is one spot below its August 2026 peak of #18, indicating recent momentum with a slight pullback. In directional contrast, Green Label Cannabis held #1 both year over year and in September 2026 with sales up 38%, while In The Flow advanced from #12 year over year to #5 with 114% sales growth, and Seed & Strain Cannabis Co. slid from #2 year over year to #4 with a 34% sales decline; this mix of upward and downward competitor shifts alongside Summit’s 7-rank YoY climb implies Summit is moving from the lower mid-tier toward the crowded teens, but sustaining progress will require breaking past the #18–#19 band as peers accelerate or retrench.
Notable Products
Apricot Scone Smalls (14g) posted the standout movement in September 2026 with a month-over-month rise of 67.4% while climbing to rank 6, even as category leader Platinum Cake Mints (Bulk) fell 33.0% at rank 1. Lemon Zest (Bulk) dropped 69.0% at rank 2 and Jumpman (Bulk) declined 27.3% at rank 4, whereas Grape Bubblegum (Bulk) grew 15.6% at rank 5 and Purple Garlic (Bulk) held rank 3 with no reported month-over-month figure; taken together, eight of the top ten SKUs are Flower, concentrating demand into a single category. This pattern implies Summit is tilting toward value-oriented Flower formats that can gain share despite volatility at the top end, with Smalls acting as a volume lever even when premium bulk strains contract.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

