

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
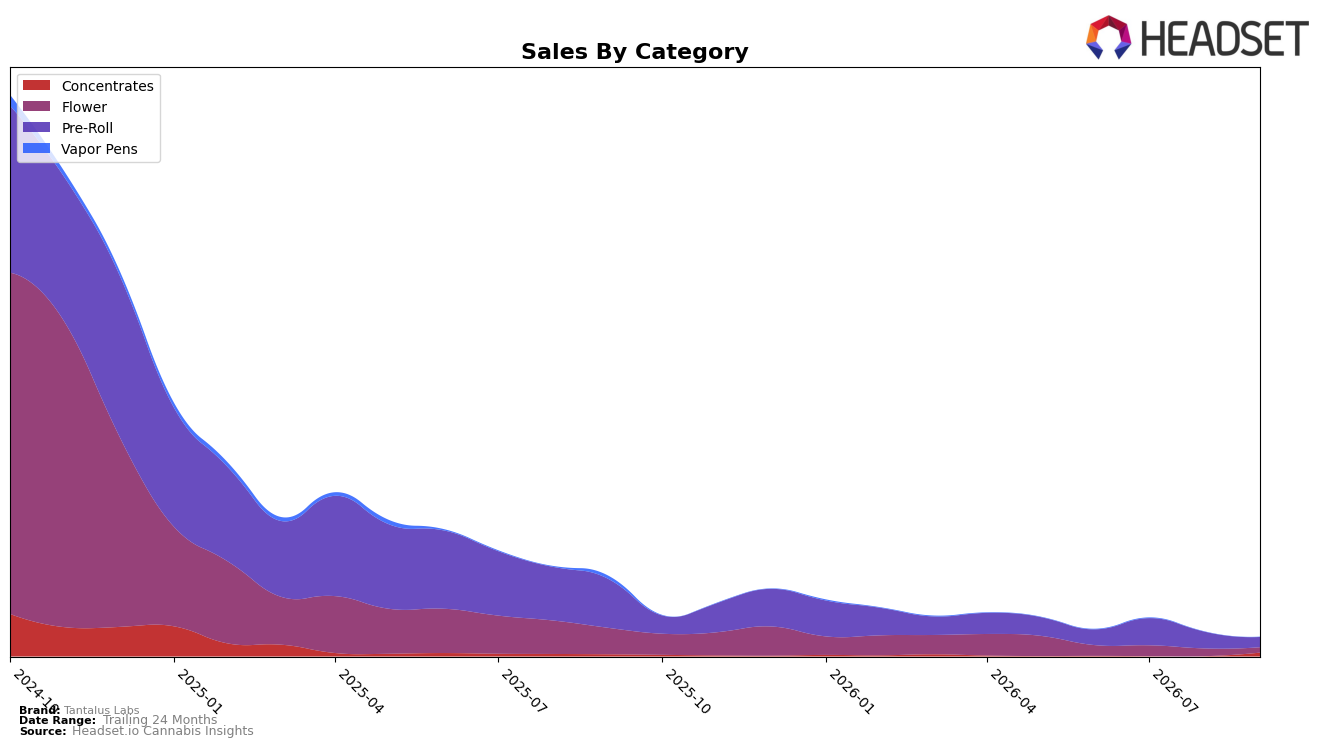
Tantalus Labs concentrated 53.41% of September 2026 sales in Pre-Roll, down 39.74% month over month and 79.63% year over year, while Flower held 27.35% share with a 31.59% MoM decline and an 80.56% YoY drop; in contrast, Concentrates reached 19.24% share with an 85.09% YoY increase and no reported MoM figure. Average price rose 4.84% YoY to $21.71 as Pre-Roll pricing sat at $14.49 and Flower at $92.01, implying mix and price dynamics that did not offset a total brand sales decline of 76.70% YoY; the pattern suggests a pivot underway from legacy Pre-Roll and Flower toward Concentrates, with British Columbia remaining the focal market absent a current Pre-Roll rank.
The simultaneous 39.74% MoM retreat in Pre-Roll share weight and 31.59% MoM contraction in Flower, alongside an 85.09% YoY surge in Concentrates to 19.24% share, points to a repositioning toward higher-velocity niches where smaller bases can still deliver growth. With category declines outpacing the modest 4.84% YoY price lift and a 96.35% two-year sales contraction, the brand is trading volume for margin in a way that compresses overall scale; the implication is that near-term competitiveness in British Columbia depends on accelerating Concentrates penetration while stabilizing Pre-Roll rank to prevent further share erosion.
Competitive Landscape
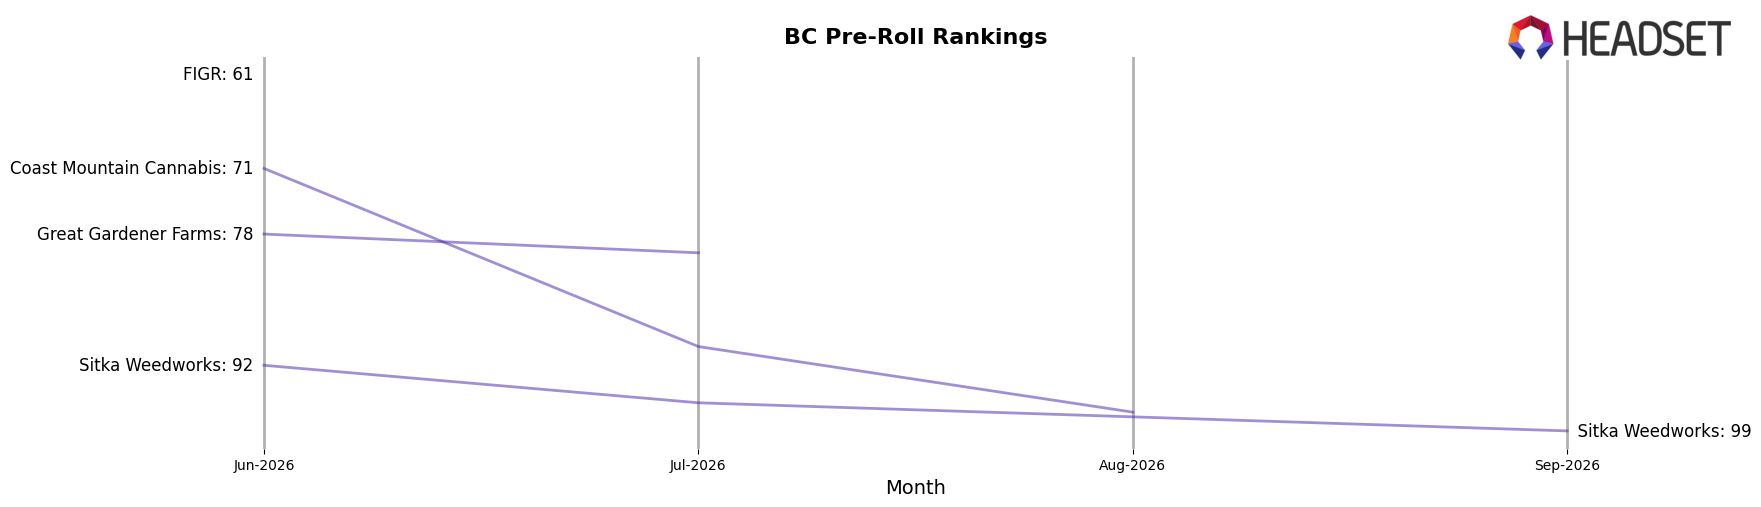
Tantalus Labs ranks at #111 in BC Pre-Roll for September 2026, down 38 positions year over year from #73, and flat versus June 2026 at #111; compared with its peak at #45 in September 2024, the brand is 66 ranks lower. Meanwhile, Weed Me moved from #2 to #1 with 28.6% year-over-year sales growth, and Back Forty / Back 40 Cannabis jumped from #13 to #2 with 197.3% year-over-year growth, indicating that Tantalus Labs lost relative position while leaders advanced. This trajectory implies the brand’s current assortment or activation is not converting in a category where top competitors are accelerating, and regaining share will require reversing the year-over-year rank decline while countering rapid gains at the top of the leaderboard.
Notable Products
Sunset Sherbert (3.5g) posted the steepest decline in September 2026 at -58.9% MoM while dropping to rank 6, and Sky Pilot (14g) also fell -26.8% to rank 4. More Cowbell Pre-Roll 3-Pack (1.5g) held rank 1 despite a -41.7% MoM slide, whereas Pacific OG Pre-Roll 3-Pack (1.5g) inched up just +1.1% at rank 3. With two Pre-Rolls in the top three and Flower SKUs occupying ranks 4–6 with double‑digit declines, the pattern implies a tilt toward smaller-format inhalables and a need to rethink large-flower positioning as demand concentrates in value-driven pre-rolls.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

