

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
The Heirloom Collective is stocked at 76 licensed dispensaries across Massachusetts, with the deepest coverage in Quincy, Boston, Fall River, Lowell, and Pittsfield. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
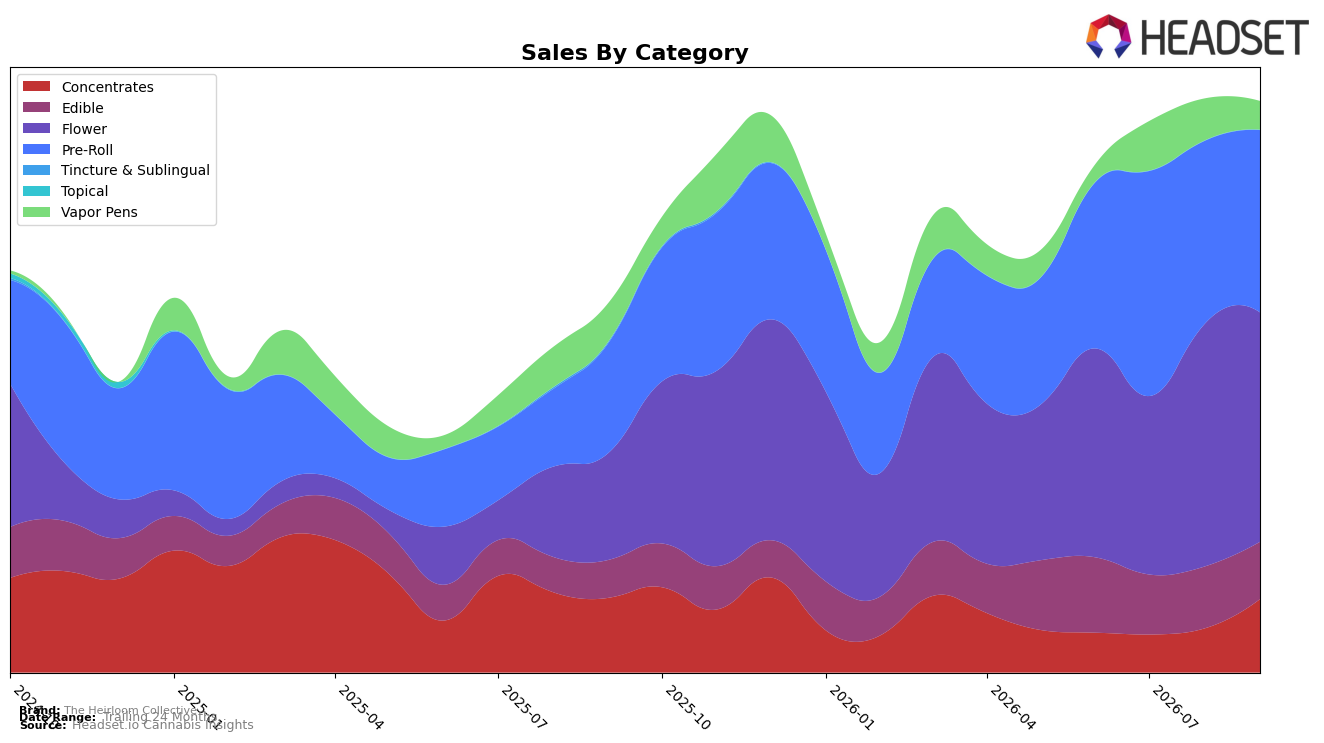
The Heirloom Collective’s category mix in September 2026 tilted toward Flower at 40.21% share with 114.99% year-over-year growth but a -5.42% month-over-month dip, while Pre-Roll held 31.94% share with 66.04% YoY growth and a softer -0.40% MoM slip; together these two categories account for 72.15% of sales, indicating concentration in inhalables despite mixed monthly momentum. Secondary categories moved in opposite directions: Concentrates rose 66.47% MoM but fell -1.70% YoY at 12.85% share, whereas Edible gained 51.56% YoY but slid -7.43% MoM at 10.01% share, and Vapor Pens contracted both -25.94% YoY and -31.96% MoM at 4.99% share. With brand-level sales up 54.94% YoY and average price down -9.80%, the pattern implies volume-driven gains concentrated in Flower and Pre-Roll, offset by a steep pullback in Vapor Pens and a tactical push into Concentrates month-over-month.
These shifts imply the brand is leaning into lower-price-per-unit, high-velocity formats to expand reach, as seen in Pre-Roll at a $6.51 average price and Flower’s price point of $18.72, while retreating from Vapor Pens at $33.44 where both YoY and MoM declines suggest weaker pull. The 66.47% MoM surge in Concentrates alongside a -1.70% YoY suggests near-term promotional or distribution expansion rather than a structural mix pivot, and the -7.43% MoM in Edible despite 51.56% YoY growth points to episodic demand rather than sustained share capture. In Massachusetts Flower, a rank of 49 combined with 114.99% YoY growth and a -5.42% MoM signals that mix-led volume can lift annual trajectory without materially improving monthly rank position, implying the brand’s positioning is anchored in value-accessible inhalables that drive traffic but require further differentiation to climb category rankings.
Competitive Landscape
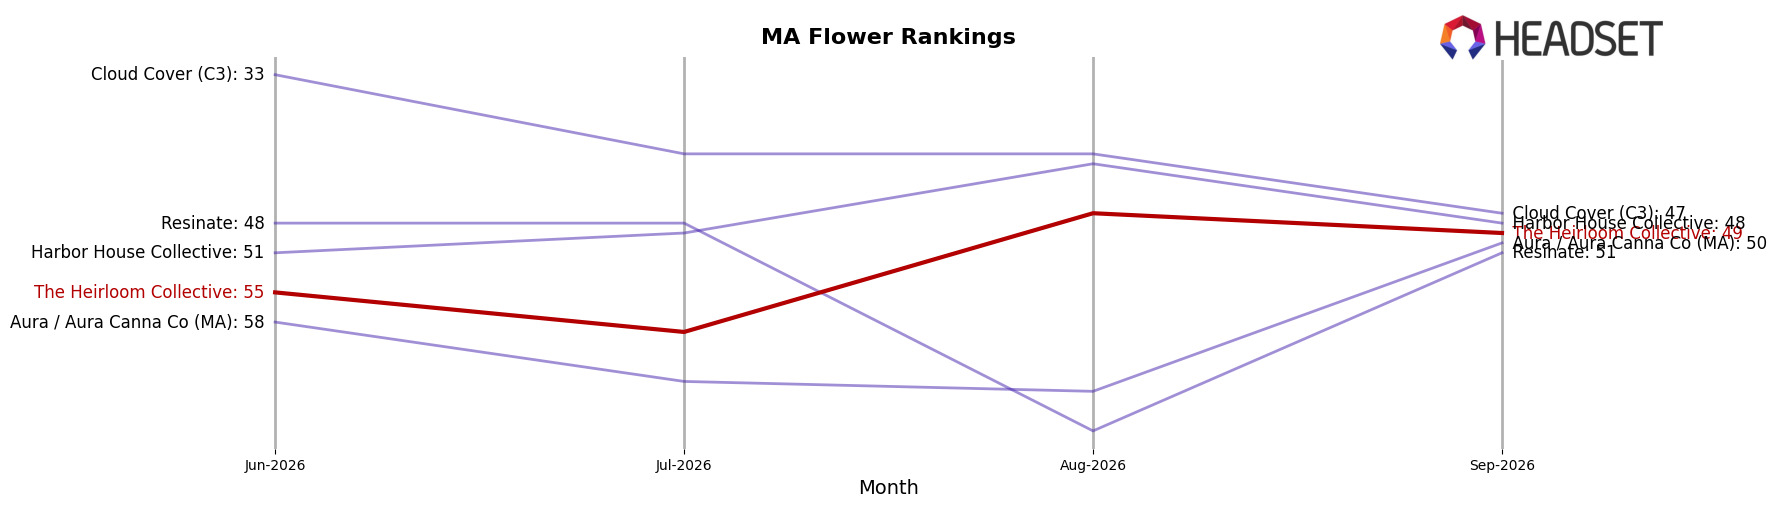
The Heirloom Collective sits at rank #49 in Massachusetts Flower for September 2026 after rising 36 spots year over year from #85, and it has improved 6 positions since June 2026 when it was #55. The brand briefly peaked at #47 in August 2026 before slipping 2 ranks month over month, while Perpetual Harvest advanced from #4 to #1 with 124.1% year-over-year sales growth and Farmer's Cut held near the top at #2 with a 37.5% year-over-year lift. Against top-three brands like Simply Herb sliding from #1 to #3 amid a 16.6% year-over-year sales decline and High Supply / Supply easing from #3 to #4 with a 13.6% drop, The Heirloom Collective’s climb from #85 to #49 alongside a near-peak at #47 implies the brand is regaining distribution or velocity faster than mid-pack peers but must convert the late-summer uptick into sustained share to avoid oscillating around the high-40s.
Notable Products
Cheezy Kush Pre-Roll (1g) posted the largest month-over-month surge at +117.2%, while Grandpa's Stash Pre-Roll (1g) followed with +76.9% and climbed to rank 2, signaling a pivot in momentum toward value-driven inhalables. Kitchen Sink (3.5g) fell -14.5% to rank 6 and Kitchen Sink Pre-Roll (1g) slipped -9.8% while still holding rank 1, indicating the flagship family is yielding share to faster-rising SKUs. Four of the top ten are Pre-Roll SKUs, including positions 1–4 and 10, and Pre-Roll gains outpaced Edibles at +5.6% for Sour Blueberry Cube Gummies 20-Pack (100mg), concentrating demand at the top of the lineup. The pattern implies The Heirloom Collective is leaning into a Pre-Roll-led mix that prioritizes rapid-turn items over premium Flower, likely reallocating assortment and promo weight toward quick-velocity SKUs.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

