
Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Is this your brand?
See your full sales and distribution data: where you sell, how you're priced, and how you rank against the brands next to you on the shelf.
See your brand's dataCarry this brand in your store?
Headset Retailer is free. Connect your POS and see what's selling and what's sitting.
Sign up freeWhere to Buy
Too Loud (MD) is stocked at 60 licensed dispensaries across Maryland, with the deepest coverage in Baltimore, Annapolis, Frederick, Hagerstown, and Silver Spring. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
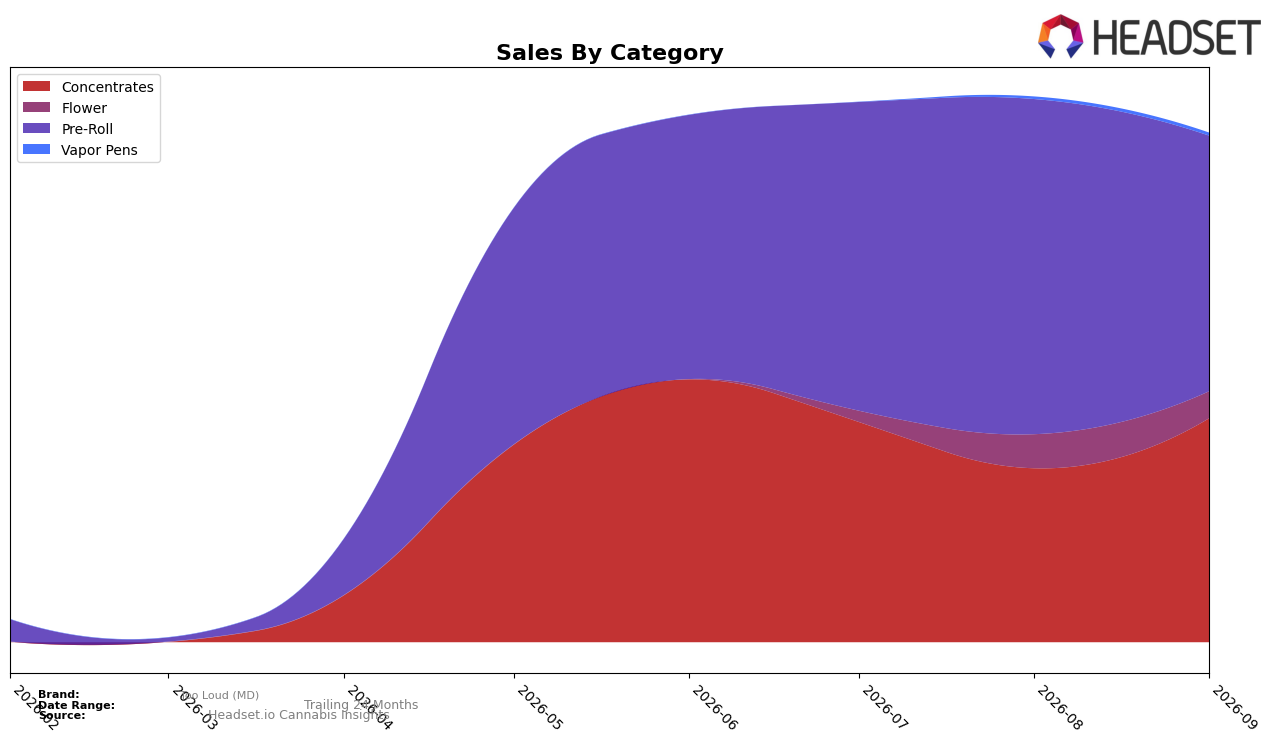
Too Loud (MD) concentrated sales in Pre-Roll at 50.19% share with a month-over-month decline of 23.82%, while Concentrates reached 44.02% share on a 28.86% month-over-month increase. Secondary categories diverged: Flower held 5.25% share with a 20.91% month-over-month drop, and Vapor Pens, at 0.55% share, rose 21.40% month-over-month. With Pre-Roll leading but shrinking and Concentrates nearly matching its scale, the September 2026 mix in Maryland implies a pivot from a single-category anchor toward a two-pillar portfolio where volatility in Pre-Roll is being offset by momentum in Concentrates.
Positioning-wise, a Pre-Roll category rank of 21 in Maryland alongside a 23.82% month-over-month Pre-Roll decline and a 28.86% month-over-month rise in Concentrates suggests Too Loud (MD) is ceding ranking headroom in its lead lane while building relevance in a faster-moving adjacent. The 5.25% share in Flower paired with a 20.91% month-over-month contraction and the 0.55% Vapor Pens share despite a 21.40% lift indicate limited traction in tertiary formats; this pattern implies the brand’s near-term differentiation will depend on sustaining Concentrates growth to balance Pre-Roll softness rather than broadening into lower-share categories.
Competitive Landscape
Too Loud (MD) sits at rank #21 in MD Pre-Roll for September 2026, improving 1 position from June 2026’s #22, while its peak at #19 in August 2026 marks a 2-rank slip month over month into September and a 1-rank gain quarter over quarter; in directional contrast, SunMed holds #1 with a 30.99% year-over-year sales increase and Strane advanced to #2 from #8 year over year alongside 106.38% sales growth, indicating Too Loud (MD) is orbiting the top-20 fringe while faster-moving leaders are widening the competitive gap, implying that without near-term share capture its rank trajectory is likely to stabilize below prior peak rather than re-enter the teens.

Notable Products
Orange Pop Star Shatter (1g) delivered the standout movement in September 2026 with a +91.1% month-over-month surge to rank 2, while Citrus Harmony Infused Pre-Roll 2-Pack (1g) plunged -68.7% to rank 10, indicating volatility polarized between Concentrates gains and Pre-Roll losses. Mic Check Infused Pre-Roll 2-Pack (1g) held rank 1 despite a -2.9% dip, contrasted by Island Drum Infused Pre-Roll 5-Pack (2.5g) falling -23.7% to rank 7, and Orange Pop Star Infused Pre-Roll 2-Pack (1g) rising +20.8% to rank 6, signaling product-family divergence within infused formats. With four of the top ten being Pre-Roll SKUs but two posting double-digit declines and one Flower SKU at rank 8 down -20.9%, the center of gravity is shifting toward Concentrates where momentum is outsized. The pattern implies Too Loud (MD) is leaning into shatter-driven velocity to offset softening in larger-pack infused formats, which points to near-term mix optimization favoring smaller, high-uptake Concentrates over bulk Pre-Roll configurations.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

