

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
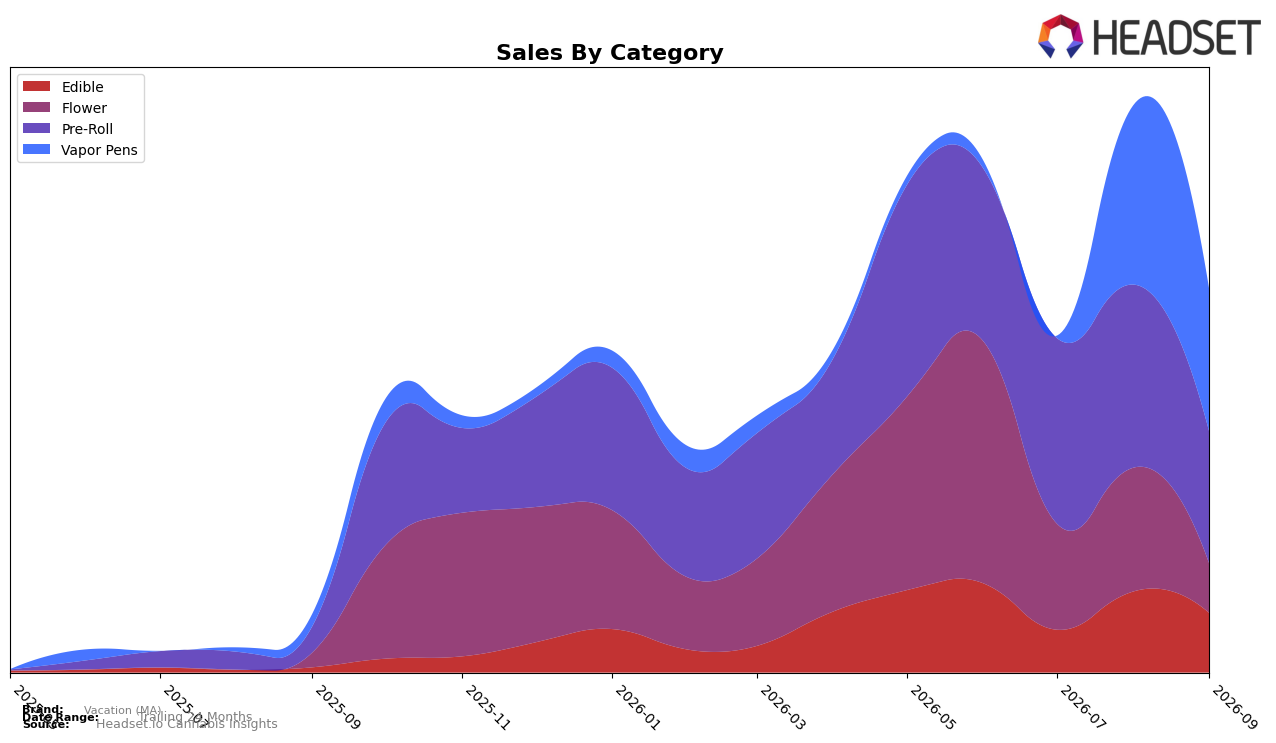
Vacation (MA) concentrated 37.18% of September 2026 sales in Vapor Pens and 34.47% in Pre-Roll, with Edible at 15.55% and Flower at 12.80%, indicating a two-category core. Year over year, Vapor Pens expanded 1,052.69% and Edible rose 1,070.05%, while Pre-Roll advanced 405.21% and Flower gained 235.31%, but month over month all four contracted, with Flower down 60.46% and Pre-Roll down 28.12%. The month’s pullback in Vapor Pens at -20.74% and Edible at -26.64%, alongside a -28.11% Pre-Roll dip, points to recent volatility layered on top of outsized annual growth, implying the mix is skewing toward inhalables but under pressure from short-term demand or inventory normalization in Massachusetts.
The mix and price dynamics suggest repositioning around value-forward inhalables: average price fell 28.11% year over year to $17.60 while Vapor Pens, with a $21.93 average price, now lead share at 37.18% and hold a state-category rank of 81, and Pre-Roll at a $14.54 average supports 34.47% share. The simultaneous 1,070.05% Edible growth and 1,052.69% Vapor Pens growth, contrasted with month-over-month declines of 26.64% and 20.74% respectively, indicate that the brand’s demand elasticity may be heightened, with shoppers trading into lower-price formats during pullbacks and away from Flower, which slid 60.46% MoM despite 235.31% YoY. This pattern implies Vacation (MA) is carving out a price-accessible, inhalable-led stance in Massachusetts, where sustaining share will hinge on stabilizing Vapor Pens momentum while using Edible as a counter-cyclical buffer.
Competitive Landscape
Vacation (MA) sits at rank #81 in Massachusetts Vapor Pens for September 2026, a 70-place climb from #151 year over year and a 75-place improvement from #156 three months ago; however, the brand remains 11 spots below its recent peak of #70 in August 2026 and 80 positions behind category leader Fernway (#1), while Jeeter surged from #23 to #4 as its sales grew 421.5% year over year and Dime Industries moved from #6 to #5 with 63.0% YoY growth; this pattern implies Vacation (MA)’s rank recovery is real but modest relative to top-tier momentum, suggesting the current trajectory requires acceleration to convert mid-tier gains into durable top-50 presence.

Notable Products
Orange Apricot x Tropic Thunder Distillate Cartridge (1g) posted the steepest decline at -55.98% MoM and sat at rank 8, while Jelly Rancher Distillate Cartridge (1g) fell -30.71% to rank 7, indicating sharp pressure within mid-table Vapor Pens. Super Sour Diesel Distillate Cartridge (1g) also contracted -25.93% at rank 3 against a contrasting +49.61% MoM surge for Super Boof Distillate Cartridge (1g) at rank 2, with Super Boof contributing $15,055 in September 2026. With six of the top ten coming from Vapor Pens alongside three Pre-Roll SKUs including rank-1 ShipWreck Pre-Roll 2-Pack (1g), the mix tilts toward volatility in cartridges but relative stability at the top, implying Vacation (MA) is leaning into a two-tier portfolio where pre-rolls anchor rank while selective pen SKUs drive swing capacity.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

