


Market Insights Snapshot
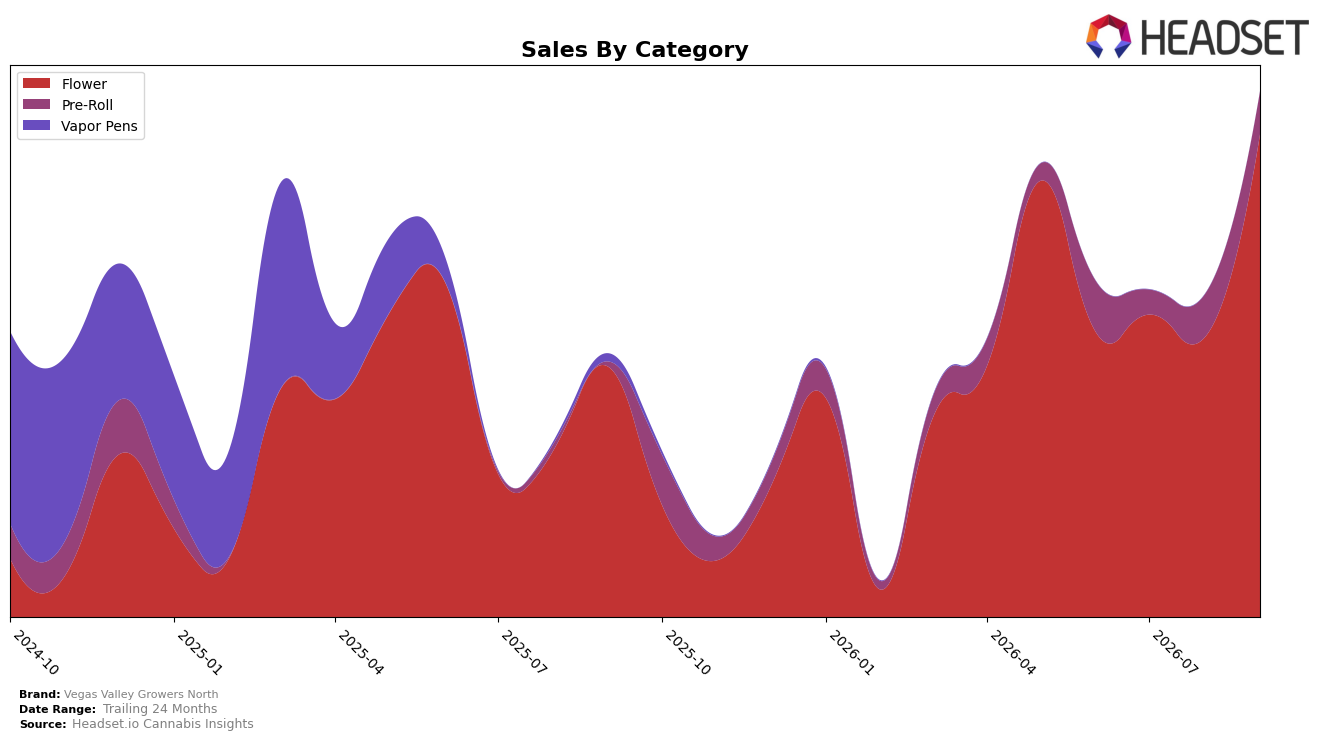
Flower accounted for 91.91% share in September 2026 with year-over-year sales up 92.87% and month-over-month up 72.72%, while Pre-Roll held 8.09% share with a 778.28% year-over-year surge but a 0.23% month-over-month decline. Average price fell 47.21% year over year to $20.98 as category weights tilted toward lower-priced Flower SKUs and value-focused Pre-Rolls, and Vegas Valley Growers North’s overall sales grew 99.77% year over year alongside a 32.26% gain over 24 months. In Nevada Flower, the brand sat at rank 37, and the combination of a 72.72% month-over-month Flower lift and a 0.23% month-over-month dip in Pre-Roll implies September 2026 growth depended on Flower velocity more than incremental category breadth.
The mix shift — 91.91% of sales in Flower with rank 37 in Nevada and an 8.09% Pre-Roll slice growing 778.28% year over year — points to a scale-through-volume posture where price elasticity is converting into share within Flower faster than it is building a second pillar in Pre-Roll. With average price down 47.21% year over year and Flower up 72.72% month over month versus a 0.23% month-over-month contraction in Pre-Roll, the brand is trading depth in its lead category for speed, which supports near-term rank stability in Flower but leaves category diversification underweighted for resilience.
Competitive Landscape
Vegas Valley Growers North sits at rank #37 in NV Flower for September 2026, improving 26 positions from #63 year over year, and tightening further from #57 just three months prior; this rise coincides with a climb to its peak rank of #37 while category leaders like RYTHM hold #1 with a 19.7% YoY sales increase and STIIIZY remains #2 with 24.2% YoY growth, indicating that Vegas Valley Growers North advanced ranks despite competitors expanding faster in sales percentage terms. With Alternative Medicine Association / AMA moving from #5 to #3 and Neon Moon jumping from #9 to #4 alongside an 82.7% YoY lift, Vegas Valley Growers North’s 26-rank YoY ascent and 20-rank gain since June 2026 imply a momentum phase primarily driven by rank efficiency rather than outsized share capture, signaling a need to convert position gains into sustained share before leaders widen the gap.

Notable Products
Pineapple Chunk (3.5g) delivered the standout movement in September 2026 with a 414% month-over-month surge that vaulted it to rank 4, while Las Vegas Lemon Pre-Roll (1g) fell 55% MoM and slid to rank 9, indicating volatility at the format level. Flower dominated breadth with six of the top ten SKUs in September 2026, and within that set Crunch Berry (3.5g) climbed 89% MoM to rank 2 as Pineapple Chunk Pre-Roll (1g) jumped 108% MoM to rank 1, signaling that strain-led demand is spilling across both flower and pre-rolls. The concentration in Flower, alongside dual-format gains for Pineapple Chunk and a retreat for one pre-roll, implies a pivot toward strain equity anchoring the lineup while trimming underperforming single-stick bets.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

