

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
22Red is stocked at 56 licensed dispensaries across Arizona, with the deepest coverage in Tucson, Phoenix, Mesa, Tempe, and Chandler. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
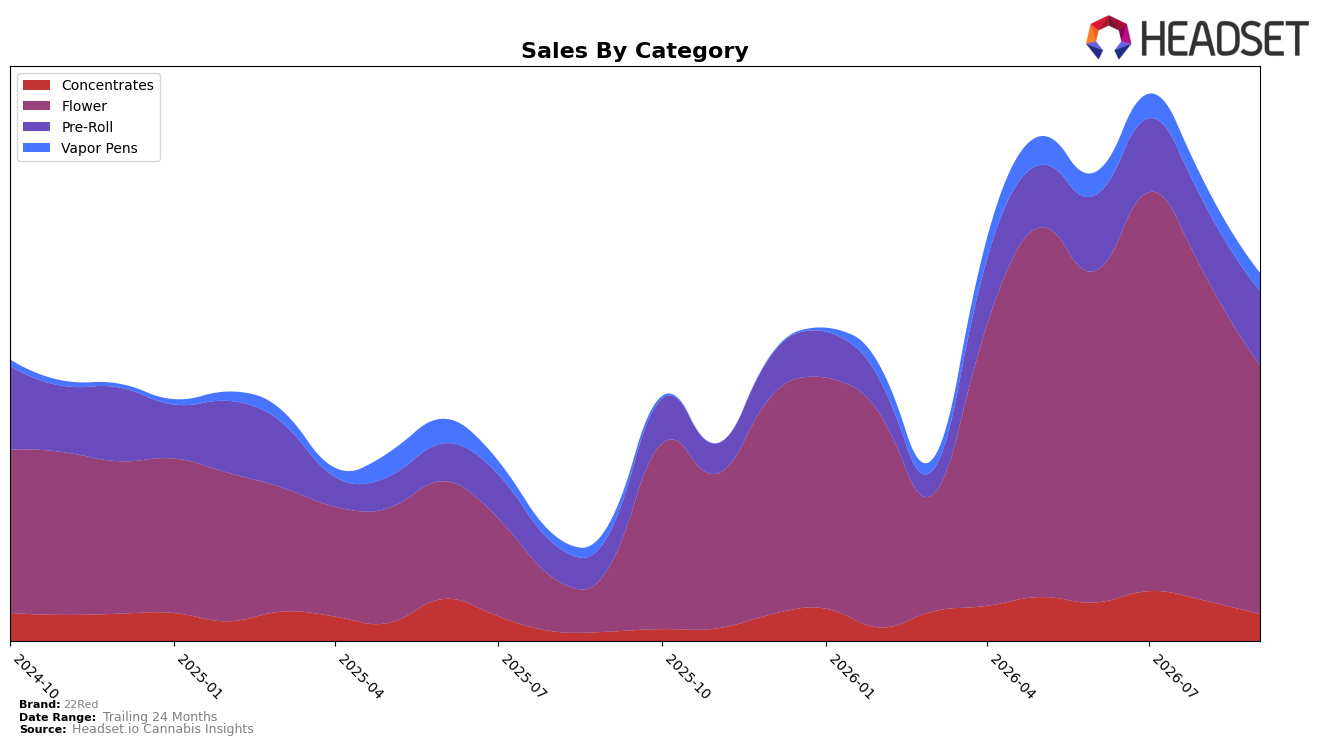
In September 2026, 22Red concentrated 67.36% of sales in Flower, where year-over-year growth hit 292.26% even as month-over-month volume contracted by 23.61%; this mix sits alongside Pre-Rolls at 20.08% share with 120.96% YoY and 5.27% MoM growth. Vapor Pens held 5.03% share with 76.99% YoY but a 13.99% MoM drop, while Concentrates represented 7.53% share with 175.65% YoY but a 32.39% MoM decline; combined with a 5.67% YoY increase in average price and brand-level sales up 214.13% YoY, the mix indicates expansion led by Flower despite shorter-term pullbacks. With Flower ranked 11 in Arizona and the brand’s top market also being Arizona, the pattern implies 22Red is leaning into high-velocity Flower while allowing cyclical MoM softness to be offset by category breadth and price resilience.
The divergence between double- and triple-digit YoY gains in Flower (292.26%) and Pre-Rolls (120.96%) versus MoM contraction in Flower (-23.61%) and Concentrates (-32.39%) signals a recalibration window where inventory and promotions likely shifted toward maintaining Pre-Roll momentum (+5.27% MoM) while protecting margin via a 5.67% YoY average price lift. With Vapor Pens at 5.03% share and -13.99% MoM, and Concentrates at 7.53% share and -32.39% MoM, the brand’s positioning tilts toward core inhalables with Flower dominance backed by a stabilizing Pre-Roll second pillar; the implication is that sustaining the 11th rank in Arizona Flower will depend on converting Pre-Roll MoM gains into repeat baskets and smoothing Flower’s month-to-month variability without diluting the category’s 67.36% mix weight.
Competitive Landscape
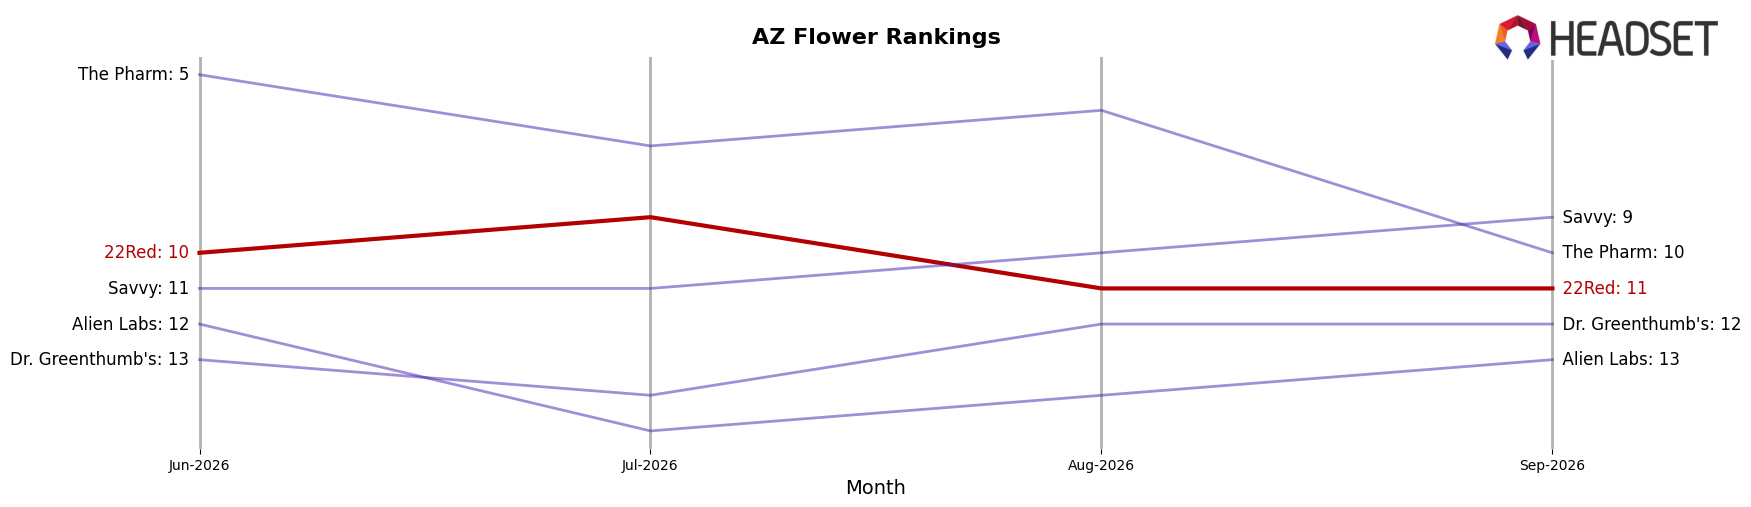
22Red sits at rank #11 in AZ Flower for September 2026, an improvement of 28 positions from #39 in September 2025, while slipping 1 spot from #10 in June 2026 and down 3 from its peak at #8 in May 2026; meanwhile, Just Flower held at #1 year over year and Loud Pax vaulted from #51 to #5 as its sales expanded by 2,181.5%, indicating competitors are consolidating share faster at the top tiers. With Find. moving from #3 to #2 alongside a 56.6% year-over-year sales increase and Mohave Cannabis Co. easing from #2 to #3 despite 6.0% year-over-year growth, 22Red’s year-over-year climb of 28 ranks alongside a quarter-over-quarter dip of 1 place points to momentum that is moderating as it encounters a faster-rising competitive set, implying the brand must convert its mid-year peak into sustained share gains to avoid getting pinned below the top 10.
Notable Products
Gelato 41 Pre-Roll (1g) posted the steepest shift in September 2026 with a -59.4% month-over-month change, sliding to rank 6 while Strawberry Z Pre-Roll (1g) fell -9.3% at rank 2 and Mr. Jack Pre-Roll (1g) declined -12.7% at rank 5. Four of the top ten are Pre-Roll SKUs clustered at ranks 1–3 and 5–6, yet the Flower lineup split directions as BCC x Jealousy (14g) rose +26.1% to rank 4 while BCC x Jealousy (3.5g) dropped -18.6% to rank 7, indicating size-tier cannibalization within the same strain. This mix, with Pre-Rolls concentrated at the top but a large-format Flower pack gaining share, implies 22Red is tilting toward value-driven formats while smaller-pack Flower and select Pre-Rolls lose momentum.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

