

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Asteroid Cannabis is stocked at 52 licensed dispensaries across Connecticut and Missouri, 34 of them in Connecticut, with the deepest coverage in Danbury, Norwalk, Stratford, Branford, and Canton. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
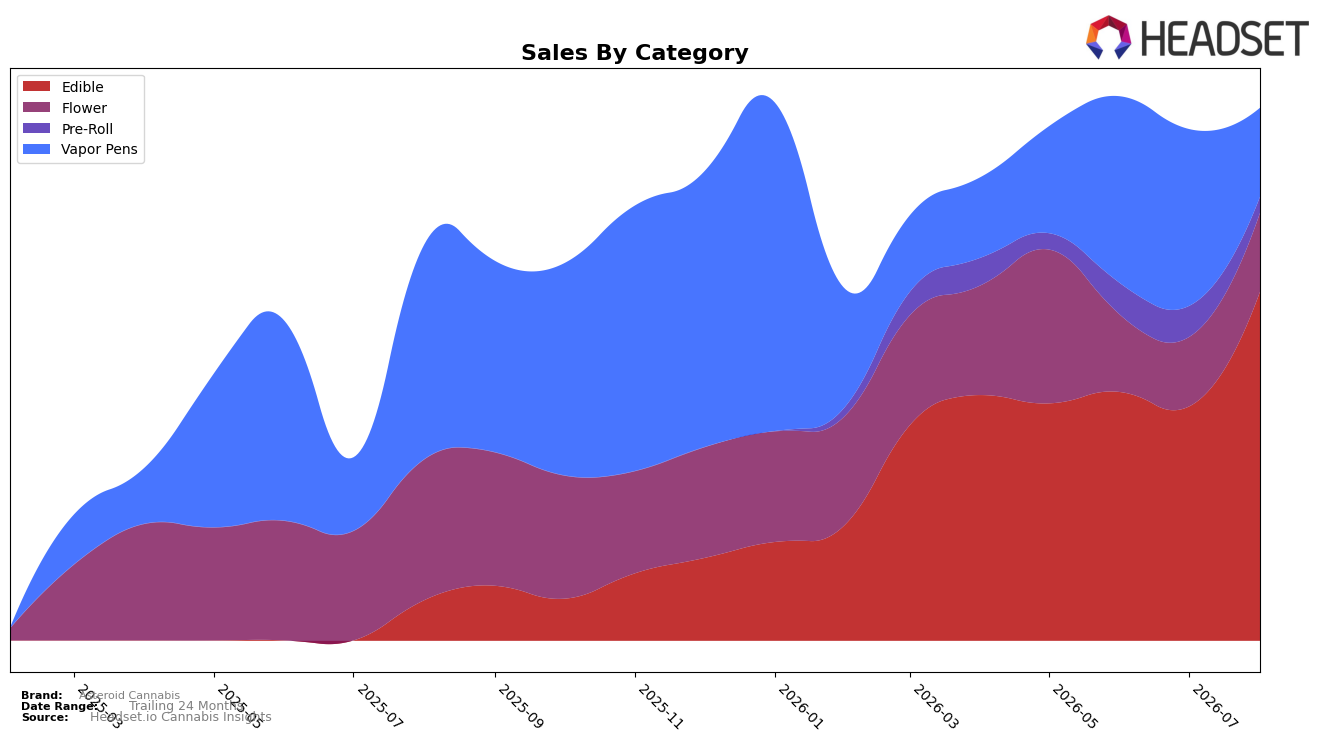
In August 2026, Asteroid Cannabis concentrated 65.59% of sales in Edible, up 763.82% year over year and 49.02% month over month, while Vapor Pens fell to 16.68% share with a -58.66% YoY decline and a -49.79% MoM drop. Flower held 14.77% share with a -44.08% YoY change but a 13.63% MoM lift, and Pre-Roll slipped to 2.97% share with a -48.64% MoM move and no prior-year comp. Average price fell 43.05% YoY to $19.41 as Edible pricing sat at 16.44 and Vapor Pens at 44.17, and the brand’s overall sales rose 34.53% YoY; the mix shift toward lower-priced Edible with triple-digit YoY growth and a top-five Connecticut Edible rank of 5 implies the brand is trading volume for share within Edible while de-emphasizing higher-ticket inhalables.
The Edible-heavy mix alongside a 49.02% MoM Edible surge and a -49.79% MoM Vapor Pens contraction indicates portfolio repositioning toward value-accessible formats, with Flower’s 13.63% MoM increase cushioning inhalable losses but not offsetting the -44.08% YoY drag. With Edible at 65.59% share and Vapor Pens plus Pre-Roll combining for only 19.65% amid double-digit MoM declines, the August 2026 profile suggests Asteroid Cannabis is anchoring competitive positioning around affordable, repeatable Edible purchases in Connecticut, using price elasticity (average price -43.05% YoY) to accelerate category penetration while accepting reduced presence in premium-priced inhalables.
Competitive Landscape
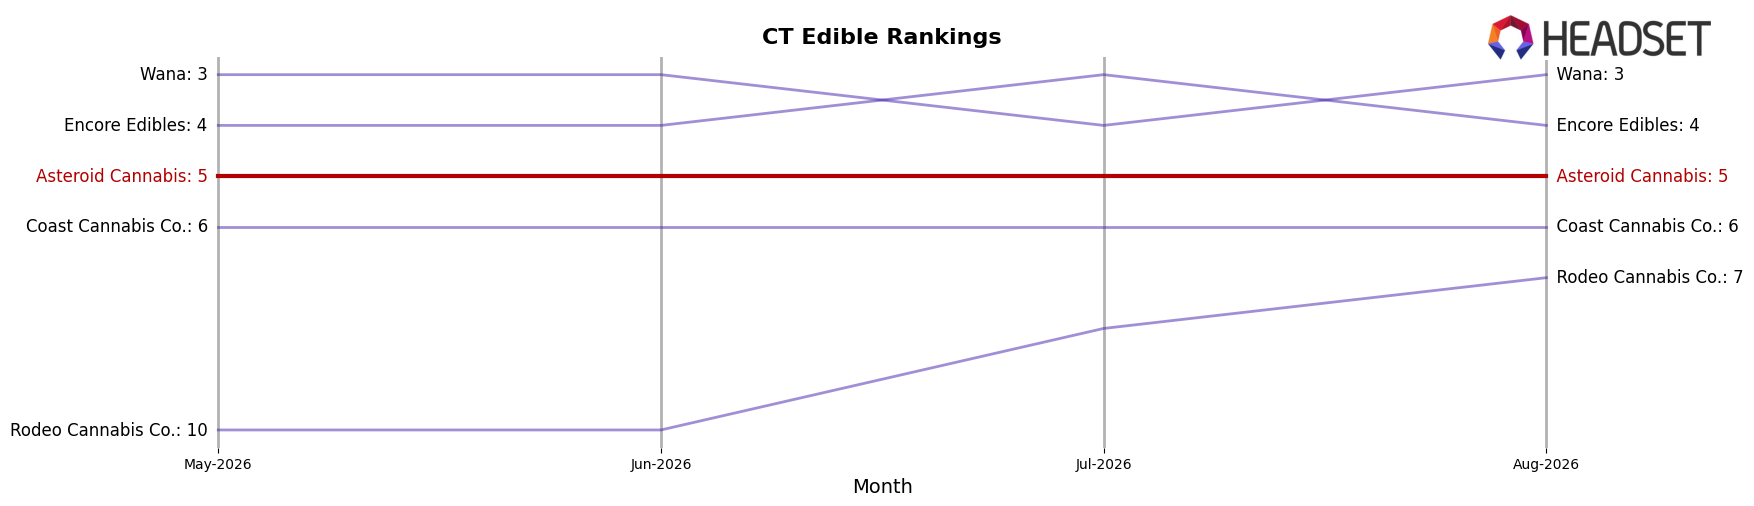
Asteroid Cannabis sits at rank #5 in CT Edible in August 2026, improving 8 positions year over year from #13, and matching its three-month rank of #5; this climb coincides with Soundview advancing from #2 to #1 while logging a 4.1% YoY sales increase, and Encore Edibles sliding from #1 to #4 on a -56.5% YoY sales decline. With Wana holding at #3 alongside a 21.8% YoY sales lift and Camino rising from #4 to #2 on 149.8% YoY growth, Asteroid Cannabis’s ascent to its peak rank of #5 in August 2026 implies it is consolidating a second-tier position while competitors reshuffle above and below it.
Notable Products
Galaxeats - Sour Green Apple Gummies 20-Pack (100mg) posted the largest movement with a 215.6% month-over-month jump to rank 4, while Pineapple Skunk Distillate Disposable (1g) fell 11.7% to rank 8, signaling a tilt toward edibles over inhalables. Galaxeats - Pink Lemonade Gummies 20-Pack (100mg) surged 80.6% to rank 2 as Galaxeats - Blueberry Bliss Gummies 20-Pack (100mg) grew 33.3% while holding rank 1, and five of the top six SKUs are Edible products, concentrating share in a single category. Black Hole Gum Infused Pre-Ground (3.5g) declined 36.8% at rank 9 even as Raspberry Rush Gummies 10-Pack (100mg) rose 40.6% at rank 3, creating a split where Flower underperforms as Edible velocity accelerates. The mix implies Asteroid Cannabis is consolidating demand around Galaxeats gummies and should prioritize Edible assortment depth over Flower and Vapor Pens despite a single SKU in Vapor Pens still generating $62,629.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

