
Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Billo is stocked at 45 licensed dispensaries across Colorado, with the deepest coverage in Colorado Springs, Grand Junction, Denver, Sedgwick, and Aurora. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
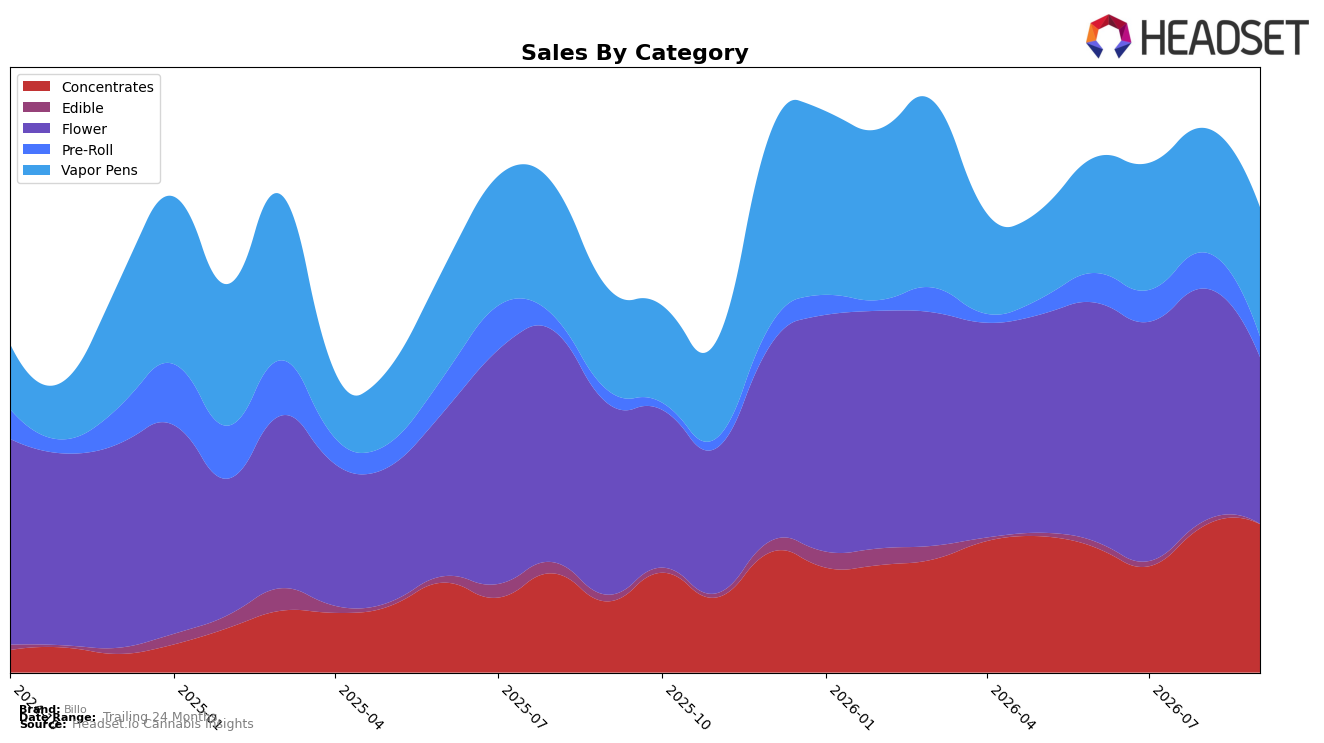
In September 2026, Billo’s mix pivoted toward higher-growth inhalables: Concentrates climbed to 30.9% share with 96.99% year-over-year growth and 0.93% month-over-month, while Vapor Pens reached 27.13% share with 24.51% year-over-year and 3.62% month-over-month. Meanwhile, Flower remained the largest slice at 34.54% share but contracted by 12.07% year-over-year and 27.17% month-over-month, and Pre-Roll fell 34.79% month-over-month despite 34.56% year-over-year growth to 5.72% share; Edible shrank to 1.70% share with a 42.77% year-over-year and 34.86% month-over-month decline. With overall brand sales up 19.08% year-over-year and the average price up 4.98% to $20.80, the mix indicates a shift away from Flower drag toward Concentrates and Vapor Pens as the primary engines of growth, implying Billo is leaning into categories where price tolerance and velocity offset the Flower downturn.
The category tilt has positioning implications: heavier exposure to Concentrates (up 96.99% year-over-year) and Vapor Pens (up 24.51% year-over-year) increases differentiation from value-oriented Flower, where a 27.17% month-over-month decline pressures shelf presence, while Pre-Roll volatility (down 34.79% month-over-month) limits entry-price traffic. Holding a 24th rank in Flower in Colorado while Flower share sits at 34.54% suggests Billo can de-emphasize lower-ranked Flower to protect margin and prioritize inhalable subsegments where small month-over-month gains of 0.93% and 3.62% compound into sustained share capture. Net, the mix implies Billo’s near-term positioning benefits from reallocating assortment and marketing toward Concentrates and Vapor Pens to stabilize month-over-month momentum and reduce sensitivity to Flower’s rank-bound ceiling.
Competitive Landscape
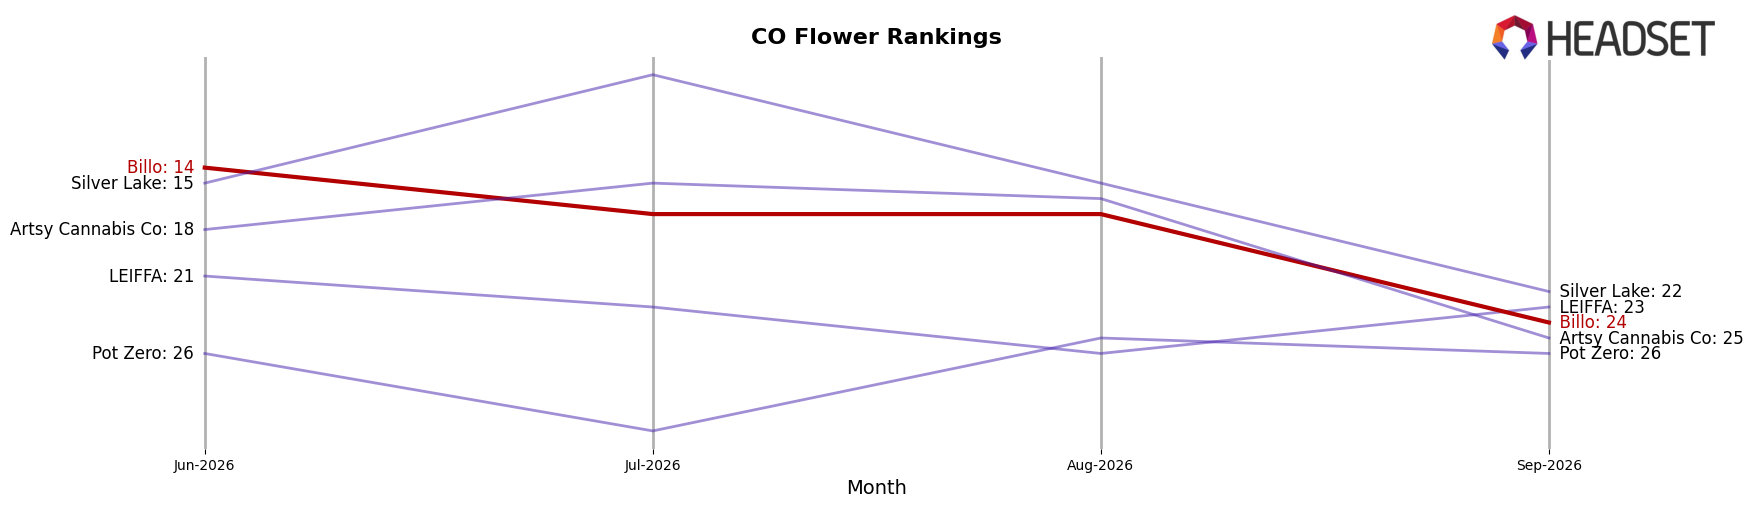
Billo sits at rank #24 in Colorado Flower in September 2026, down 8 positions year over year from #16, and 10 places below its three-month position of #14, while its peak of #9 in January 2026 underscores a longer slide from top-10 visibility. In contrast, Green Label Cannabis held #1 year over year at #1 with 38.0% YoY sales growth, and In The Flow advanced from #12 to #5 alongside 113.5% YoY sales growth, indicating share consolidation among leaders as Billo ceded 8 ranks YoY. The pattern implies Billo’s declining rank momentum—from #9 in January 2026 to #24 in September 2026—signals lost relative velocity that will likely persist unless it counters gains from rising incumbents and climbers.
Notable Products
Lilac Diesel Pre-Roll (0.75g) posted the steepest movement in September 2026 with a -63.1% MoM drop while holding rank 3, signaling acute volatility in a core format as Pre-Rolls occupy four of the top ten slots. Deep Fried S'mores Live Nectar Disposable (1g) slid -10.9% MoM at rank 2, narrowing the gap to rank 1 and indicating Vapor Pens are ceding momentum to value-leaning Pre-Rolls despite the latter’s mixed performance. Slurri Crasher Pre-Roll (0.75g) led the board at rank 1 with no reported MoM rate and $11,976 in sales, reinforcing category concentration even as one flagship falls and another leads. Together, the mix implies Billo is tilting toward Pre-Rolls for share defense while premium inhalables lose pace, suggesting near-term emphasis on stabilizing Pre-Roll price tiers and selectively pruning underperforming SKUs.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

