

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Cannect Wellness is stocked at 47 licensed dispensaries across Illinois, with the deepest coverage in Chicago, Anna, Harrisburg, Milan, and Moline. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
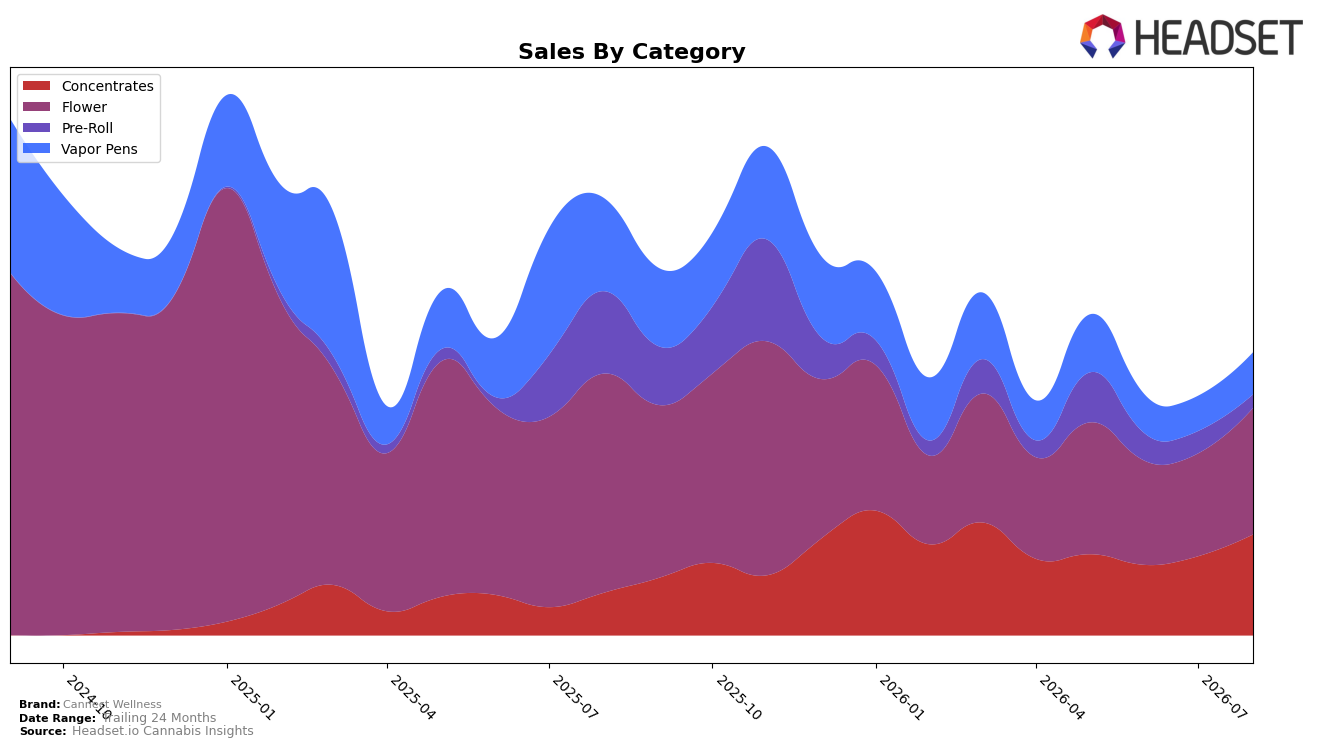
Cannect Wellness concentrated 44.75% of August 2026 sales in Flower and 35.75% in Concentrates, with Vapor Pens at 14.82% and Pre-Roll at 4.68%, indicating a two-category core. Year over year, Concentrates surged 137.34% while Flower fell 42.38%, and month over month both Flower and Concentrates expanded by 23.08% and 27.69% respectively, contrasted with a 39.95% monthly drop in Pre-Roll and a 19.61% lift in Vapor Pens. The brand held rank 68 in Flower within Illinois, and average price slipped 0.89% year over year alongside a 35.38% brand sales decline, implying mix-driven volume pressures despite selective pricing moderation.
The pivot toward Concentrates gaining 35.75% share while Flower retains 44.75% suggests Cannect Wellness is shifting from a Flower-led identity toward a dual-pillar portfolio, where high-growth Concentrates offset Flower contraction. With Vapor Pens down 54.98% year over year yet up 19.61% month over month, and Pre-Roll collapsing 83.92% year over year with a 39.95% monthly drop, the brand’s positioning favors higher-intensity formats over impulse-ready Pre-Rolls; this implies marketing and distribution should lean into Concentrates’ August 2026 momentum to stabilize overall sales while Flower’s rank at 68 in Illinois signals a need for SKU rationalization rather than price cuts.
Competitive Landscape
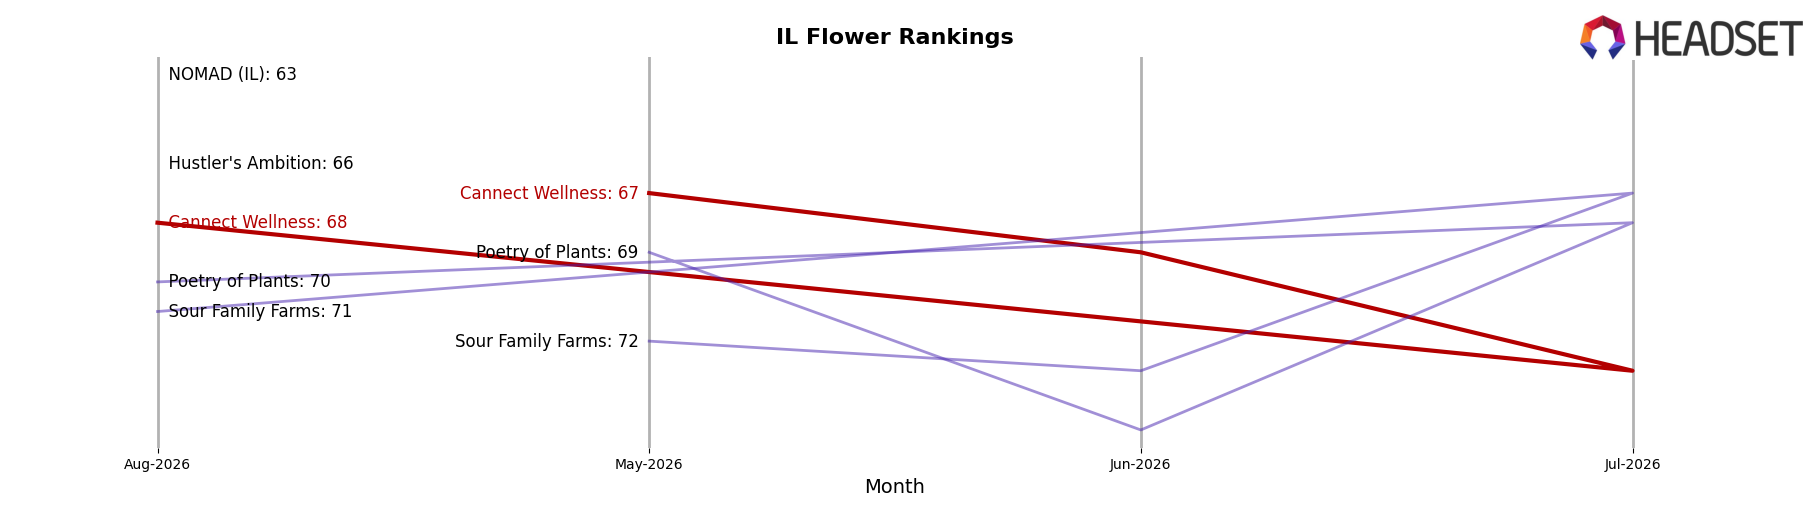
Cannect Wellness sits at rank #68 in Illinois Flower for August 2026, down 14 positions year over year from #54 and slipping 1 spot since May 2026 when it was #67; compared to its peak of #39 in August 2024, the brand has fallen 29 ranks while category leaders like High Supply / Supply held #1 both this year and last despite a -10.1% YoY sales change, and RYTHM maintained #2 with a 36.5% YoY increase, indicating Cannect Wellness is losing share against stable top-tier incumbents rather than being displaced by broad market churn; the trajectory from #54 to #68 alongside stagnation near #67 over the last three months implies erosion in relative velocity that will require either price or assortment repositioning to re-enter the top 50.
Notable Products
Cakelato (3.5g) delivered the headline in August 2026 with a +481% month-over-month surge to $21,704 and a jump to rank 1, while Blueberry Blintz (3.5g) fell -37% to rank 3 and Super Boof (3.5g) declined -45% to rank 9. Super Boof Live Resin Badder (1g) climbed +67% to rank 4, whereas Jelly Pie Cured Resin (1g) rose a more modest +47% to rank 2, indicating concentrates are gaining traction relative to several Flower SKUs. Four of the top ten are Flower SKUs, but only one of them improved month-over-month, whereas two Concentrates in the top four posted +47% and +67% gains. The product mix points to a pivot toward a hero Flower anchor supported by rising concentrates, implying Cannect Wellness is leaning into a barbell of one breakout Flower SKU and accelerating extracts to diversify away from volatile mid-tier Flower.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

