


Market Insights Snapshot
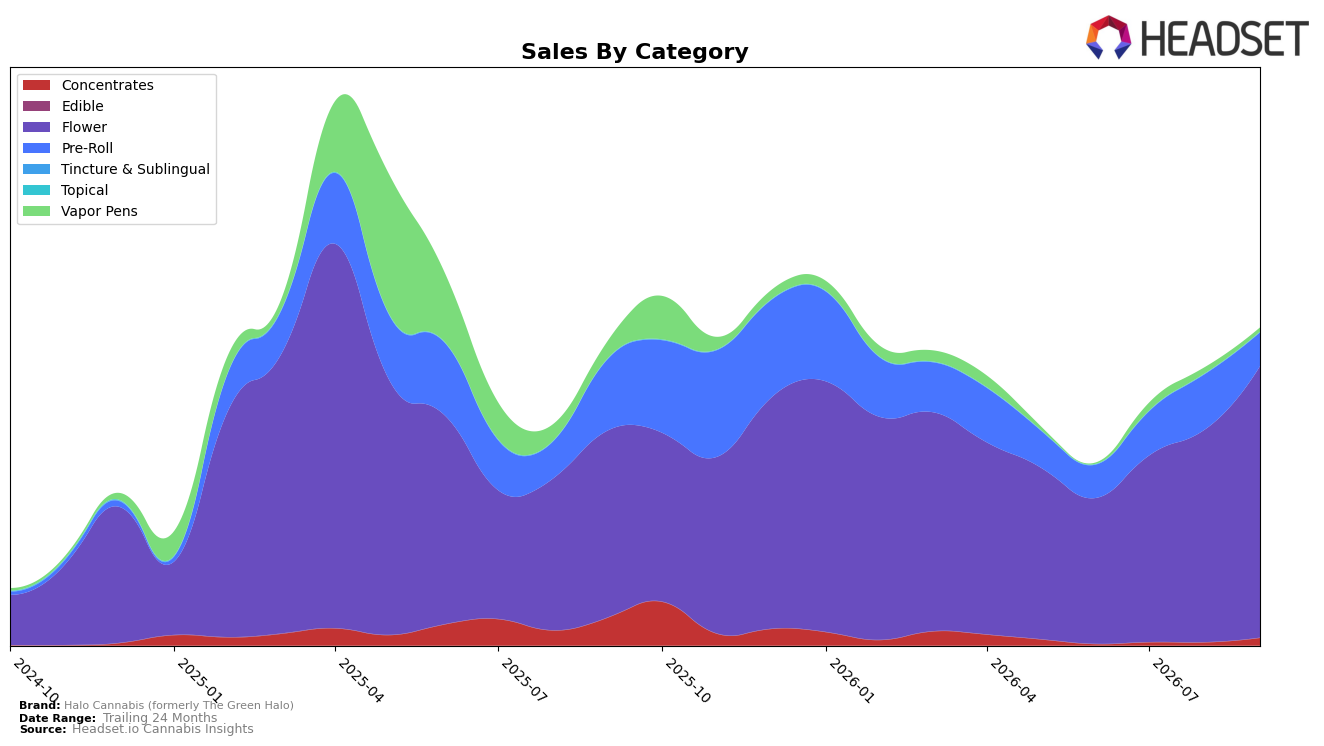
In September 2026, Halo Cannabis (formerly The Green Halo) concentrated 85.87% of sales in Flower, where category sales rose 45.32% year over year and 27.84% month over month, while Pre-Roll fell to a 10.58% share with a 53.18% YoY decline and a 39.41% MoM drop. Smaller lines were volatile: Concentrates held 2.34% share with a 155.33% MoM jump despite a 73.47% YoY decline, and Vapor Pens at 1.22% share contracted 34.81% MoM and 77.73% YoY; combined with an 8.65% YoY average price increase to $11.32 and a Flower rank of 26 in Arizona, the mix implies reliance on Flower for near-term volume while legacy inhalables retrench.
The shift deepens a single-category posture: expanding Flower share alongside Pre-Roll and Vapor Pen contractions reallocates demand toward higher-priced Flower (average Flower price $12.76) and away from lower-priced units, which can lift revenue per unit as long as Flower momentum holds and the rank at 26 in Arizona does not slip. The rebound in Concentrates (155.33% MoM) against steep YoY declines in both Concentrates (−73.47%) and Vapor Pens (−77.73%) signals tactical upside from niche shoppers rather than a structural recovery, so the pattern points to a positioning anchored in Flower with selective, test-and-scale bets in Concentrates to diversify risk from Pre-Roll’s 39.41% MoM and 53.18% YoY declines.
Competitive Landscape
Halo Cannabis (formerly The Green Halo) sits at rank #26 in AZ Flower in September 2026 after a year-over-year climb of 8 positions from #34, and a quarter-over-quarter move of 11 positions from #37 to #26, while still one spot short of its historical peak at #25 last reached in April 2025; against this, Just Flower held steady at #1 year over year (from #1 to #1) and Find. improved from #3 to #2, indicating that Halo’s upward trajectory is occurring beneath a relatively stable top tier. With Loud Pax surging from #51 to #5 and Mohave Cannabis Co. slipping from #2 to #3, the competitive middle is fluid, and Halo’s 8-rank YoY gain paired with an 11-rank improvement since June 2026 implies a momentum phase where near-term execution could convert into a return to, and potential surpassing of, its prior #25 peak.

Notable Products
Lemon Cherry Madness (3.5g) posted the standout move in September 2026 with a +105.9% month-over-month surge, climbing to rank 2, while Amoretto Sour (3.5g) slid -14.2% to rank 10. Flower concentrated the leaderboard with eight of the top ten SKUs, including Blunicorn (3.5g) at rank 1 and L.A. Baker (3.5g) up +28.7% at rank 5, whereas the highest Pre-Roll, Pineapple Burst Pre-Roll (1g), sat at rank 4 with Rose Sherb Pre-Roll (1g) down -5.8% at rank 6. Don Mega F2 (3.5g) contracted -43.4% to rank 7 even as Blunicorn (3.5g) led category revenue at $50,172, indicating volatility beneath headline gains. Taken together, outsized upside at the top and multiple double-digit declines imply a bet on Flower-driven hero SKUs over breadth, pushing Halo Cannabis (formerly The Green Halo) toward a more winner-takes-most product mix.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

