

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
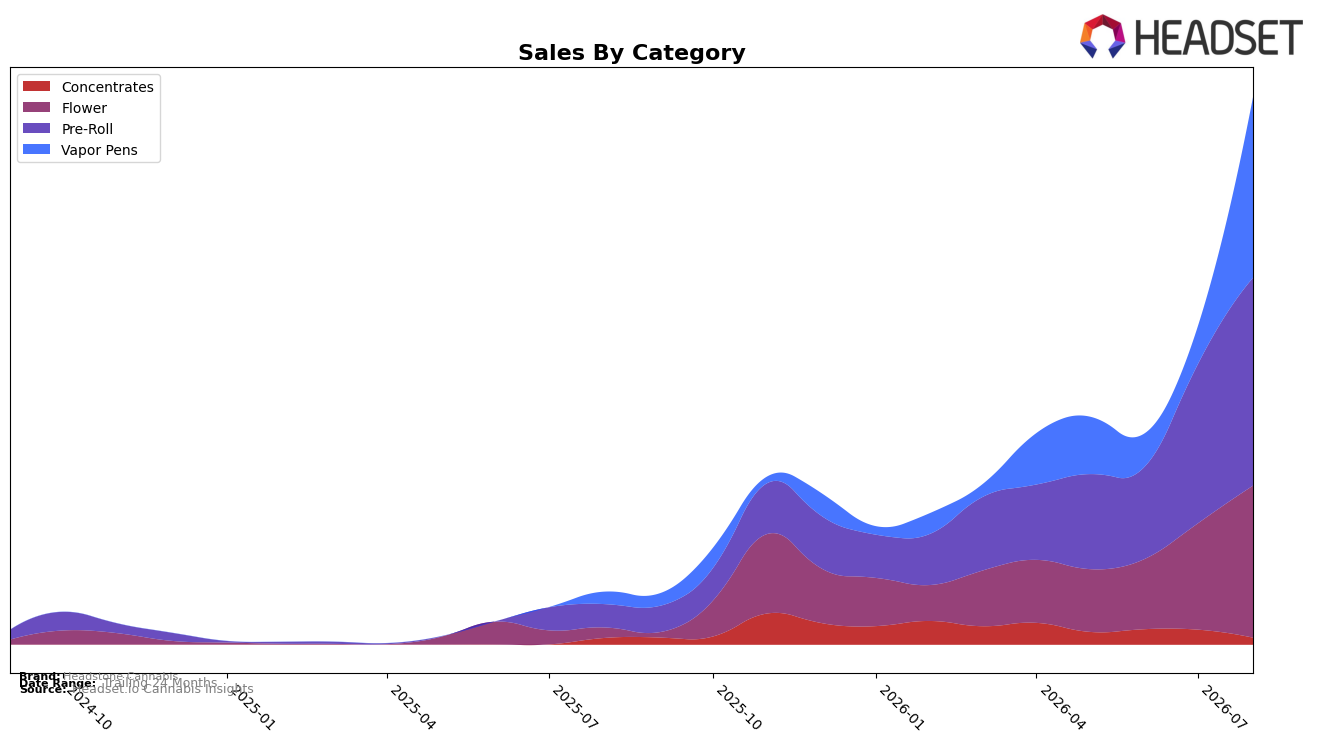
In August 2026, Headstone Cannabis concentrated 37.86% of sales in Pre-Roll, 33.18% in Vapor Pens, 27.71% in Flower, and 1.25% in Concentrates, with Pre-Roll ranking 15th in Alberta. Momentum skewed toward inhalables: Vapor Pens rose 376.04% month over month and 1,387.92% year over year, while Flower climbed 43.02% MoM and 1,376.04% YoY; Pre-Roll advanced 30.33% MoM and 797.79% YoY as Concentrates contracted 54.13% MoM despite a 3.18% YoY gain. With brand-level sales up 948.98% YoY and average price up 18.70% YoY to $25.97, the mix indicates a rapid shift toward higher-ticket inhalables alongside price elasticity that has not impeded volume, implying a short-term land-grab strategy anchored in Vapor Pens and supported by Flower while Pre-Roll scale sustains share leadership within the portfolio.
This mix shift implies Headstone Cannabis is repositioning toward potency-per-dollar and convenience: Vapor Pens at a $34.63 average price and Flower at $47.15 are capturing outsized growth versus Pre-Roll at $16.72, while Concentrates’ 1.25% share and 54.13% MoM decline suggest deliberate deprioritization. The 15th-place Pre-Roll rank in Alberta alongside a 30.33% MoM gain signals that portfolio breadth, not just category leadership, is driving scale, and the 33.18% share in Vapor Pens alongside 27.71% in Flower creates a twin-engine for mix accretion. The pattern implies Headstone Cannabis can trade consumers up without eroding volume by leaning into Vapor Pens and Flower while using Pre-Roll as a recruitment on-ramp, and exiting low-yield Concentrates to lift average price and maintain YoY growth velocity.
Competitive Landscape
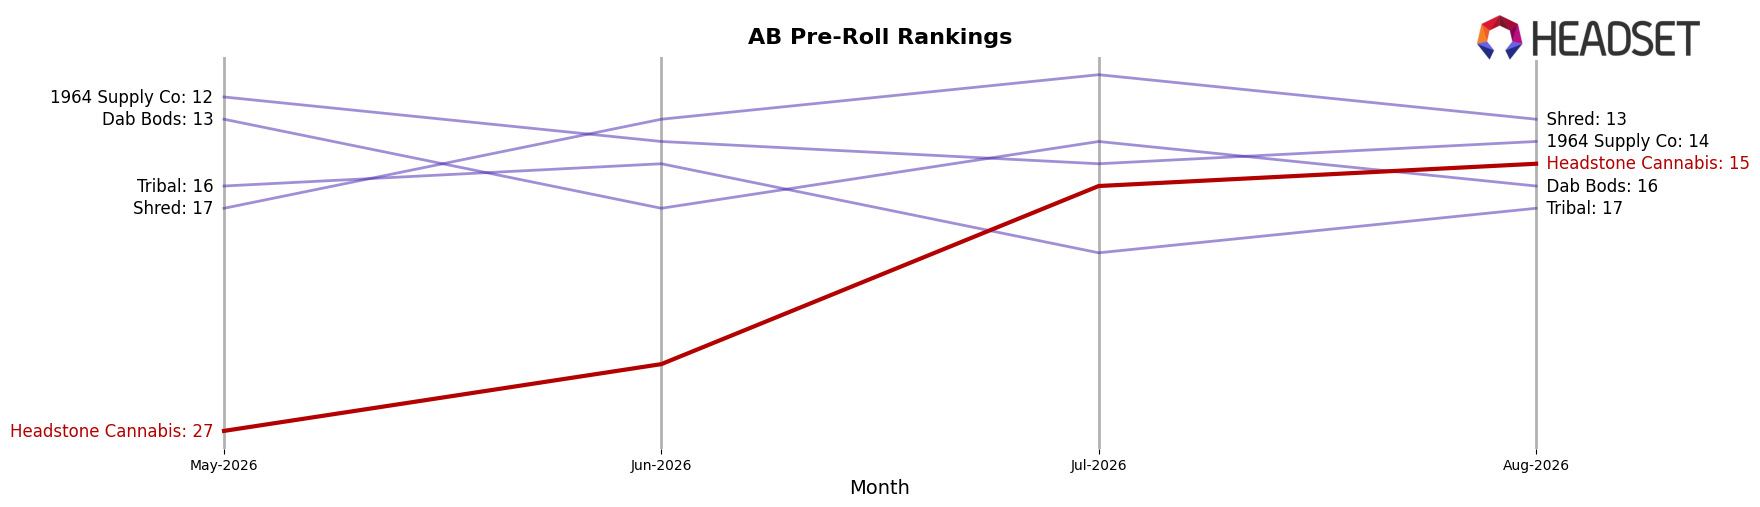
Headstone Cannabis sits at rank 15 in AB Pre-Roll in August 2026, improving 58 positions year over year from rank 73 and climbing 12 spots from rank 27 since May 2026; this is also its peak-to-date rank of 15 in August 2026. Against incumbents, Back Forty / Back 40 Cannabis moved up from rank 5 to rank 1 while growing sales 51.5% year over year, and General Admission slipped from rank 1 to rank 2 with a 20.3% sales decline, indicating that Headstone Cannabis’s ascent is occurring amid leader churn rather than broad category lift. The pattern implies a trajectory driven by share capture from weakening top-tier players and momentum consolidation at the mid-table, setting expectations for continued rank pressure upward if retention holds through November 2026 and December 2026.
Notable Products
Afterlife Cured Resin Disposable (1g) posted the standout move in August 2026 with a 224.9% month-over-month surge that vaulted it into rank 6, while Black Mountain Morgue Cured Resin Cartridge (1g) doubled at +102.0% to settle at rank 9. In parallel, Flawless Clarity Diamond Infused Pre-Roll 3-Pack (1.5g) climbed 72.0% to rank 10 as Lamb of God (7g) jumped 84.5% to rank 4. The pattern points to a pivot where fast-accelerating Vapor Pens anchor incremental gains while a single Flower SKU scales quickly to diversify beyond Pre-Rolls.
Within Pre-Rolls, Lamb of God Pre-Roll 5-Pack (2.5g) held rank 1 despite a slower 47.3% MoM than the 72.0% recorded by the diamond-infused 3-pack at rank 10, and Ghoul Fuel Pre-Roll (0.5g) advanced 21.6% to rank 2. Four of the top ten are Pre-Rolls, but two Vapor Pens posted triple- and double‑digit MoM expansions while Pre-Roll gains ranged from 14.7% to 72.0%, indicating momentum is shifting toward inhalable formats with higher velocity. The mix implies Headstone Cannabis is broadening growth drivers from legacy Pre-Rolls into Vapor Pens and larger-pack Flower to capture faster-turn segments.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

