
Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Is this your brand?
See your full sales and distribution data: where you sell, how you're priced, and how you rank against the brands next to you on the shelf.
See your brand's dataCarry this brand in your store?
Headset Retailer is free. Connect your POS and see what's selling and what's sitting.
Sign up freeMarket Insights Snapshot
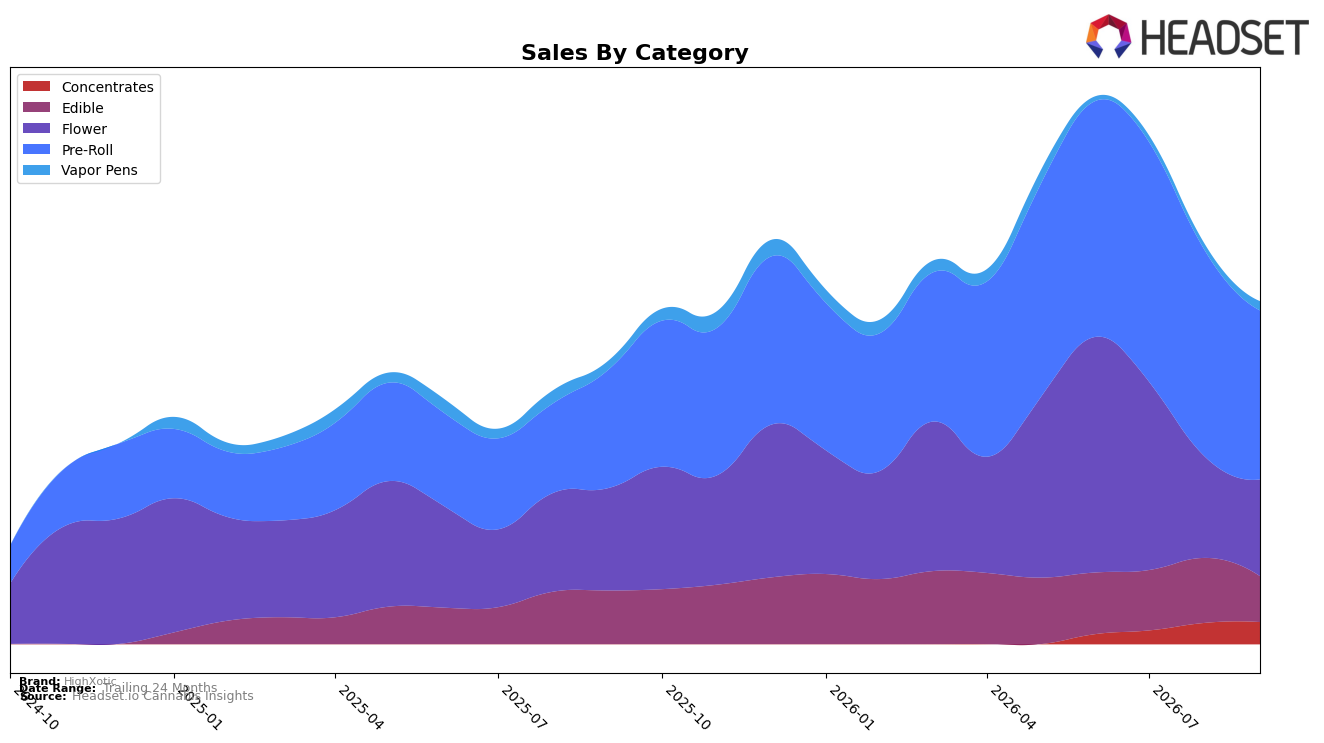
HighXotic’s category mix in September 2026 tilted heavily to Pre-Roll at 49.32% share, with year-over-year sales up 42.98% but month-over-month down 18.09%, while Flower held 28.22% share with a -5.49% YoY change and a -4.68% MoM slide. Edible accounted for 13.35% share with -14.57% YoY and -29.48% MoM, contrasted by Vapor Pens at 2.65% share growing 2.17% YoY and 47.15% MoM, and Concentrates at 6.46% share with a 4.03% MoM uptick and no YoY basis. With an average price up 35.24% YoY and Pre-Roll ranked 27th in Ontario, the pattern implies reliance on a single growth driver (Pre-Roll) alongside tactical momentum in Vapor Pens, while Flower and Edible contractions pull against broader 21.11% brand YoY sales growth.
The combination of Pre-Roll’s elevated share and double-digit YoY gain with a concurrent MoM drop, alongside a sharp 47.15% MoM lift in Vapor Pens and a 4.03% MoM rise in Concentrates, implies near-term repositioning toward inhalable formats as Edible and Flower retreat (-29.48% MoM and -4.68% MoM). Given the 27th Pre-Roll rank in Ontario and a 35.24% YoY increase in average price, the mix shift suggests pricing headroom is being captured primarily in Pre-Roll while diversification into Vapor Pens and Concentrates buffers month-to-month volatility, pointing to a strategy that trades depth in Flower and Edible for breadth across faster-cycling inhalables.
Competitive Landscape
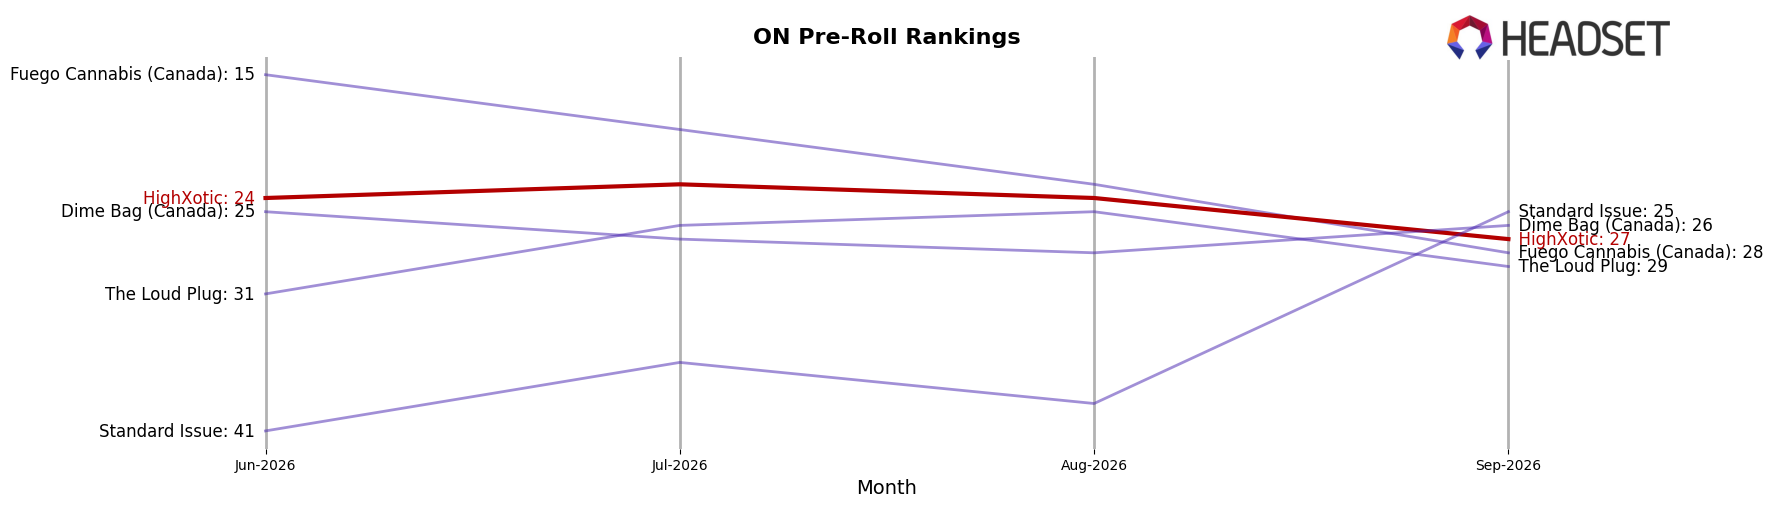
HighXotic sits at rank #27 in ON Pre-Roll for September 2026, improving 17 positions year over year from #44 but sliding 3 spots from June 2026’s #24 and 4 from its peak at #23 in July 2026; meanwhile, Back Forty / Back 40 Cannabis advanced from #2 to #1 with a 46.6% YoY sales gain, and General Admission fell from #1 to #2 alongside a 38.2% YoY sales decline, signaling that HighXotic’s YoY climb is happening while leadership is redistributing at the top. With Spinach jumping from #17 to #4 on 141.2% YoY growth and Thumbs Up Brand rising from #8 to #3 on 62.1% YoY growth, HighXotic’s recent quarter-over-quarter drift from #24 to #27 amid a market where upward moves of 5–13 ranks are occurring at the top implies that incremental YoY gains without sustained monthly momentum risk being overshadowed by faster movers.
Notable Products
Royal Journey Pre-Roll 3-Pack (1.5g) posted the most acute movement in September 2026 with a -73.7% month-over-month drop and slid to rank 9, while TenTen - Sunny Drift Live Rosin Gummy (10mg) declined -15.5% and sat at rank 3. In contrast, CBG/THC 5:1 - Morning Dew Live Rosin Gummy (100mg CBG, 20mg THC) jumped +71.0% to rank 2 and, together with TenTen - Caribbean Chill Live Rosin Gummy (10mg) at rank 1 despite a -48.6% decline and $86,655 in sales, indicates mixed demand within Edibles. Four of the top ten are Pre-Roll SKUs clustered at ranks 4–9, but with additional drops of -59.0% for Royal Spice#3 - Hindu Glue Aces Pre-Roll 3-Pack (1.5g) at rank 6 and -52.9% for Royal One - Vault Series Pre-Roll (1g) at rank 7, the segment’s velocity is thinning even as shelf presence remains high. The pattern implies HighXotic is pivoting toward functional Edibles for momentum while reevaluating Pre-Roll breadth that holds rank positions but yields declining throughput.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

