

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Peninsula Cannabis is stocked at 247 licensed dispensaries across Michigan, with the deepest coverage in Detroit, New Buffalo, Monroe, Hazel Park, and Battle Creek. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
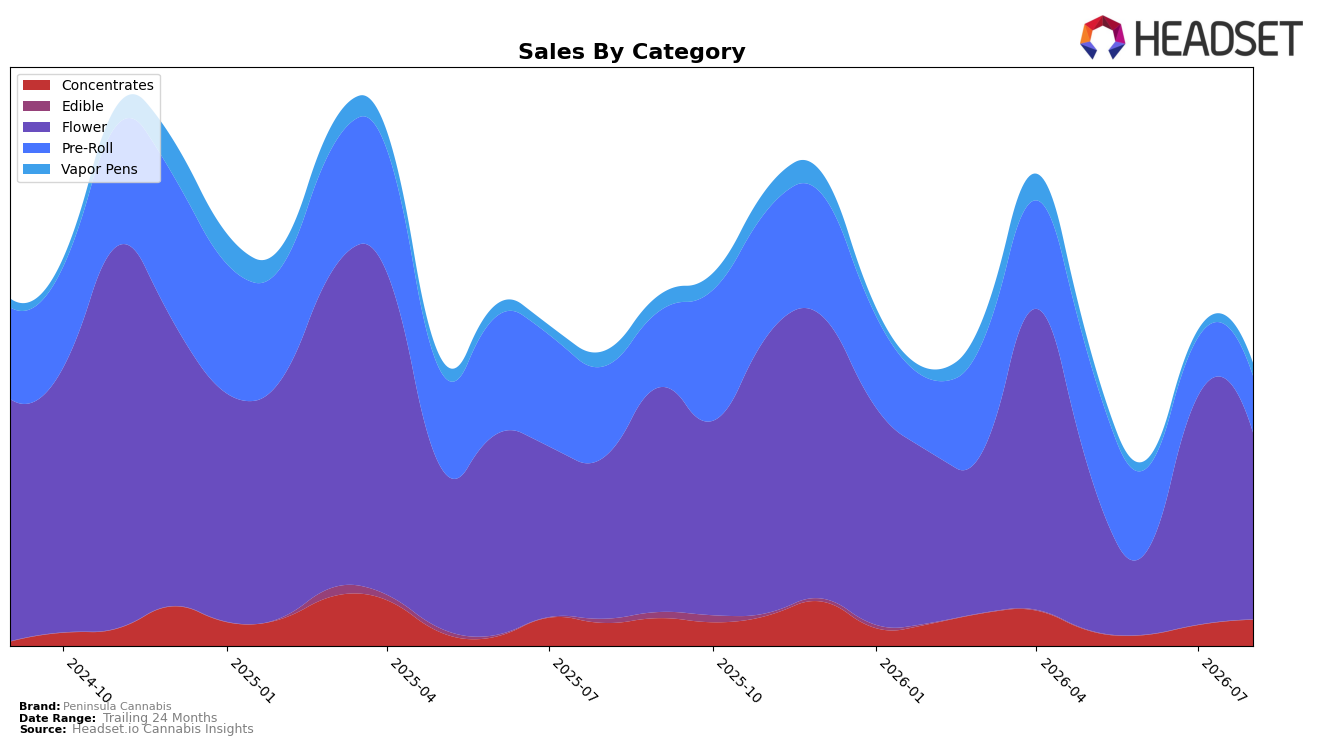
In August 2026, Peninsula Cannabis concentrated 66.08% of sales in Flower with year-over-year growth of 14.85% but a month-over-month decline of 19.12%, while Pre-Roll held 20.11% share with a 37.69% YoY drop and a 2.59% MoM dip. Concentrates rose to 9.29% share with 13.96% YoY growth and a 25.49% MoM jump, and Vapor Pens reached 4.53% share despite a 15.63% YoY decline as MoM surged 71.31%. The brand’s average price of $20.95 sits alongside a 33.52% YoY price increase, suggesting a trade-up dynamic even as overall brand sales fell 4.49% YoY; net effect, mix is tilting from Pre-Roll toward higher-priced Concentrates and Vapor Pens, implying a margin-first pivot despite short-term Flower softness.
With Flower ranked 45th in Michigan and MoM down 19.12% against a 14.85% YoY gain, Peninsula Cannabis is relying on improved depth-of-line rather than pure velocity, as Concentrates’ 25.49% MoM growth and Vapor Pens’ 71.31% MoM spike offset Pre-Roll’s 37.69% YoY contraction. Given that Flower still accounts for 66.08% of mix and Pre-Roll 20.11%, the near-term positioning hinges on stabilizing large-base Flower while leaning into smaller but faster-moving Concentrates and Vapor Pens; the pattern implies share defense in core Flower in Michigan alongside a calculated shift to premium-adjacent formats where price tolerance is rising.
Competitive Landscape
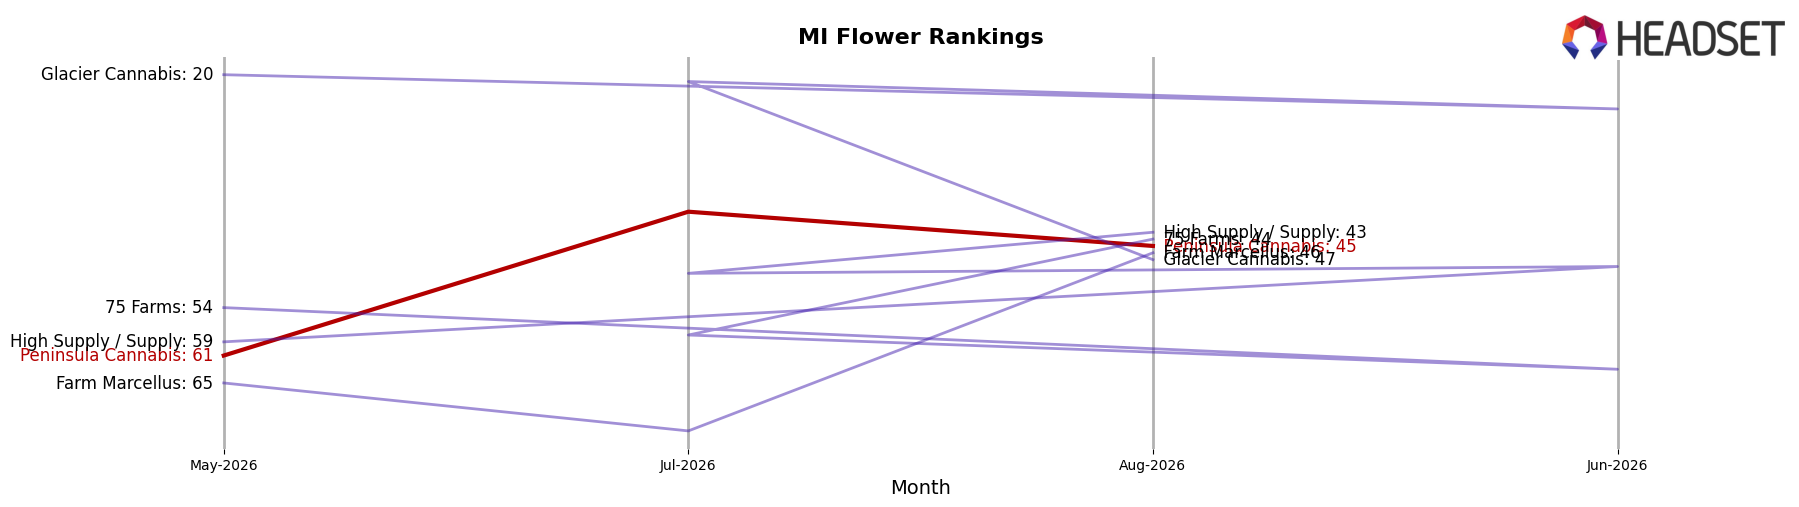
Peninsula Cannabis is ranked #45 in MI Flower in August 2026, improving 17 positions from #62 year over year, and rising 16 spots from #61 in May 2026, while still trailing its peak rank of #24 from November 2024. Against this backdrop, High Minded holds #1 despite a -17.4% year-over-year sales change, and NOBO climbed from #42 to #3 with a 506.8% year-over-year sales increase, indicating that share is consolidating toward leaders with sharper momentum than Peninsula Cannabis’s recent rank gains. The pattern implies Peninsula Cannabis’s upward trajectory is recovery rather than breakout, as mid-pack gains of 17 ranks YoY are outpaced by top-tier surges that reshape the leaderboard.
Notable Products
Runtz Pre-Roll (1g) set the tone in August 2026 with a rank of 1 and a month-over-month gain of 89.1%, while Sherb Pie Pre-Roll (1g) slid to rank 9 with a 36.3% decline. Runtz (7g) dropped to rank 2 with a steep 38.4% MoM contraction even as Party Poppers (Bulk) jumped 50.2% at rank 4, indicating a pivot from packaged Flower toward value and impulse formats. Four of the top ten are Pre-Roll SKUs, and the category also occupies ranks 1 and 3, concentrating velocity away from mid-pack Flower like Runtz (3.5g) despite its 37.9% MoM rise. The mix implies Peninsula Cannabis is consolidating demand in Pre-Rolls and bulk Flower, prioritizing high-frequency and value-forward formats over large-pack premium Flower, even with one-off dollar peaks such as $179,425 for Runtz (7g).
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

