

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Is this your brand?
See your full sales and distribution data: where you sell, how you're priced, and how you rank against the brands next to you on the shelf.
See your brand's dataCarry this brand in your store?
Headset Retailer is free. Connect your POS and see what's selling and what's sitting.
Sign up freeWhere to Buy
The Grower Circle is stocked at 68 licensed dispensaries across Nevada and New Mexico, 54 of them in Nevada, with the deepest coverage in Las Vegas, Henderson, Reno, North Las Vegas, and Carson City. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
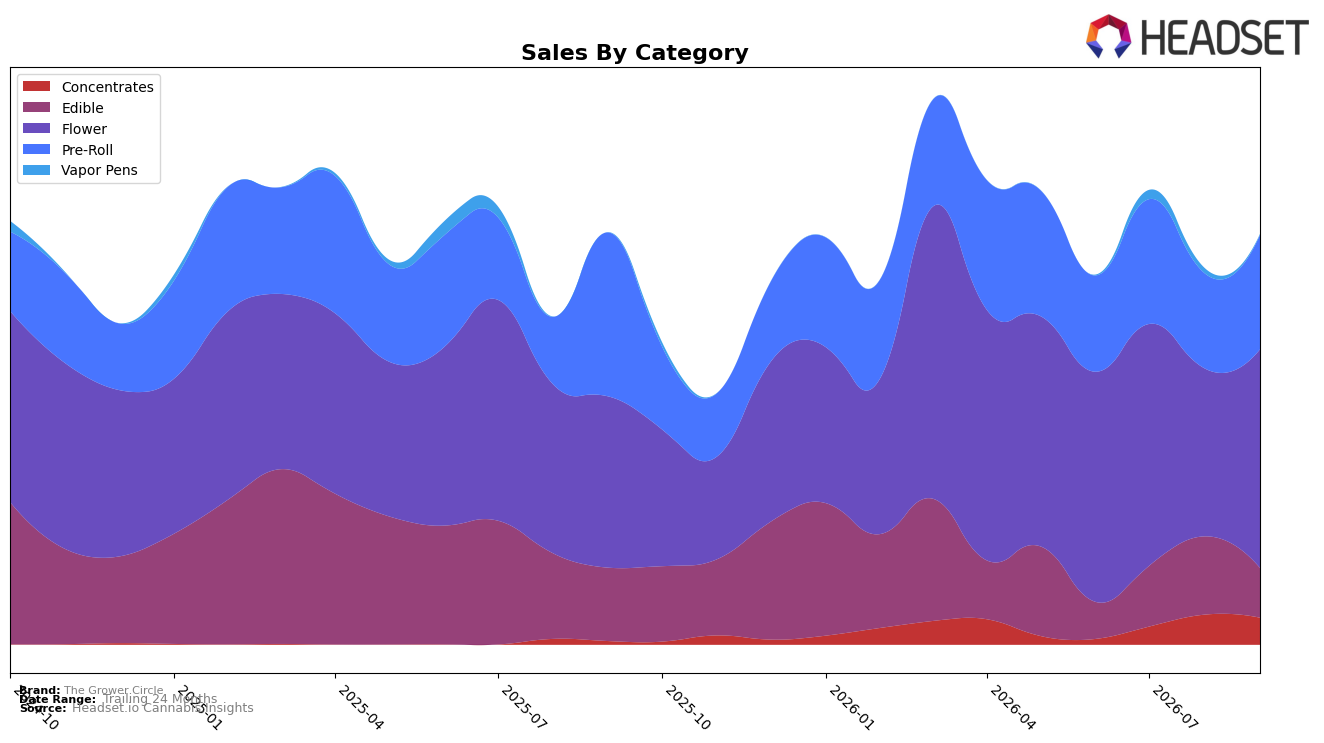
In September 2026, The Grower Circle’s category mix tilted further toward Flower at 53.30% share with 27.64% YoY growth and 30.18% MoM, while Pre-Roll held 27.87% share despite a -30.30% YoY drop offset by a 20.26% MoM rebound. Edible contracted to 12.09% share with -32.25% YoY and -36.49% MoM, contrasted by Concentrates at 6.56% share posting 668.27% YoY but sliding -10.27% MoM; Vapor Pens fell to 0.18% share with -85.27% MoM. Despite a -44.35% YoY decline at the total brand level and a 58.92% YoY rise in average price, the 22nd rank in Flower in Nevada indicates the mix is concentrating around higher-priced inhalables and away from Edible and Vapor Pens.
The mix shifts imply The Grower Circle is leaning into premiumized inhalable formats: Flower’s 30.18% MoM surge alongside Concentrates’ 668.27% YoY suggests emphasis on higher-ticket units even as Concentrates cooled -10.27% MoM, and Pre-Roll’s 20.26% MoM lift provides volume ballast against Edible’s -36.49% MoM decline. With average price up 58.92% YoY and Flower anchoring share at 53.30% while overall sales are down -44.35% YoY, the brand’s positioning skews toward fewer, higher-value baskets that support the Nevada Flower rank at 22 but limit breadth in Edible and Vapor Pens at 12.09% and 0.18% share, respectively.
Competitive Landscape
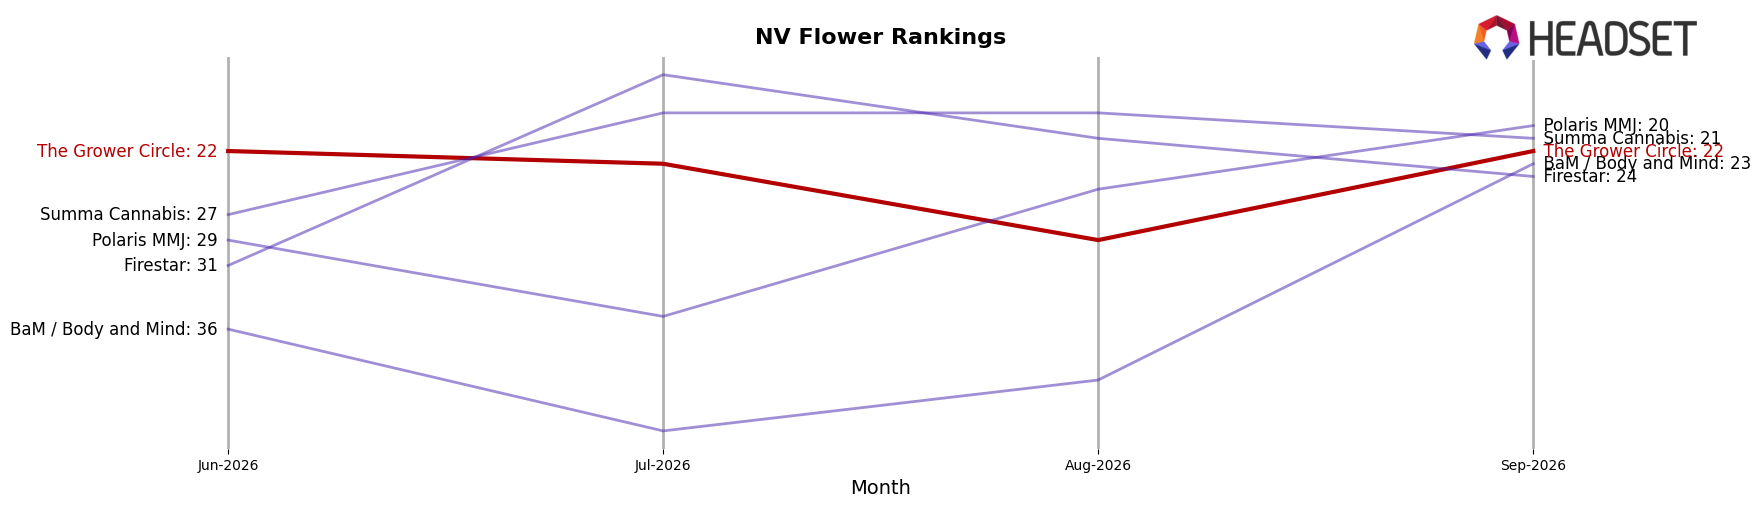
The Grower Circle sits at rank #22 in NV Flower for September 2026, improving 9 positions YoY from #31 while holding flat versus June 2026 at #22, and remaining 3 spots below its March 2026 peak of #19; in contrast, RYTHM held #1 year over year with a 19.7% sales increase and STIIIZY stayed at #2 alongside a 24.2% sales lift, indicating that while top-tier leaders are stable at ranks #1–#2, The Grower Circle’s mid-pack gain of 9 ranks YoY did not translate into further quarter-over-quarter ascent. With Alternative Medicine Association / AMA advancing from #5 YoY to #3 on 32.6% growth and Neon Moon climbing from #9 YoY to #4 on an 82.7% surge, competitive pressure is tilting upward faster in ranks #3–#5 than in the #19–#22 band where The Grower Circle is anchored; the pattern implies that maintaining #22 after a 9-rank YoY rise points to momentum that has cooled, requiring a catalyst to re-enter the top-20 and close the 3-rank gap to its March 2026 peak.
Notable Products
GMO x Lemon (3.5g) delivered the headline move in September 2026 with a 177% month-over-month surge to rank 1, while GMO x Lemon Pre-Roll (1g) inched up 4% at rank 8, indicating traction anchored in the Flower format rather than its line extension; with Flower SKUs taking 3 of the top 5 ranks and Pre-Rolls occupying ranks 2, 4, 6, 7, 8, and 9, the mix tilt implies a portfolio leaning on inhalables but with outsized momentum concentrated in flagship Flower. Animal Cookies Pre-Roll (1g) advanced 38% to rank 2 versus Flight Bites - Berry Cereal Hash Rosin Gummies 10-Pack (100mg) up 24% at rank 10, and the edible’s spend at $13,840 is still well below the top Flower leaders, suggesting incremental rather than primary demand capture from non-inhalable formats. The clustering of multiple Pre-Rolls in the top 10 alongside only one edible points to an inhalable-led basket where premium Flower spikes are the primary growth catalyst for The Grower Circle’s near-term commercial direction.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

