


Where to Buy
Trichome Technologies (OR) is stocked at 61 licensed dispensaries across Nevada, Washington, and 4 other states, 24 of them in Nevada, with the deepest coverage in Las Vegas, Henderson, Carson City, Fallon, and Mesquite. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
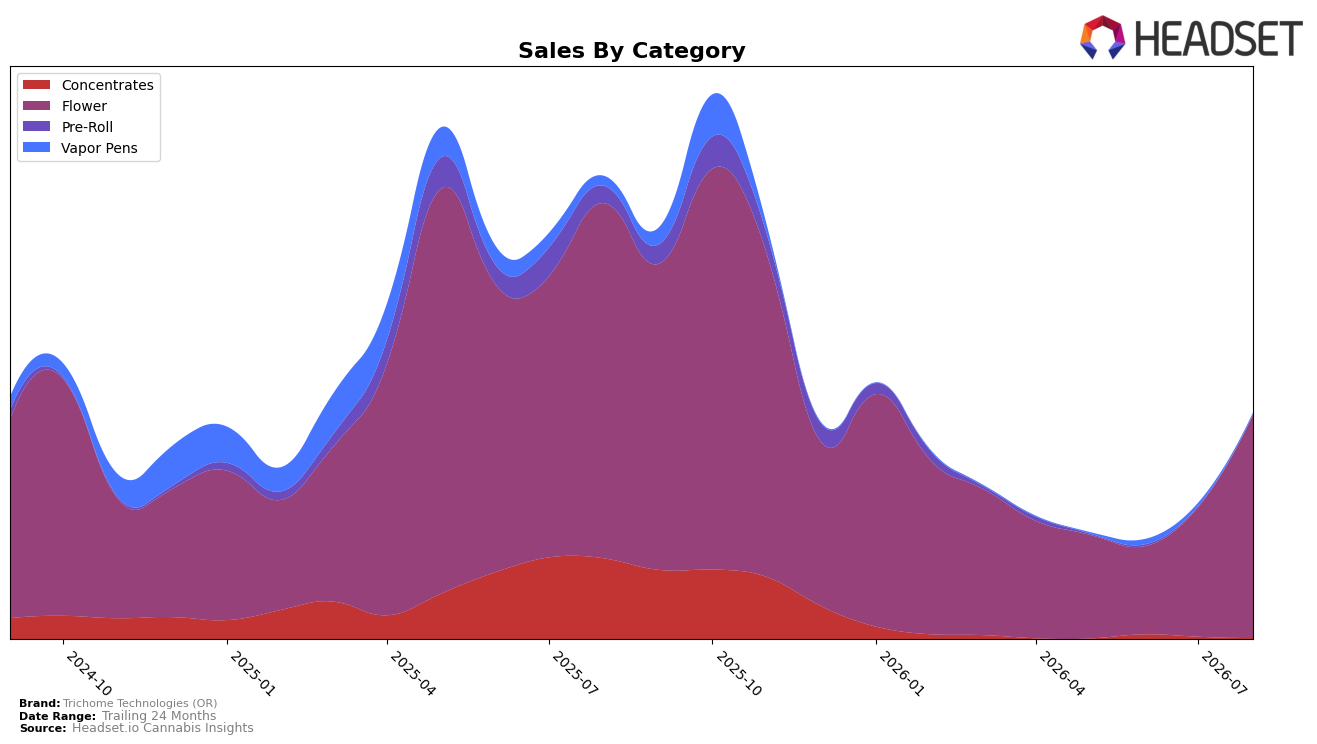
In August 2026, Trichome Technologies (OR) concentrated 98.79% of sales in Flower, where sales moved 72.81% month over month but fell 37.10% year over year, while Vapor Pens at 0.72% share declined 48.54% MoM and 83.46% YoY. Concentrates slipped to 0.39% share with a 59.66% MoM drop and a 98.90% YoY decline, and Pre-Roll at 0.10% share contracted 77.08% MoM and 98.75% YoY. With brand-level sales down 51.14% YoY and average price down 44.02% YoY, the mix shows expansion within Flower offsetting deep contractions elsewhere; the pattern implies the brand is re-centering around a single-category footprint to stabilize volume despite broad category retrenchment.
The heavy tilt toward Flower coincides with a rank of 48 in Flower in Oregon, suggesting that the 72.81% MoM gain in its dominant category is not yet translating into higher competitive standing while share in adjacent formats shrinks by 48.54% to 77.08% MoM. Given a 51.14% YoY sales contraction and a 44.02% YoY price decrease alongside 98.75% to 98.90% YoY declines in Pre-Roll and Concentrates, the brand is likely trading assortment breadth for price-led Flower velocity; this implies near-term positioning as a value-forward Flower specialist with limited cross-category capture and constrained laddering into higher-priced formats.
Competitive Landscape
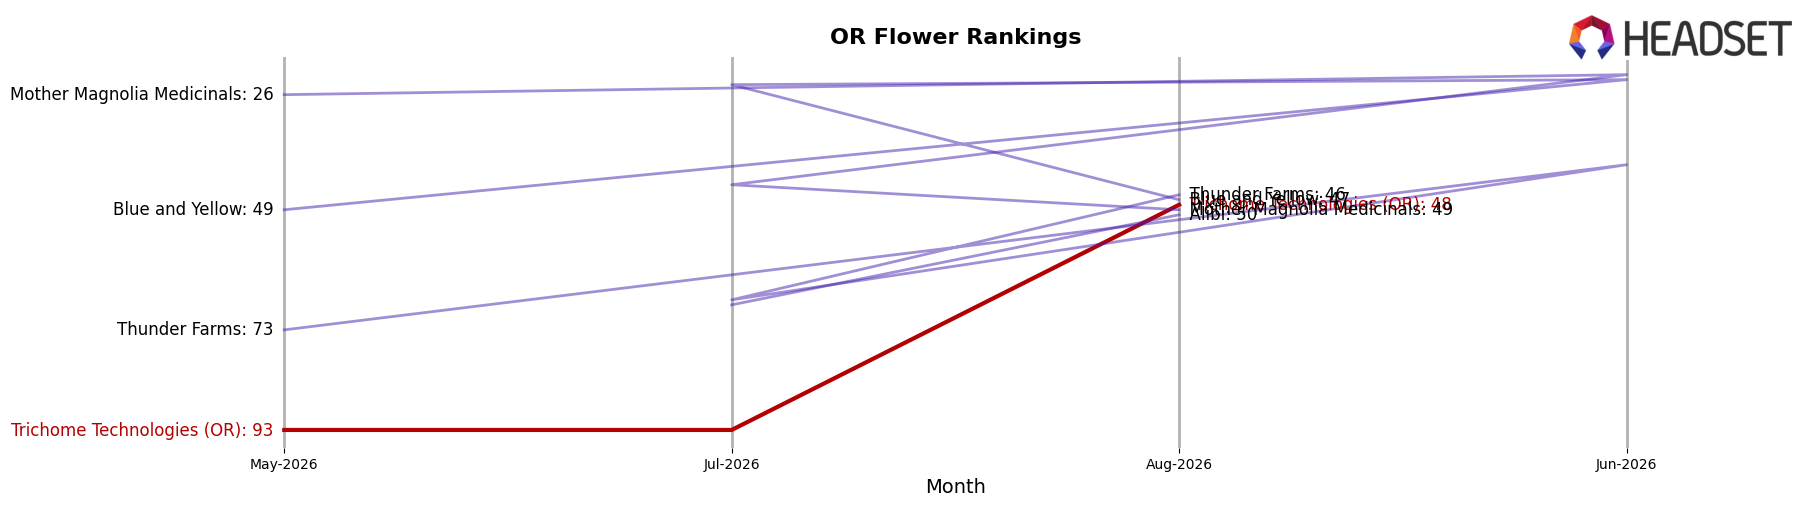
Trichome Technologies (OR) sits at rank #48 in OR Flower in August 2026, improving 9 positions year over year from #57 while rebounding 45 spots from #93 in May 2026; however, it remains 23 places below its peak at #25 from May 2025. Competitive pressure is acute: Grown Rogue moved from #3 to #1 with a 49% YoY sales gain, and Oregrown advanced from #23 to #3 alongside a 182% YoY increase, whereas PRUF Cultivar / PRŪF Cultivar slid from #1 to #2 with a 17% YoY decline. The pattern implies Trichome Technologies (OR) is recovering rank faster than earlier in the year but must accelerate velocity to keep pace with leaders that are climbing double-digit ranks and triple-digit growth.
Notable Products
Black Widow (Bulk) delivered the defining move in August 2026 with a 1,136% month-over-month surge to rank 1, while White Runtz (3.5g) also leapt 160% to rank 3. In contrast, Black Widow (1g) fell 21% to rank 5 and Super Runtz (3.5g) slipped 5% to rank 4. With eight of the top ten positioned in Flower and three SKUs sitting in ranks 1, 3, and 4, the mix signals a pivot toward bulk-led Flower velocity and away from smaller-size Flower units, implying an emphasis on wholesale-focused throughput over breadth in packaged formats.
Pineapple Tang (1g) climbed 48% to rank 2, while Pineapple Tang (3.5g) dropped 53% to rank 8, and Grandpas Cookies (3.5g) declined 70% to rank 7. Blueberry Sugar (Bulk) contracted 80% to rank 6, and the first Vapor Pens appearance, Dutch Treat Live Resin Disposable (1g), entered at rank 10 with $1,035 in August 2026. The divergence between bulk Flower gains and packaged 3.5g pullbacks implies Trichome Technologies (OR) is consolidating demand into high-volume Flower formats while only tentatively testing Vapor Pens.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

