
Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Seed & Smith is stocked at 141 licensed dispensaries across Colorado and Maryland, 140 of them in Colorado, with the deepest coverage in Denver, Colorado Springs, Aurora, Longmont, and Grand Junction. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
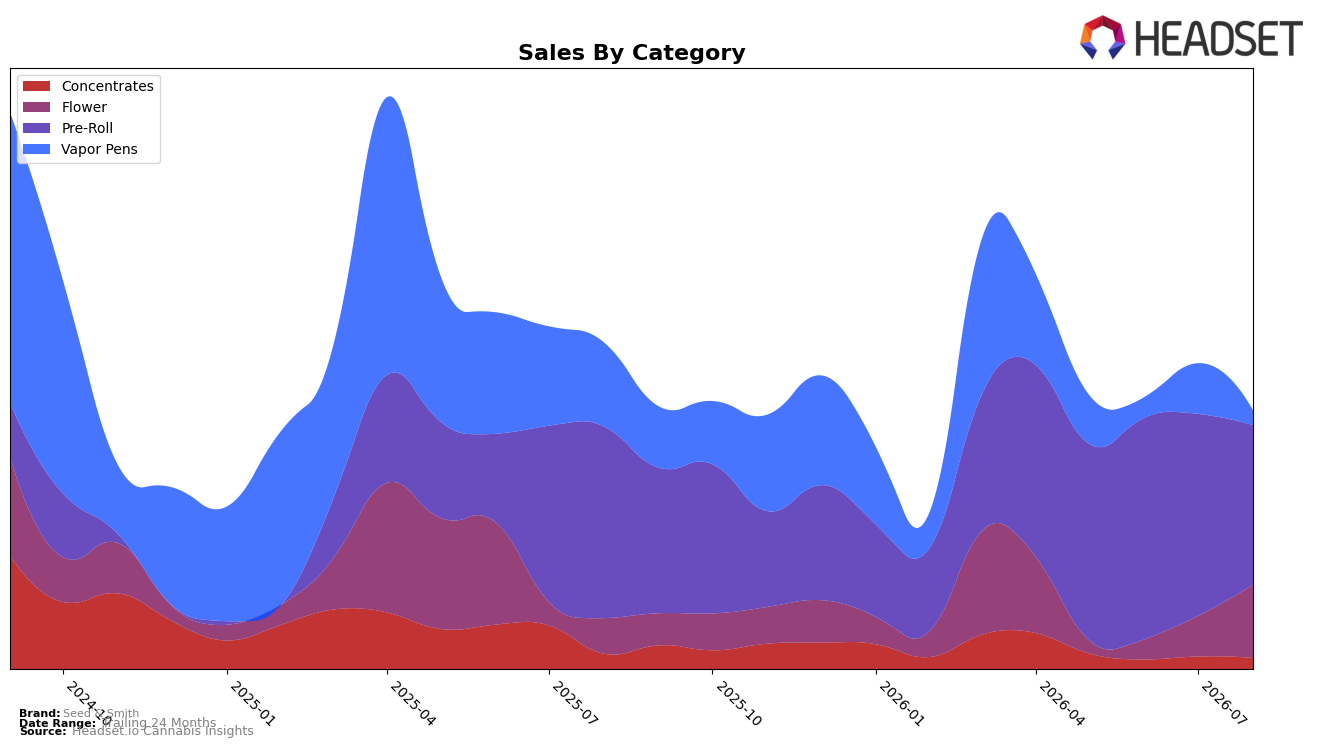
In August 2026, Seed & Smith concentrated 60.58% of sales in Pre-Roll, where year-over-year sales fell 16.49% and month-over-month declined 20.74%, while the category held an average price of $18.94; by contrast, Flower rose to a 28.24% mix with year-over-year growth of 100.32% and month-over-month growth of 76.28% at an average price of $21.65. Vapor Pens shrank to 6.25% share with year-over-year down 80.64% and month-over-month down 68.37% at a $30.51 average, as Concentrates held 4.93% share with year-over-year down 24.43% and month-over-month down 9.78% at a $15.80 average. With overall brand sales down 20.29% year-over-year and average price down 11.93%, the pattern implies a pivot toward Flower volume to offset contracting Pre-Roll and Vapor Pens, trading into a lower-price environment while relying on a growing Flower base to stabilize mix.
Positioning-wise, Seed & Smith’s reliance on Pre-Roll at 60.58% alongside a rank of 37 in Colorado Pre-Roll suggests vulnerability if double-digit month-over-month declines persist, whereas the 76.28% month-over-month and 100.32% year-over-year surge in Flower indicates a regain path via mid-price Flower. The 80.64% year-over-year decline in Vapor Pens and 24.43% year-over-year drop in Concentrates reduce category breadth, and the 11.93% brand-wide price decrease points to a value-led stance; together these shifts imply Seed & Smith should lean into Flower-led acquisition and defend Pre-Roll share with targeted price-pack architecture to prevent further mix erosion.
Competitive Landscape
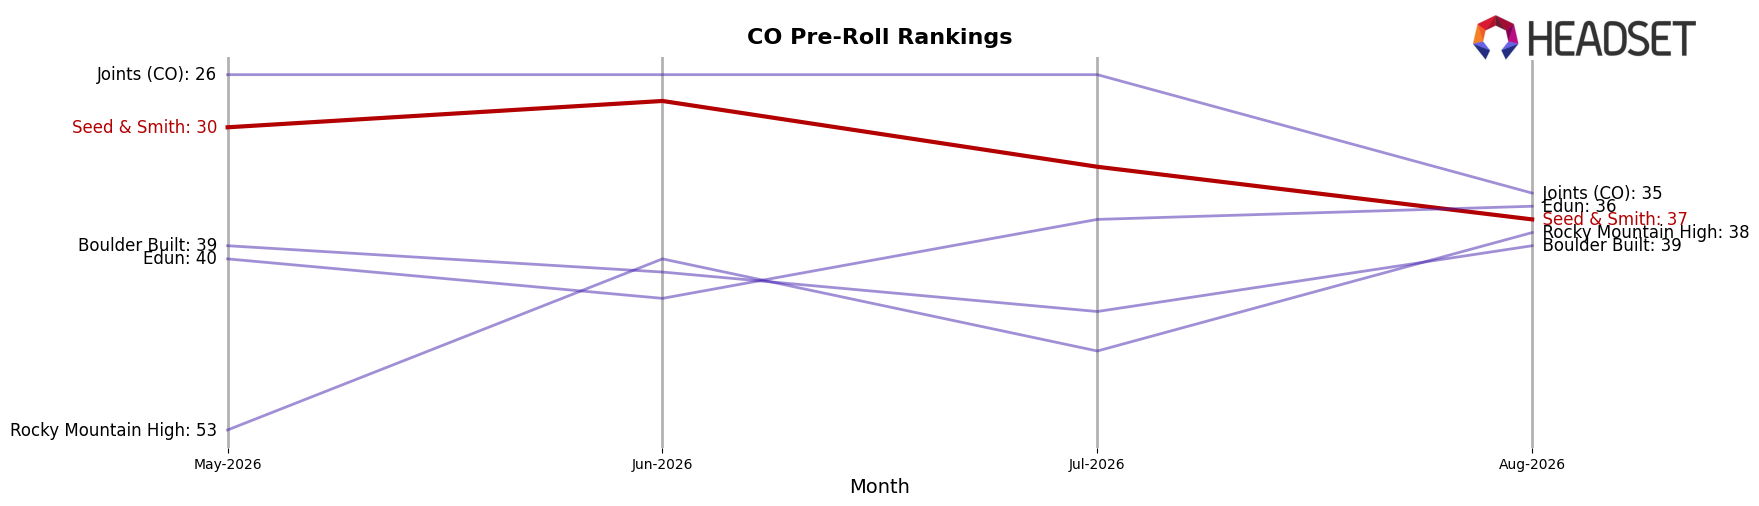
Seed & Smith sits at rank 37 in CO Pre-Roll for August 2026, a 1-place improvement from rank 38 year over year but a 7-place slide from rank 30 in May 2026 to 37 by August 2026; meanwhile, the brand’s best position of rank 28 in June 2026 contrasts with a return to the mid-30s three months later. Competitive context tightened at the top: Green Label Cannabis held rank 1 year over year to rank 1 despite a 30.1% sales contraction, while Cali-Blaze moved up from rank 3 to rank 2 on 19.7% growth and Green Dot Labs advanced from rank 4 to rank 3 with 55.1% growth; in contrast, Kaviar fell from rank 2 to rank 4 with a 41.5% decline even as Be One Kind vaulted from rank 28 to rank 5 on 292.8% growth. The mix of a 1-rank YoY gain alongside a 9-rank gap from the June 2026 peak implies Seed & Smith is oscillating around the lower mid-tier, where brief peaks are not yet converting into sustained share capture against faster-climbing rivals.
Notable Products
KY Jealous Shake (14g) posted the standout move with a 226.9% month-over-month surge to $16,725, while Apricot Scone (3.5g) fell 30.3% and slipped to rank 6 from a higher tier implied by that decline. Pineapple Infused Pre-Roll (1g) dropped 55.0% yet still held rank 1, and Strawberry Kiwi Infused Pre-Roll 5-Pack (5g) rose 8.5% at rank 2, indicating price-sensitive volatility at the top alongside incremental stability. With two Flower SKUs in the top six growing triple- and double-digits and three Pre-Roll SKUs occupying ranks 1, 2, and 3, the mix points to Seed & Smith tilting toward value-driven Flower upsides while maintaining Pre-Roll scale as the volume anchor.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

