


Where to Buy
Cloud 9 (CO) is stocked at 36 licensed dispensaries across Colorado, Vermont, and 4 other states, 19 of them in Colorado, with the deepest coverage in Denver, Pueblo West, Colorado Springs, Aurora, and Boulder. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
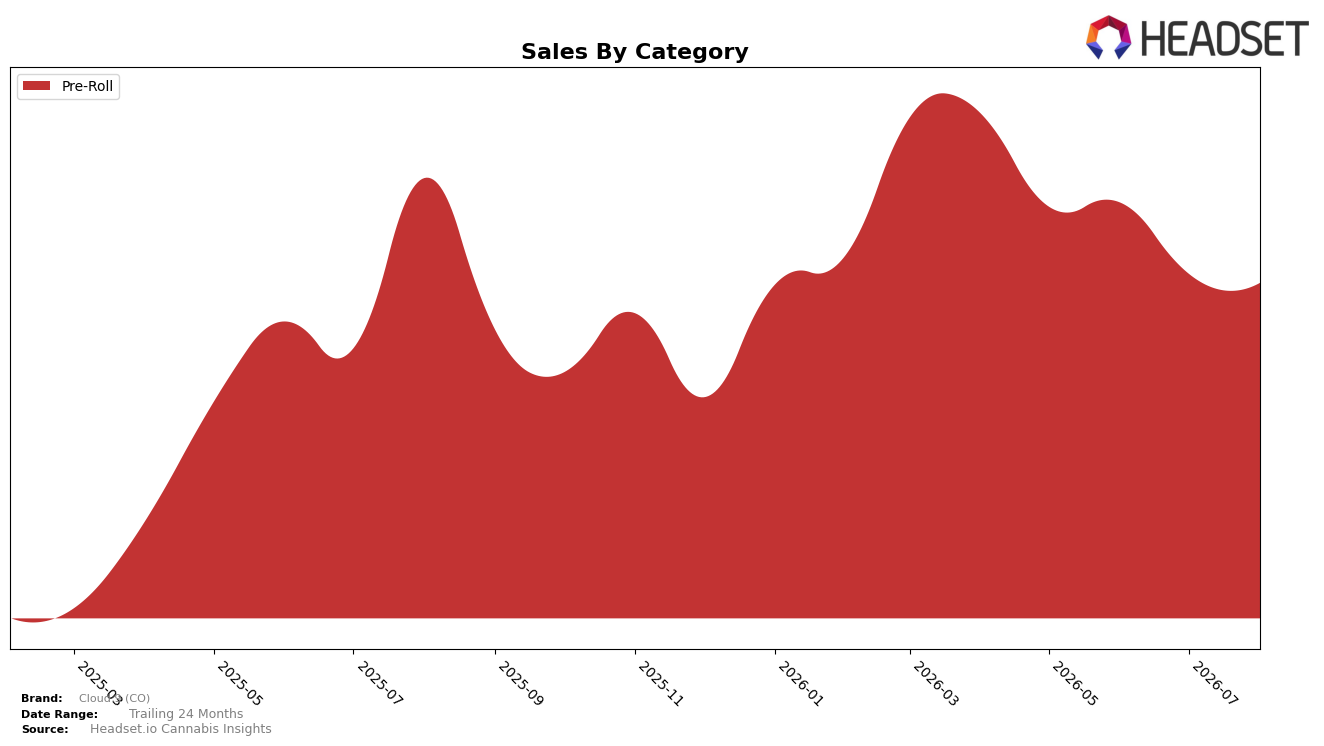
Cloud 9 (CO) concentrated entirely in Pre-Roll during August 2026 with a 100.0% mix, while category-level performance showed a -23.65% year-over-year sales change and a -2.57% month-over-month move alongside a -4.56% average price shift year over year. Within Colorado Pre-Roll, the brand held rank 27, and the month-over-month decline of -2.57% against a full-category allocation implies limited diversification upside in the short term. The pattern suggests a single-category dependency where the -23.65% YoY drawdown paired with a 100.0% mix compresses flexibility, and rank 27 sets a ceiling on near-term volume recapture unless mix or pricing strategy evolves.
The combination of a -4.56% YoY price decrease and a -23.65% YoY sales decline, together with a -2.57% MoM sales dip in a fully Pre-Roll-weighted portfolio, points to positioning pressure concentrated in value tiers rather than premium recovery. Holding rank 27 in Colorado Pre-Roll while carrying 100.0% category exposure indicates that incremental gains likely depend more on sub-segment mix within Pre-Roll than on broad market tailwinds, implying that price architecture and pack-size or strain-led differentiation are the primary levers for share lift rather than expansion into adjacent categories in the immediate term.
Competitive Landscape
Cloud 9 (CO) sits at rank #27 in Colorado Pre-Roll for August 2026, down 3 positions year over year from #24 and 2 positions from May 2026’s #25, while still trailing its March 2026 peak of #17 by 10 ranks; by contrast, Cali-Blaze moved up from #3 to #2 and Green Dot Labs advanced from #4 to #3 alongside a 55.1% YoY sales increase, whereas Kaviar slid from #2 to #4 with a 41.5% YoY sales decline. With Be One Kind leaping from #28 to #5 amid a 292.8% YoY sales surge and Green Label Cannabis holding #1 despite a 30.1% YoY sales contraction, the spread between upwardly mobile challengers and contracting incumbents suggests Cloud 9 (CO)’s 3-rank YoY decline and 2-rank slide since May 2026 indicate erosion of relative momentum unless assortment or pricing repositions the brand back toward its March 2026 trajectory.

Notable Products
Glue Trap x Dry Ice Pre-Roll (1g) posted the steepest move in August 2026 with a -88.1% month-over-month drop while sitting at rank 8, contrasted by Monkey Spunk Pre-Roll (1g) surging +98.3% to rank 1 and generating $28,284. Two SKUs moved more than 50% in opposite directions (+98.3% and -88.1%), and MAC Flurry x 98' Bubba Pre-Roll (1g) also fell -52.3% at rank 7, signaling a polarization within the lineup. With Pre-Rolls occupying all ten top spots, the assortment is concentrated in a single category even as rank 2 rose +38.1% MoM and rank 1 improved to the top position. The pattern implies Cloud 9 (CO) is leaning into a hit-driven Pre-Roll strategy where a few leaders gain share while underperformers are pruned or rotated quickly.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

