

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Is this your brand?
See your full sales and distribution data: where you sell, how you're priced, and how you rank against the brands next to you on the shelf.
See your brand's dataCarry this brand in your store?
Headset Retailer is free. Connect your POS and see what's selling and what's sitting.
Sign up freeWhere to Buy
Hi Lo is stocked at 40 licensed dispensaries across Massachusetts, with the deepest coverage in Boston, Quincy, Taunton, Abington, and Beverly. Search by ZIP code or city below to find the closest one.
Market Insights Snapshot
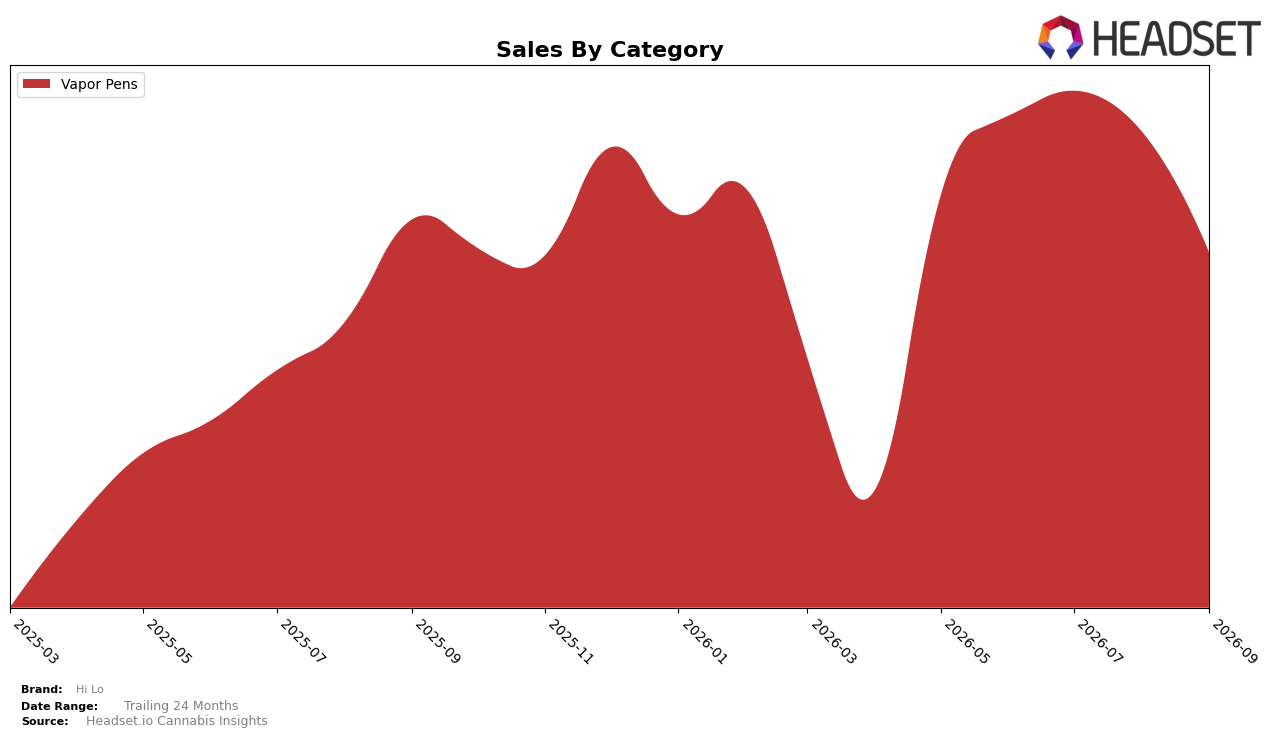
Hi Lo’s category mix in September 2026 is fully concentrated in Vapor Pens at 100.0% share, with category sales down 7.66% year over year and down 23.18% month over month, while average price declined 4.92% YoY to $35.27. Within Massachusetts Vapor Pens, the brand sits at rank 34, indicating a mid-pack placement relative to peers despite the MoM drop; the combination of a 7.66% YoY sales contraction and a 4.92% YoY price decline implies volume did not backfill price cuts. The thesis is that single-category concentration amplifies exposure to intra-category price compression and demand volatility, with rank 34 signaling limited insulation from month-to-month swings.
These shifts imply Hi Lo’s positioning relies on Vapor Pens price elasticity that is currently unfavorable, as a 4.92% YoY decrease in average price did not prevent a 7.66% YoY sales decline nor a 23.18% MoM retreat, and rank 34 in Massachusetts suggests competitive pressure is outpacing current pricing and mix choices. With 100.0% of sales in Vapor Pens and a month-to-month contraction exceeding 20%, the brand’s exposure to a single segment elevates risk and limits cross-category buffering. The thesis is that sustaining or improving rank will require either price-pack architecture or assortment differentiation within Vapor Pens since category diversification is currently zero.
Competitive Landscape
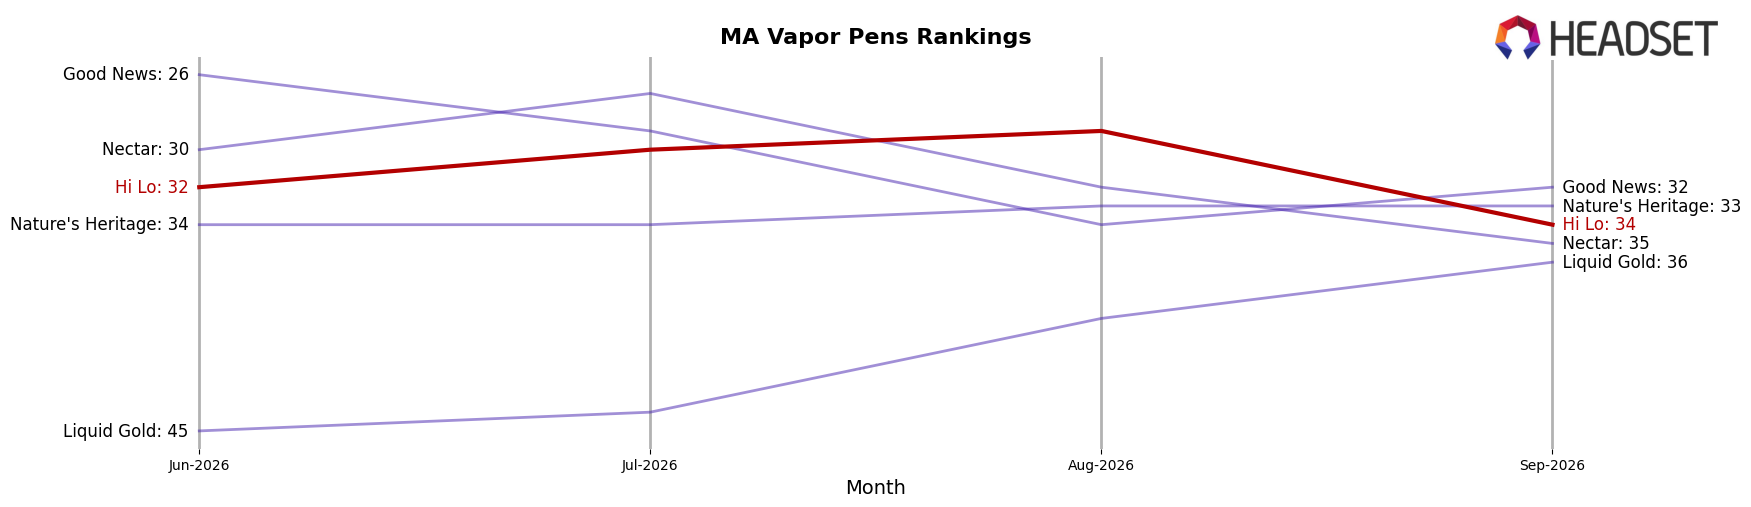
Hi Lo sits at rank #34 in MA Vapor Pens in September 2026, slipping 1 position YoY from #33 and down 2 spots from #32 three months ago, while the brand’s peak at #27 in February 2026 marks a 7-rank retreat since that high. Against this backdrop, Fernway held #1 YoY and in September 2026 as its sales rose 43.6%, and Jeeter surged from #23 YoY to #4 alongside a 421.5% sales increase, indicating that share is consolidating upward among leaders as Hi Lo drifts downward; the pattern implies Hi Lo’s rank trajectory is one of gradual erosion in a market where faster-moving rivals are pulling the ladder up.
Notable Products
Banana Candy Distillate Disposable (1.5g) posted the standout move in September 2026 with a +71.7% month-over-month surge and rose to rank 4, while category leader Peach Rings Distillate Disposable (1.5g) fell -41.8% at rank 1. Watermelon Splash Distillate Disposable (1.5g) dropped -32.8% at rank 2 as Honeydew Distillate Disposable (1.5g) inched up +9.7% at rank 3. Five of the top six SKUs are Vapor Pens, indicating a concentrated portfolio where volatility at the top is being counterbalanced by an emerging mid-pack mover, implying Hi Lo is leaning into flavor rotation within Vapor Pens to stabilize share.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

