


Market Insights Snapshot
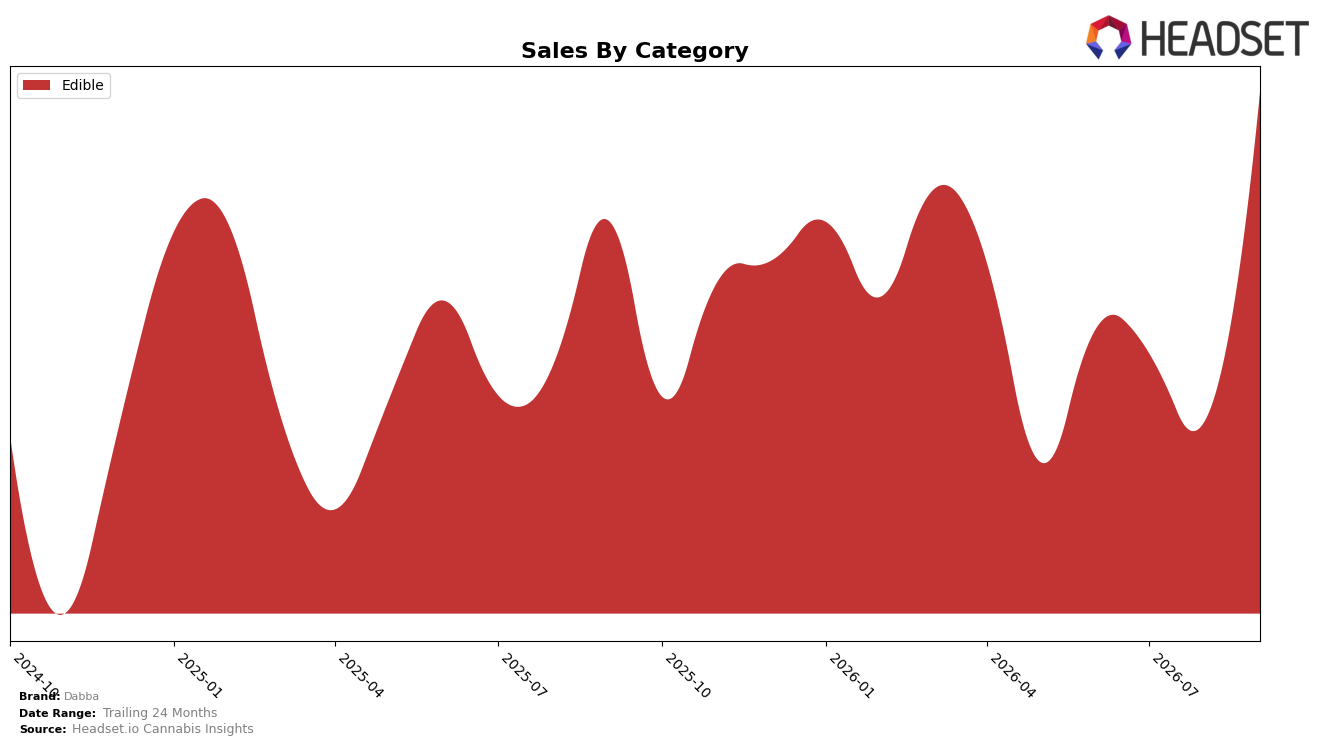
In September 2026, Dabba’s mix concentrated entirely in Edible, with category share at 100.0% and year-over-year sales growth of 26.5% alongside a month-over-month jump of 116.7%. The average price fell 7.9% YoY to $14.42, while rank in Colorado Edible sat at 36, placing the brand in the lower third of the leaderboard even as sales rose. The pattern implies that Dabba’s volume-driven gains in Edible are offset by price compression and a single-category dependency that caps rank mobility despite the 26.5% YoY and 116.7% MoM lifts.
The full Edible reliance and 7.9% YoY price decline, paired with a 36 rank in Colorado Edible, indicate a trade-up in unit velocity rather than mix expansion, with September 2026 momentum (116.7% MoM) driven by lower price points rather than category breadth. Given 24-month sales down 7.1% against a current-month YoY of 26.5%, the thesis is that Dabba’s positioning has pivoted toward price-accessible Edibles, which can deliver short-term share defense but leaves exposure to further price resets and limits cross-category insulation.
Competitive Landscape
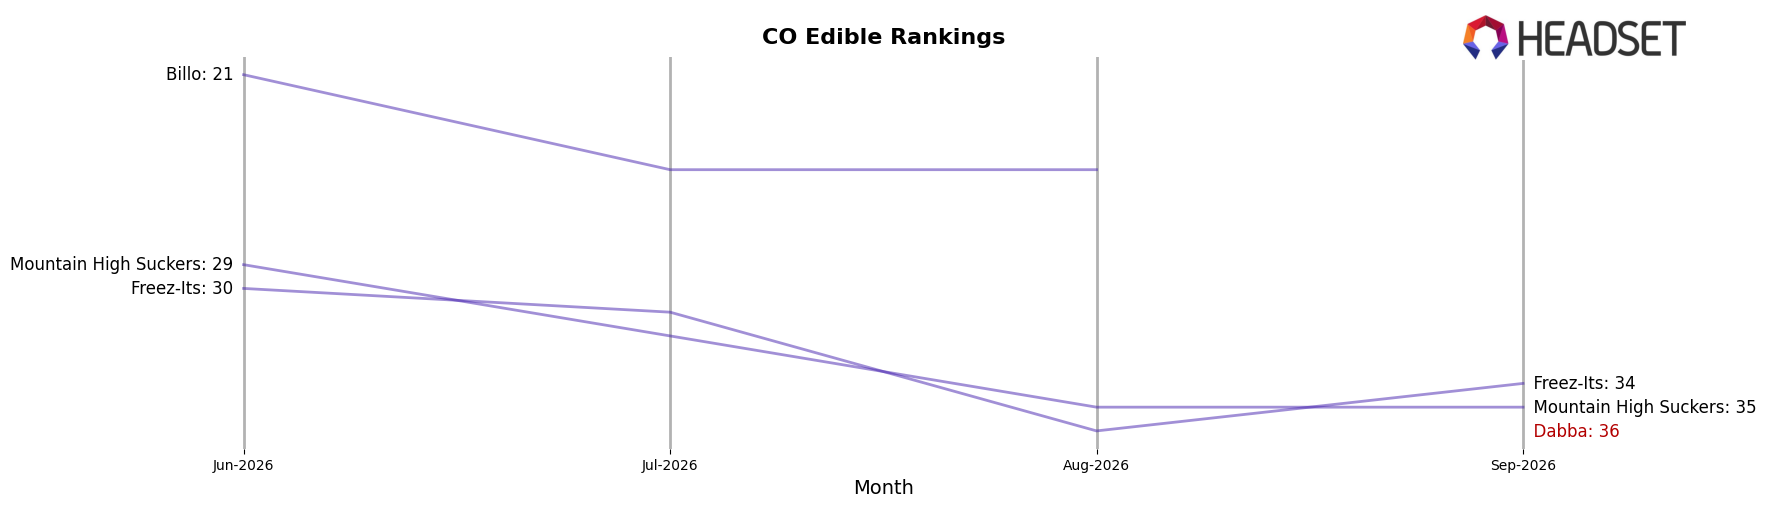
Dabba sits at rank #36 in Colorado Edible for September 2026, a 6-position climb from #42 in September 2025, and up 1 spot from #37 in June 2026; this is also a peak rank for the period, indicating recent momentum despite remaining outside the top 30. Competitively, Wana moved from #2 to #1 with a 10.5% year-over-year sales increase while Wyld slipped from #1 to #2 alongside a 23.8% sales decline, and Dialed In Gummies held #3 with 30.8% growth; against this backdrop, Dabba’s 6-rank YoY improvement and 1-rank quarter-over-quarter uptick signal incremental share capture but a need to convert rank stability at #36 into sustained advances toward the top 25.
Notable Products
CBD/THCV/THC 1:1:2 Mint Chocolate 10-Pack (50mg CBD, 50mg THCV, 100mg THC) posted the largest month-over-month gain at +382%, yet it only reached rank 4 while Sweet Dreams - THC/CBN 2:1 Raspberry Dark Chocolate Bar 10-Pack (100mg THC, 50mg CBN) jumped +189% to take rank 1; this spread implies surging interest in function-forward variants but with leadership concentrated in sleep-oriented formulations. Balance- CBG/CBD/THC 1:1:1 Premium Mint Milk Chocolate Bar 10-Pack (100mg CBG, 100mg CBD, 100mg THC) rose +112% to rank 2, while THC/CBN/CBD 1:1:1 Dark Chocolate Raspberry 10-Pack (100mg CBN, 100mg CBD, 100mg THC) fell -55% to rank 5, showing that 1:1:1 blends bifurcated between premium adoption and portfolio pruning. Four of the top ten are Edible SKUs, and with September 2026 revenue led by a $3,514 flagship in rank 1 alongside triple-digit growth in two other top-4 items, the mix points to Dabba consolidating around high-potency, multi-cannabinoid chocolates optimized for distinct use-cases rather than broad-spectrum staples.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

