

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Pretty Dope is stocked at 95 licensed dispensaries across California, with the deepest coverage in Los Angeles, Long Beach, Modesto, San Bernardino, and Fresno. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
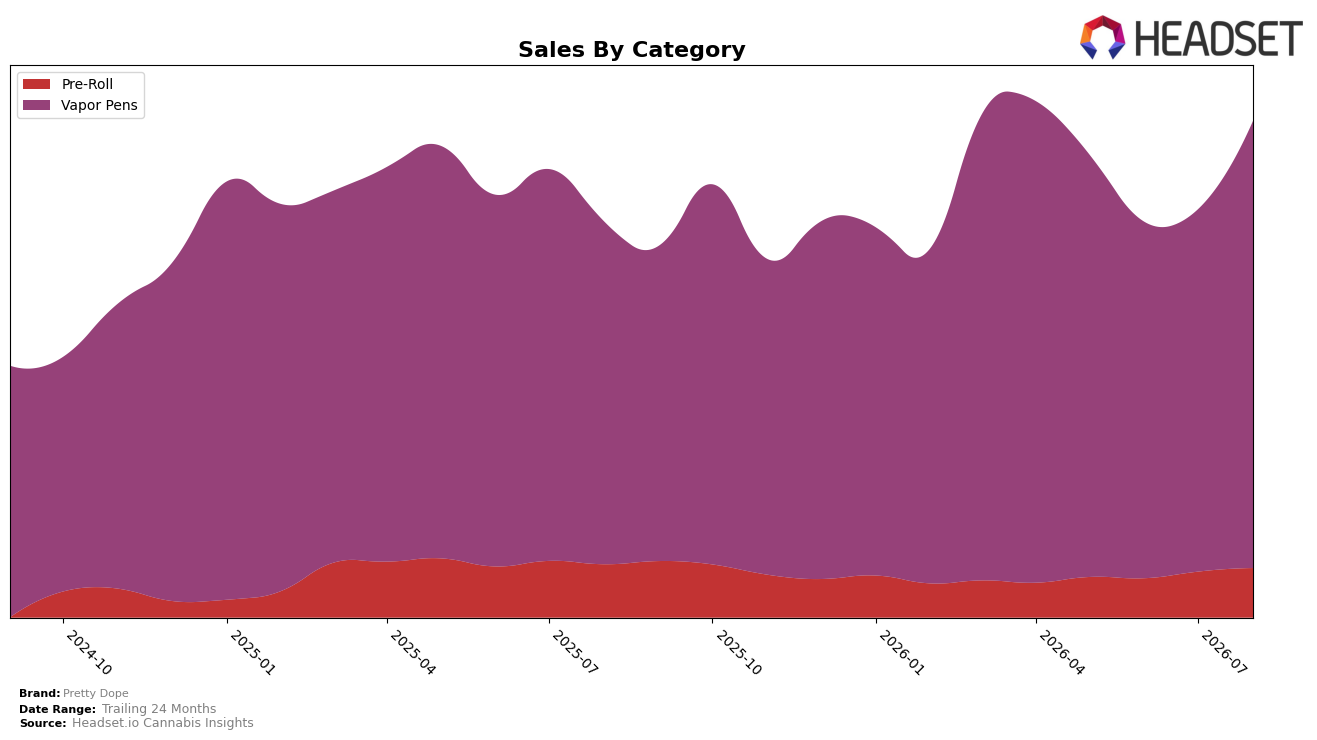
In August 2026, Vapor Pens accounted for 90.08% of Pretty Dope’s mix with year-over-year growth of 30.46% and month-over-month growth of 23.46%, while Pre-Roll held 9.92% with a year-over-year decline of 7.17% but month-over-month growth of 7.92%. The brand’s average price fell 5.34% year over year to $12.19, and overall brand sales grew 25.42% year over year alongside a 88.70% gain over 24 months. With Vapor Pens ranked 42 in California and the category contributing the vast majority of share, the pattern implies Pretty Dope is leaning into volume-led expansion in Vapor Pens, using price elasticity to gain mix while accepting Pre-Roll contraction on a yearly basis.
The combination of a 23.46% month-over-month surge in Vapor Pens and a simultaneous 7.92% month-over-month lift in Pre-Roll signals that August 2026 momentum is concentrated but not exclusive, with price strategy likely redirecting demand toward the higher-share format as the 5.34% price decrease widens the value gap. Given 30.46% year-over-year growth in Vapor Pens versus a 7.17% year-over-year decline in Pre-Roll, plus a 42nd rank in California Vapor Pens, the implication is that Pretty Dope’s competitive path depends on deepening presence where it already converts, prioritizing Vapor Pens assortment and distribution to climb ranks while treating Pre-Roll as a tactical, margin-managed adjunct rather than a growth engine.
Competitive Landscape
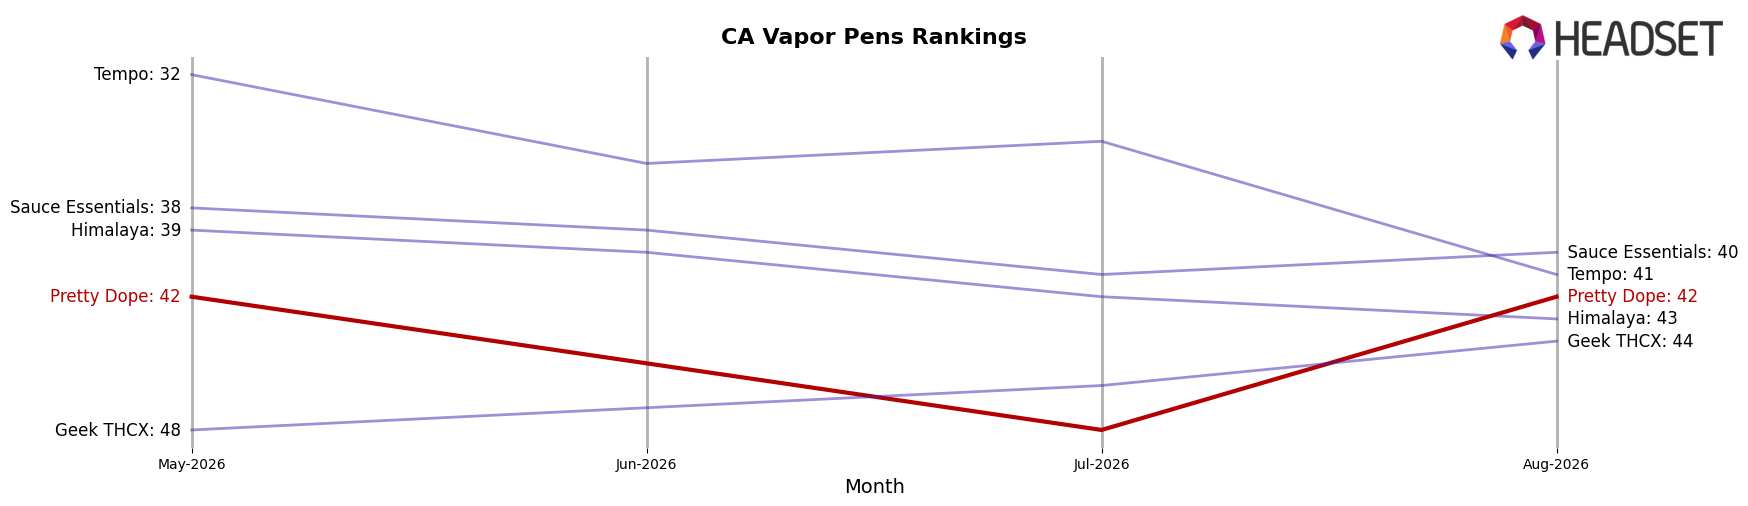
Pretty Dope sits at rank #42 in CA Vapor Pens in August 2026, a 3-position improvement from #45 year over year and flat versus May 2026 at #42, while still trailing its April 2026 peak at #37 by 5 slots; in the same window, Jetty Extracts climbed from #4 to #3 with a 40.5% YoY sales increase and Plug Play slipped from #3 to #4 with a 14.3% YoY decline, indicating mid-tier mobility is active above Pretty Dope’s lane. The combination of a modest 3-rank YoY gain and a 5-rank gap from the April 2026 peak implies a pause in upward momentum, suggesting that without incremental share wins against moving targets like Jetty Extracts’ +1 rank and Plug Play’s -1 rank, Pretty Dope’s trajectory points to stabilization rather than ascent.
Notable Products
Maui Wowie Distillate Cartridge (1g) posted the largest month-over-month gain at 55.8% while jumping into rank 6, and Grapealicious Distillate Cartridge (1g) followed with a 44.1% surge at rank 2, indicating sharp upside concentrated in mid-to-upper ranks rather than only at the top. Watermelon Mojito Distillate Cartridge (1g) held rank 1 with a 5.3% increase, and Forbidden Fruit Distillate Cartridge (1g) climbed 29.8% at rank 3, which together signals that growth is broadening across tiers rather than hinging on a single hero SKU. Four of the top ten are Vapor Pens in the top eight ranks, and the only decline among named items was Strawberry Mimosa Terpene Infused Pre-Roll (1g) at -3.2% in rank 5 with approximately $14,746 in August 2026 sales, implying portfolio gravity toward Vapor Pens is strengthening as Pre-Rolls provide smaller but stable support. The pattern points to a commercial direction that prioritizes accelerating Vapor Pen momentum with selective Pre-Roll maintenance to preserve shelf breadth without diluting the category that is compounding share gains.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

