


Market Insights Snapshot
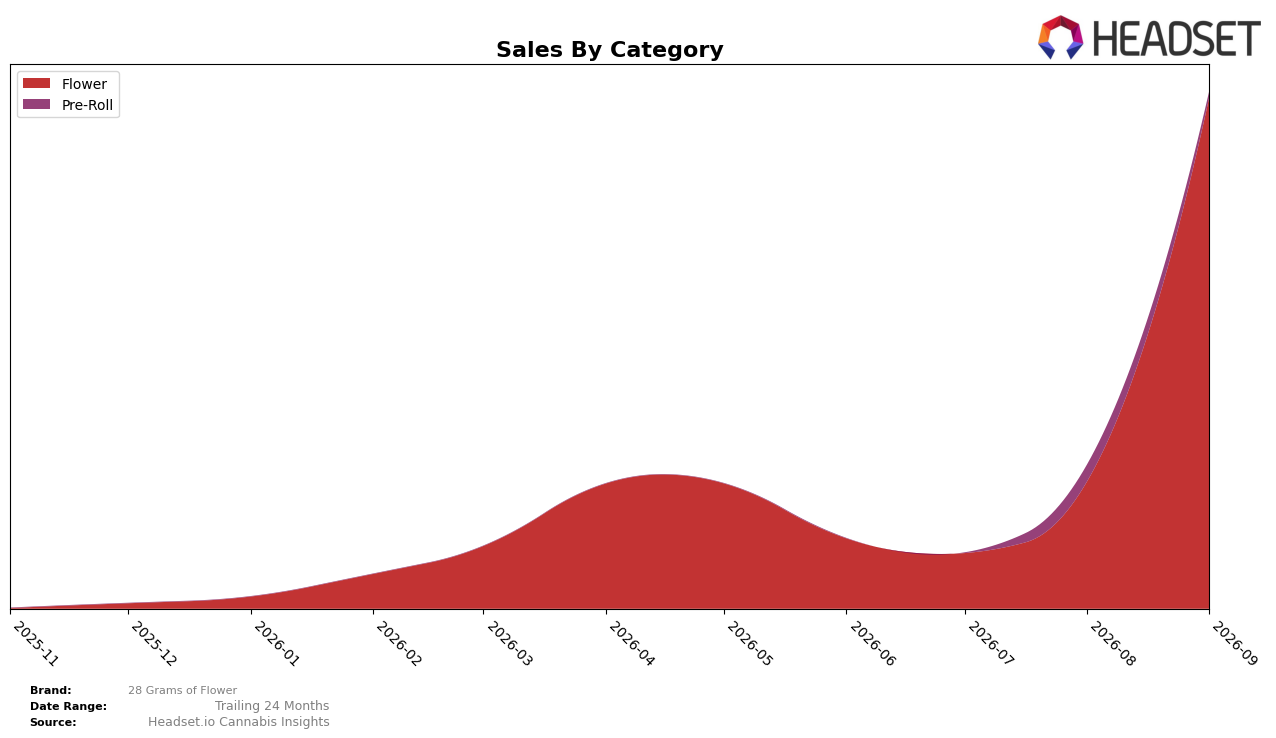
In September 2026, 28 Grams of Flower concentrated 98.85% share in Flower and 1.15% in Pre-Roll, with Flower surging 303.26% month over month while Pre-Roll fell 64.17% month over month. The brand held rank 21 in Flower within Illinois, and its average price sat at $81.43 versus $81.16 in Flower and $113.32 in Pre-Roll, placing the unit-price mix at a premium for Pre-Roll and near-par for Flower. The pattern implies an intentional pivot toward Flower volume as the core growth engine, while deprioritizing Pre-Roll despite its higher ticket, optimizing for rank movement in a category where the brand currently sits at position 21.
Given a 303.26% month-over-month lift concentrated in a 98.85% Flower mix alongside a 64.17% decline in a 1.15% Pre-Roll mix, the portfolio is trading depth for breadth within Flower to improve scale rather than margin per unit. With rank 21 in Illinois Flower and Pre-Roll priced 39.5% above the Flower average price ($113.32 vs $81.16), the shift indicates the brand is prioritizing competitive share capture where rank mobility is more attainable, using near-category-average pricing to reduce friction while allowing premium-priced Pre-Roll to shrink without materially impacting overall share.
Competitive Landscape
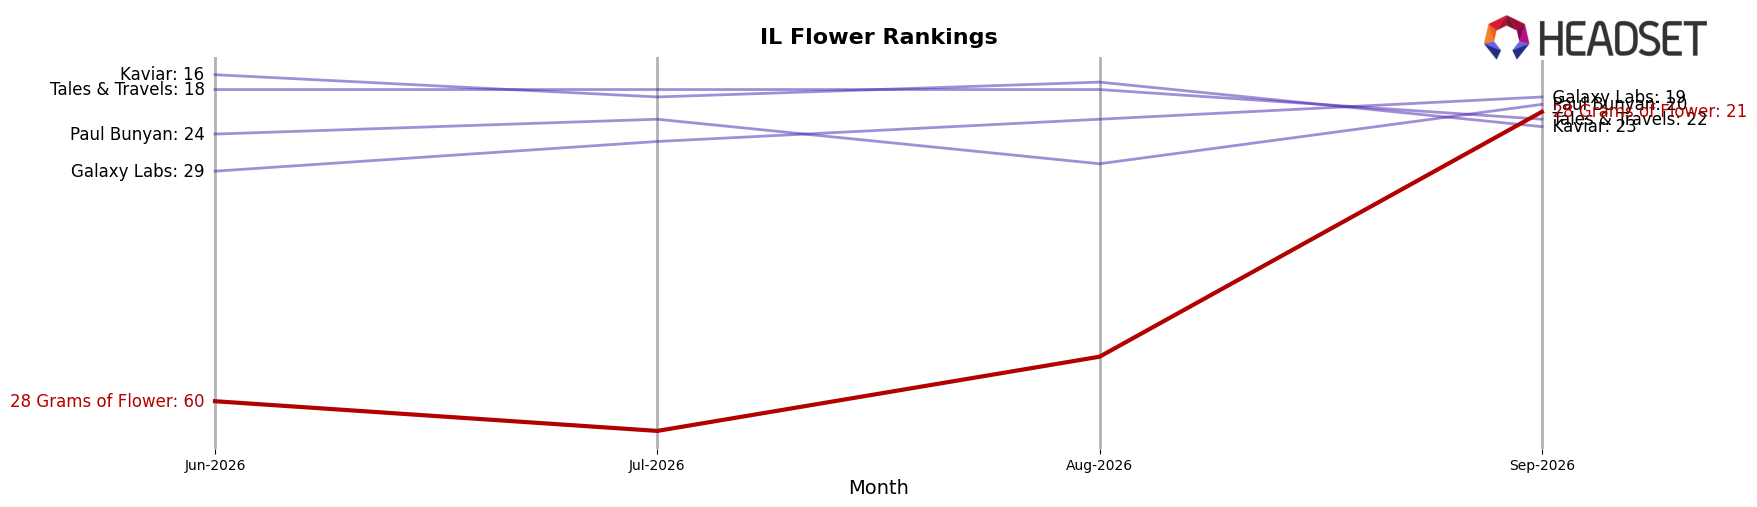
28 Grams of Flower sits at rank #21 in Illinois Flower in September 2026 after climbing 39 positions from #60 in June 2026, marking its peak rank of #21 in September 2026; while year-over-year rank is unavailable, the month-over-month trajectory suggests accelerated share capture. Against incumbents, High Supply / Supply holds #1 with a -2.5% year-over-year sales change as RYTHM maintains #2 with +22.0% year-over-year growth, and The Botanist surged to #4 from #27 year-over-year on +495.0% sales growth; in this context, 28 Grams of Flower’s jump from #60 to #21 within three months implies recent distribution or assortment gains that are outpacing mid-tier rivals despite top-tier consolidation.
Notable Products
Super Boof (14g) delivered the standout move in September 2026 with a month-over-month surge of 1,336.6% and a climb into rank 3, eclipsing the 914.7% jump of Banana Zoap (28g) at rank 2 and the 832.4% rise of Super Boof (28g) at rank 1. Dirty 30 (14g) added breadth with a 256.9% MoM increase at rank 5 while Somali Taxi Ride (28g) slid 49.1% to rank 9, creating a barbell of rapid gainers against a sharp decliner; together these shifts point to consumer preference consolidating around a few fast-scaling size/strain combinations. With Super Boof represented in two of the top three ranks and multiple 28g formats occupying four of the top ten, the assortment is tilting toward high-volume ounces and select strain families. The pattern implies 28 Grams of Flower is concentrating demand into flagship strains and larger pack sizes, favoring scale efficiency over a wide tail of slower movers.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

