


Where to Buy
Calamity Jane is stocked at 11 licensed dispensaries across New York, with the deepest coverage in Buffalo, New York, Binghamton, East Syracuse, and Jamestown. Search by ZIP code or city below to find the closest one.
Market Insights Snapshot
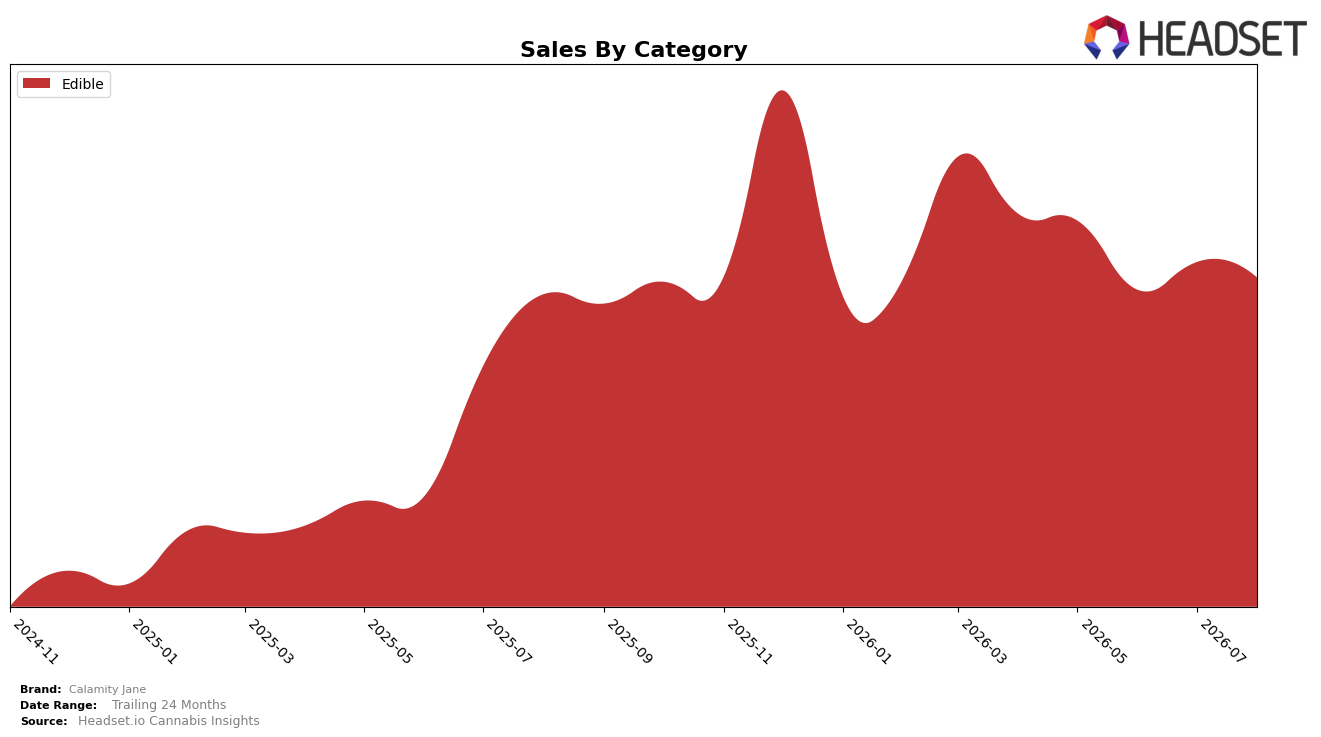
Calamity Jane operated as a single-category brand in August 2026, with Edible accounting for 100.0% of sales and posting year-over-year growth of 5.21% alongside a month-over-month decline of 4.48%. Within Edible, the average price fell 6.83% year over year to $19.35 while sales rose 5.21%, pointing to unit expansion despite price compression. The brand ranked 40 in Edible in New York for August 2026, while category share held at 100.0% and MoM momentum softened by 4.48%. The pattern implies Calamity Jane’s growth is volume-led within Edible, but August 2026 softness and a 40th rank indicate limited headroom without diversification or pricing recovery.
The shift toward lower average price (down 6.83% YoY) concurrent with Edible-only concentration (100.0% share) positions Calamity Jane as a value-access point in Edible rather than a premium or multi-category player, with rank 40 in New York reinforcing mid-to-lower tier placement. The 5.21% YoY sales gain against a 4.48% MoM dip suggests elasticity-driven unit gains that are vulnerable to monthly volatility and promotional cycles. The implication is that sustaining momentum will rely on maintaining price elasticity advantages and improving rank from 40 via mix depth within Edible (form factors, strengths, pack sizes) rather than pricing up, given the August 2026 pullback and the 6.83% YoY price decline.
Competitive Landscape
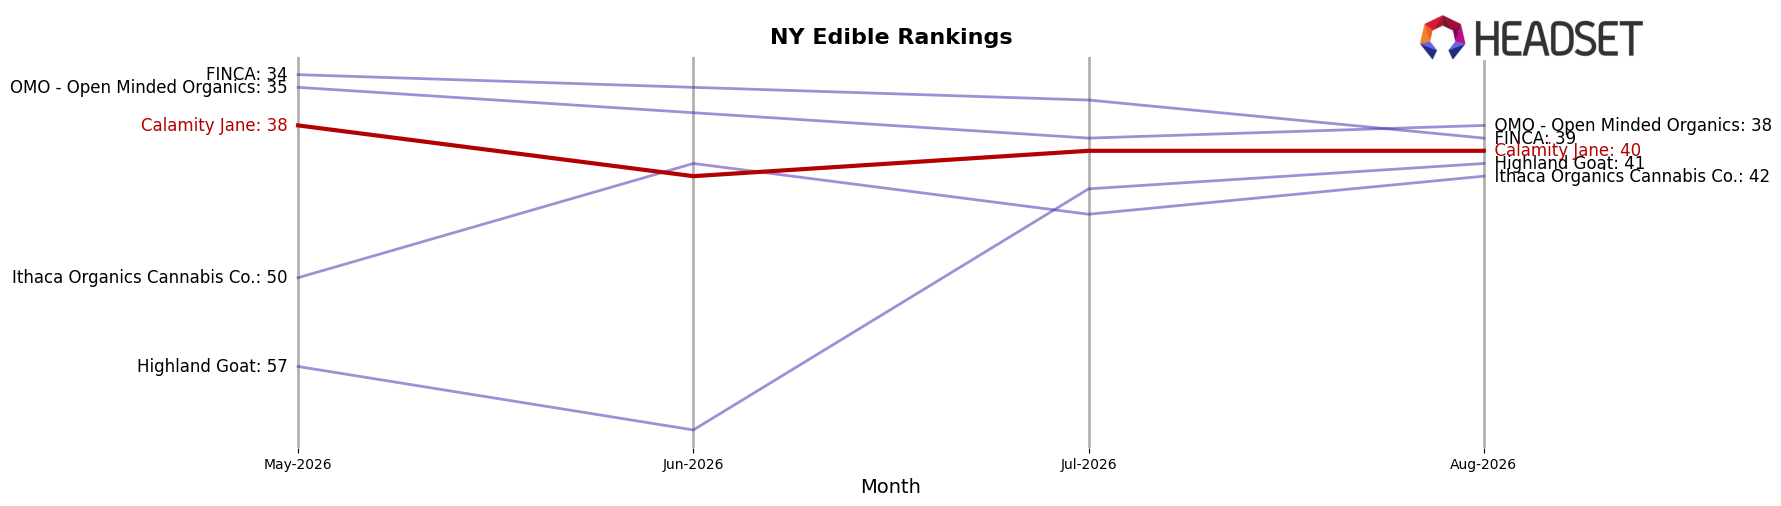
Calamity Jane sits at rank #40 in NY Edible for August 2026 with no year-over-year rank change from #40, while sliding 2 positions since May 2026 from #38 to #40; by contrast, Off Hours moved down from #1 to #2 year-over-year and Gron / Grön climbed from #4 to #3 alongside a 14.77% sales increase. Despite peaking at #35 in March 2026 and then relinquishing 5 positions by August 2026, Calamity Jane is tracking below the upward momentum of Gron / Grön and behind the stability at the top where Wyld holds #4 after rising from #3 year-over-year by 1 position; this flat YoY rank and recent slippage imply the brand is stuck in the lower tier, requiring a catalyst to re-enter the mid-30s.
Notable Products
THC/CBN 2:1 Nighttime Dark Bullet Bar Chocolate (100mg THC, 50mg CBN) led with a -29.98% month-over-month drop while still holding rank 1, and White Chocolate Cookies and Cream Bullet Bar 10-Pack (100mg) fell -43.02% to rank 9, indicating portfolio dependence on declining Bullet Bar formats despite top billing. Rocky Top Cookies & Cream White Chocolate Bites 10-Pack (100mg) rose 39.32% into rank 4 as CBD/THC 1:1 High Noon Calm Milk Chocolate Calm Bites 10-Pack (100mg CBD, 100mg THC) climbed 25.25% at rank 6, while CBG/THC 2:1 Prospector Milk Chocolate Toffee Crunch 10-Pack (100mg THC, 50mg CBG) slid -15.90% at rank 5, creating a split between bite-size momentum and bar softness; eight of the top ten are Edible SKUs with multiple 1:1 cannabinoid blends. Sleep - CBD/CBN/THC 1:1:1 Sundown Plain Dark Chocolate Bites 10-Pack (100mg CBN, 100mg CBD, 100mg THC) in rank 2 grew 2.01% on $8,963, while CBG/CBD/ THC 1:1:1 Blackjack Peanut Butter Bites Dark Chocolate 10-Pack (100mg CBG, 100mg CBD, 100mg THC) advanced 10.95% at rank 3, implying August 2026 product mix is tilting toward multi-cannabinoid bite formats as the bar sub-line contracts.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

