


Market Insights Snapshot
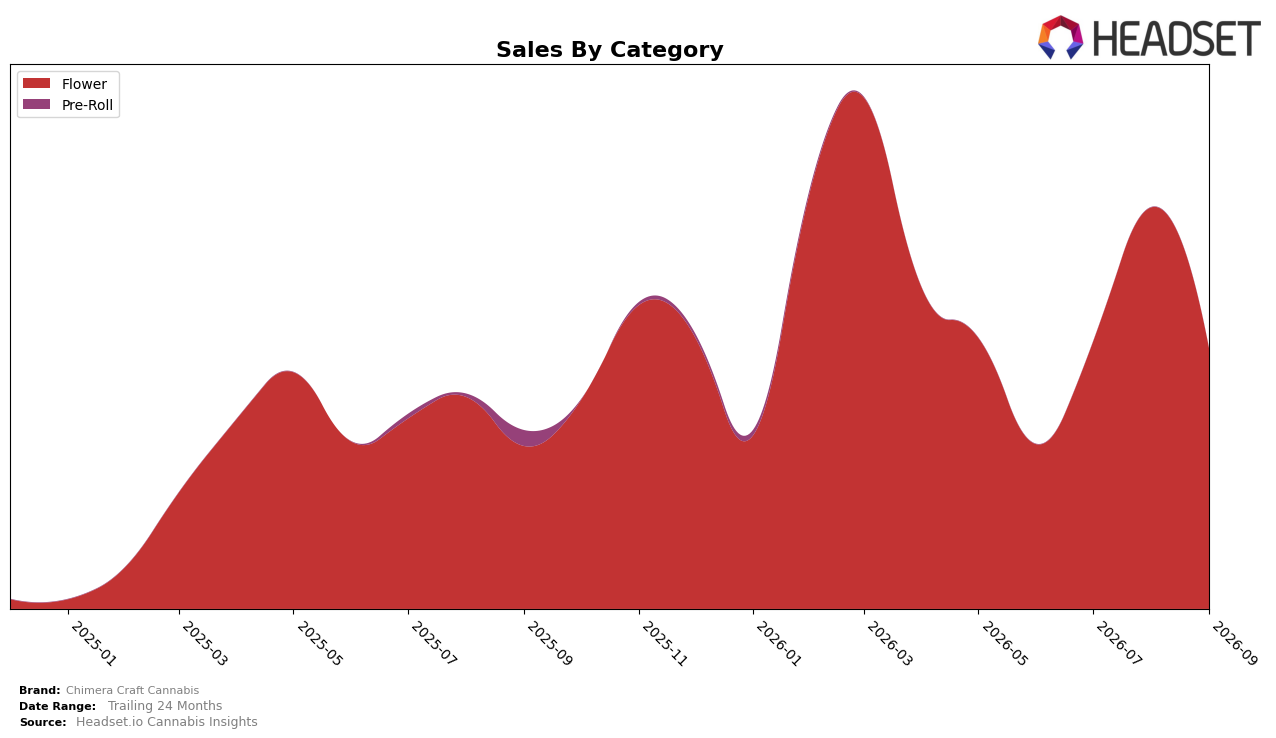
In September 2026, Chimera Craft Cannabis operated as a single-category brand with Flower at 100.0% of sales, posting a year-over-year Flower sales increase of 59.21% alongside a month-over-month decline of 35.54%. The brand’s overall sales rose 45.34% year over year while its average retail price rose 88.02%, indicating that price per unit expanded faster than sales volume and that September’s sequential pullback likely came from unit softness rather than pricing pressure. With Flower as the entire mix and an average price of $6.20, the combination of a triple-digit pricing uplift and a single-category footprint implies concentrated exposure to Flower demand cycles and sensitivity to monthly volatility.
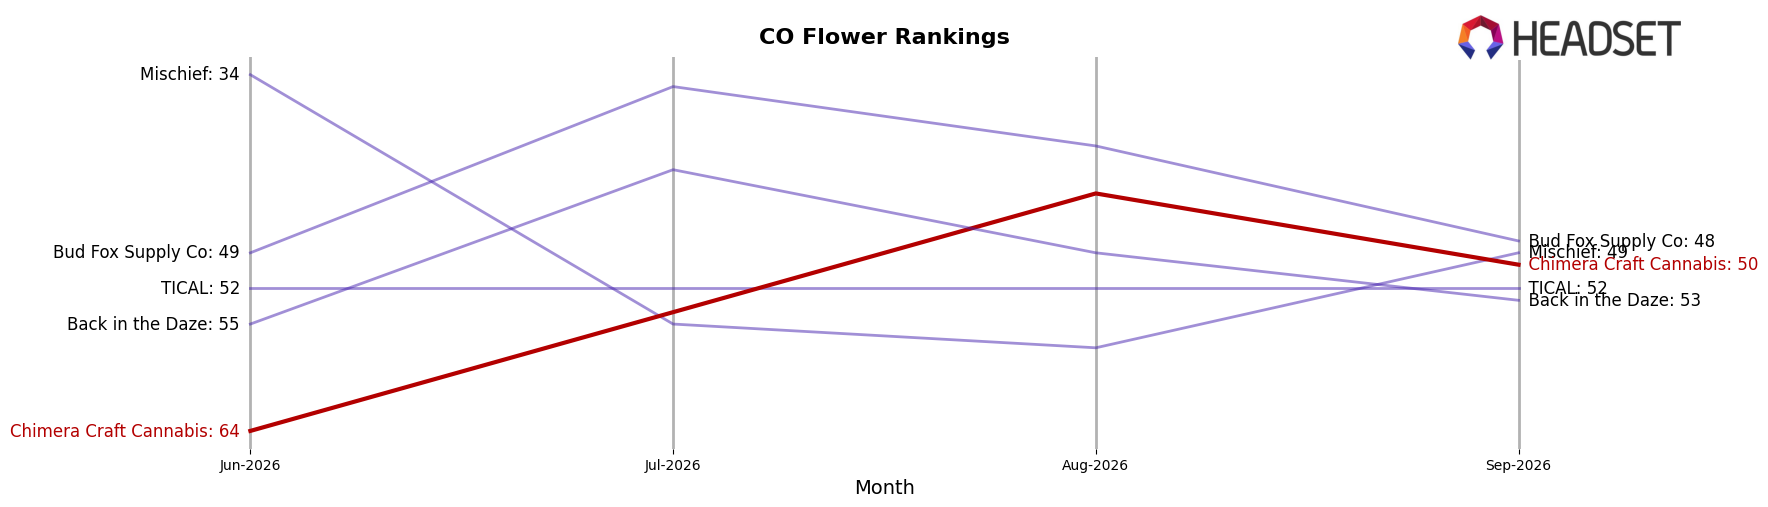
The concentration in Flower paired with a rank of 50 in Flower within Colorado suggests mid-pack placement where pricing strategy is a primary lever: the 88.02% year-over-year price increase alongside a 59.21% sales lift points to revenue driven more by pricing than volume, while the 35.54% month-over-month decline signals limited insulation from short-term category swings. This pattern implies that maintaining or improving rank will depend on stabilizing unit velocity within Flower while selectively calibrating price, because a single-category, 100.0% mix magnifies the impact of Flower’s month-to-month demand shifts on both share and rank.
Competitive Landscape
Chimera Craft Cannabis sits at rank #50 in Colorado Flower in September 2026, improving 26 positions from #76 year over year, and up 14 spots from #64 in June 2026; however, it remains below its peak of #39 reached in March 2026 and trails the top tier where Green Label Cannabis held #1 both this year and last while growing sales 38.0%, and Good Chemistry Nurseries advanced from #3 to #2 with 45.5% YoY sales growth. Against a rising challenger tier where In The Flow jumped from #12 to #5 on 113.5% YoY growth while Seed & Strain Cannabis Co. slid from #2 to #4 with a 33.5% sales decline, Chimera Craft Cannabis’s move from #76 to #50 indicates recovery but not breakout momentum, implying the brand is stabilizing mid-pack rather than converging toward the top 10 without a step-change in share capture.
Notable Products
Watermelon Hurricane (Bulk) posted the standout move in September 2026 with a +1852.2% month-over-month surge to rank 1, while Trail Mix Popcorn (1g) fell -53.6% to rank 3, indicating a sharp reallocation of demand toward a single bulk SKU at the top. Zoap (Bulk) declined -54.5% to rank 6 and Zoap Popcorn (1g) dropped -73.7% to rank 5, and with all ten top SKUs in Flower, the concentration implies reliance on format and strain rotation within one category rather than diversification. Trail Mix (Bulk) also slid -72.3% to rank 4 as Zoap (14g) entered at rank 7 with no prior baseline, suggesting unit-size shifts are redistributing share away from smaller popcorn packs toward bulk and larger formats. Taken together, the mix points to a pivot toward fewer, higher-volume Flower leaders driving September 2026 sell-through rather than a broad bench of steady mid-tier items.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

